

The NCERT PDF for Class 11 Accountancy Chapter 9 Financial Statements - II brings together the official 2026-27 chapter on adjustments in final accounts. It helps students revise outstanding expenses, prepaid expenses, accrued income, depreciation, bad debts, provisions, manager's commission and interest on capital before preparing adjusted financial statements.
- Core focus: adjustments before Trading Account, Profit and Loss Account and Balance Sheet.
- Practice value: students learn how one adjustment affects two final-account places.
- PDF use: keep the chapter open while solving adjusted final accounts.
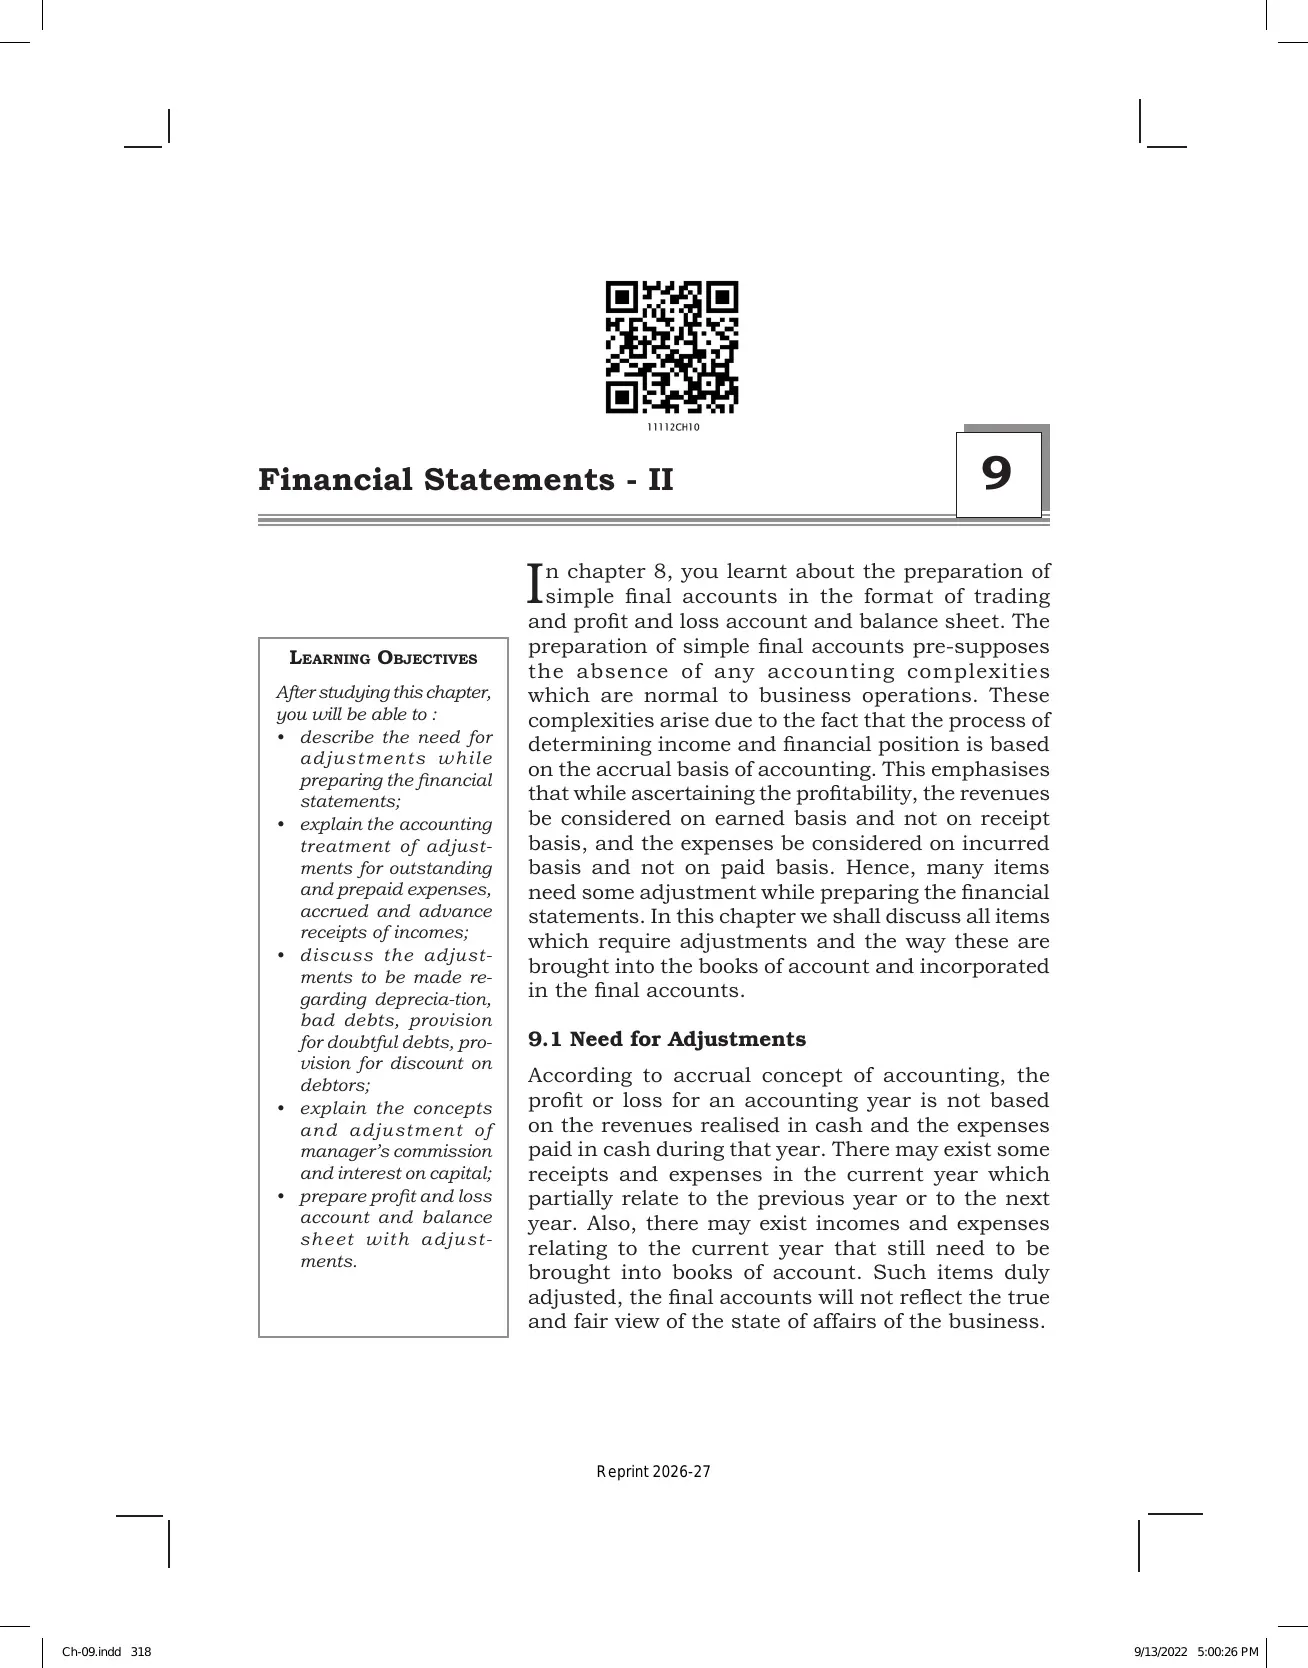
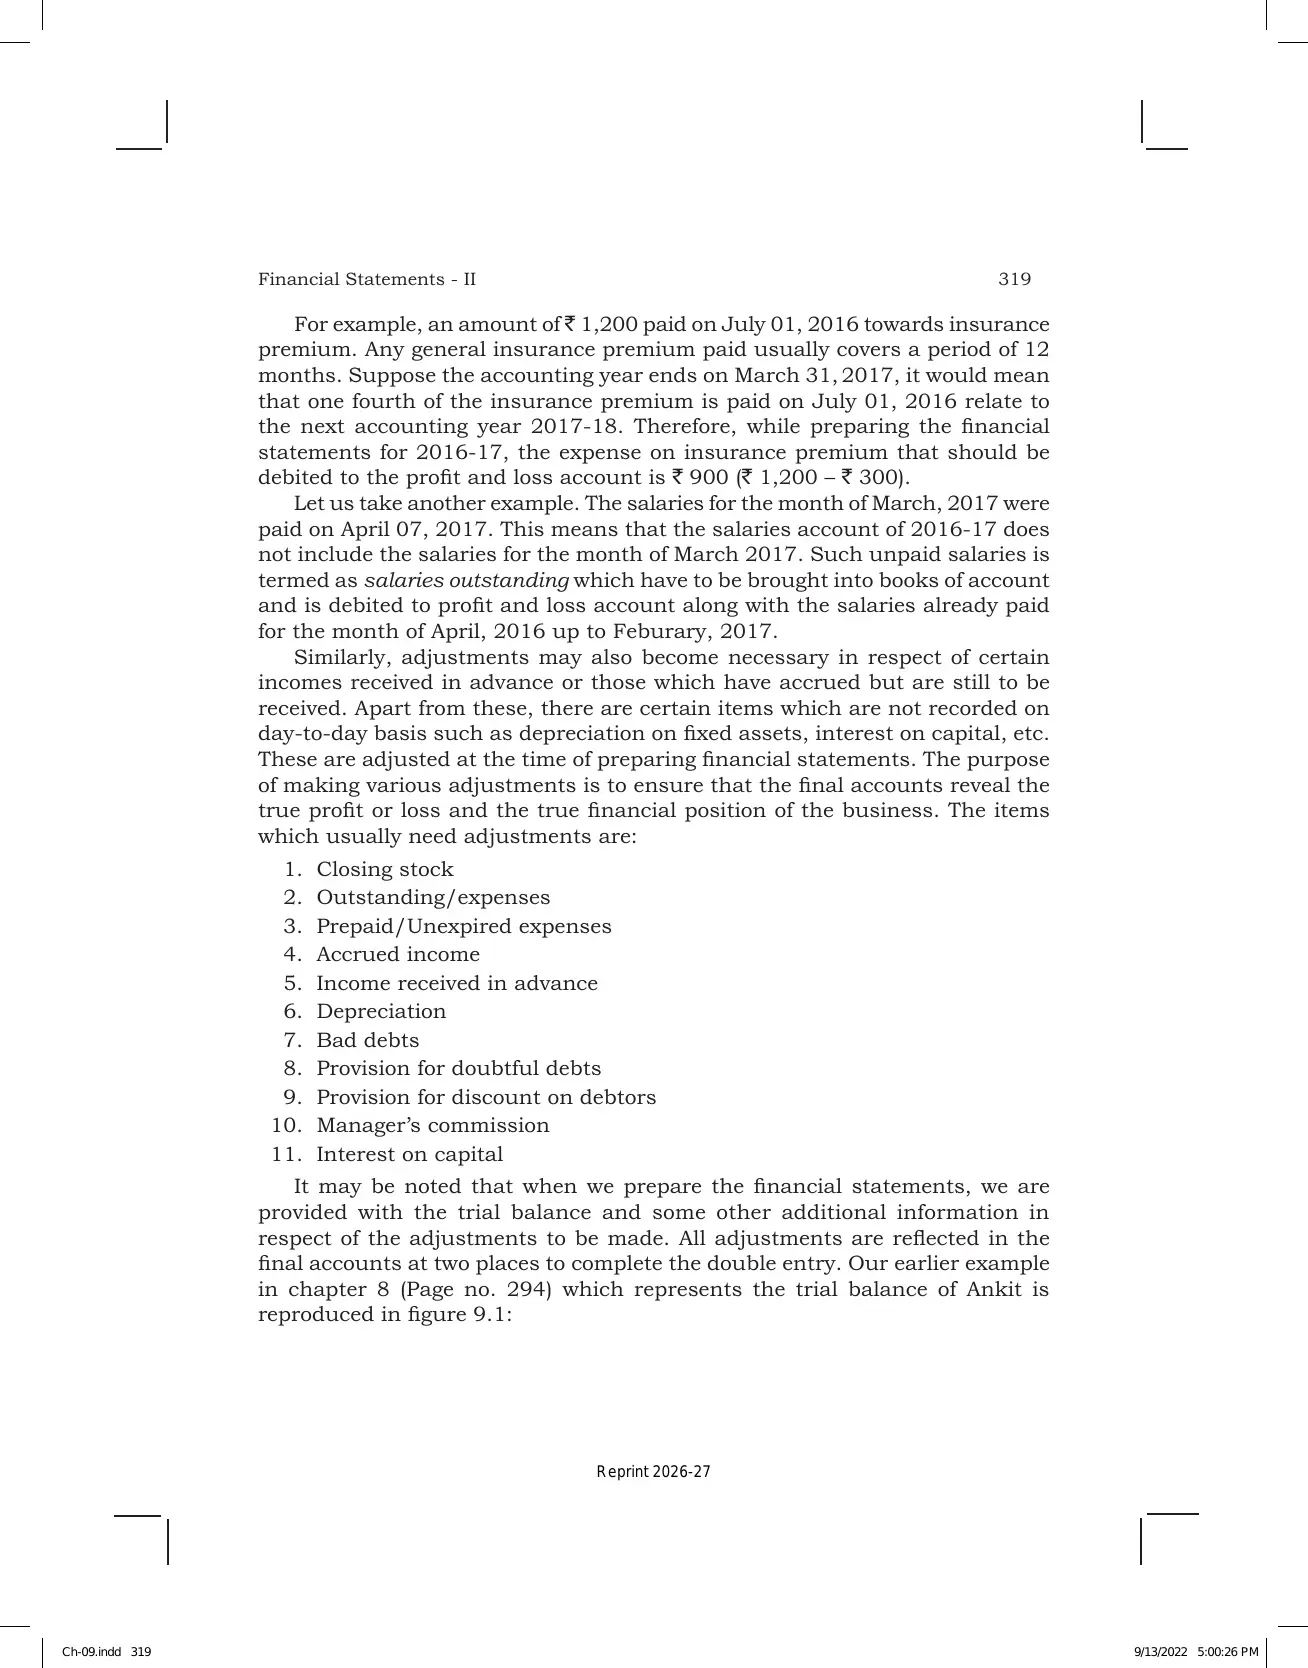
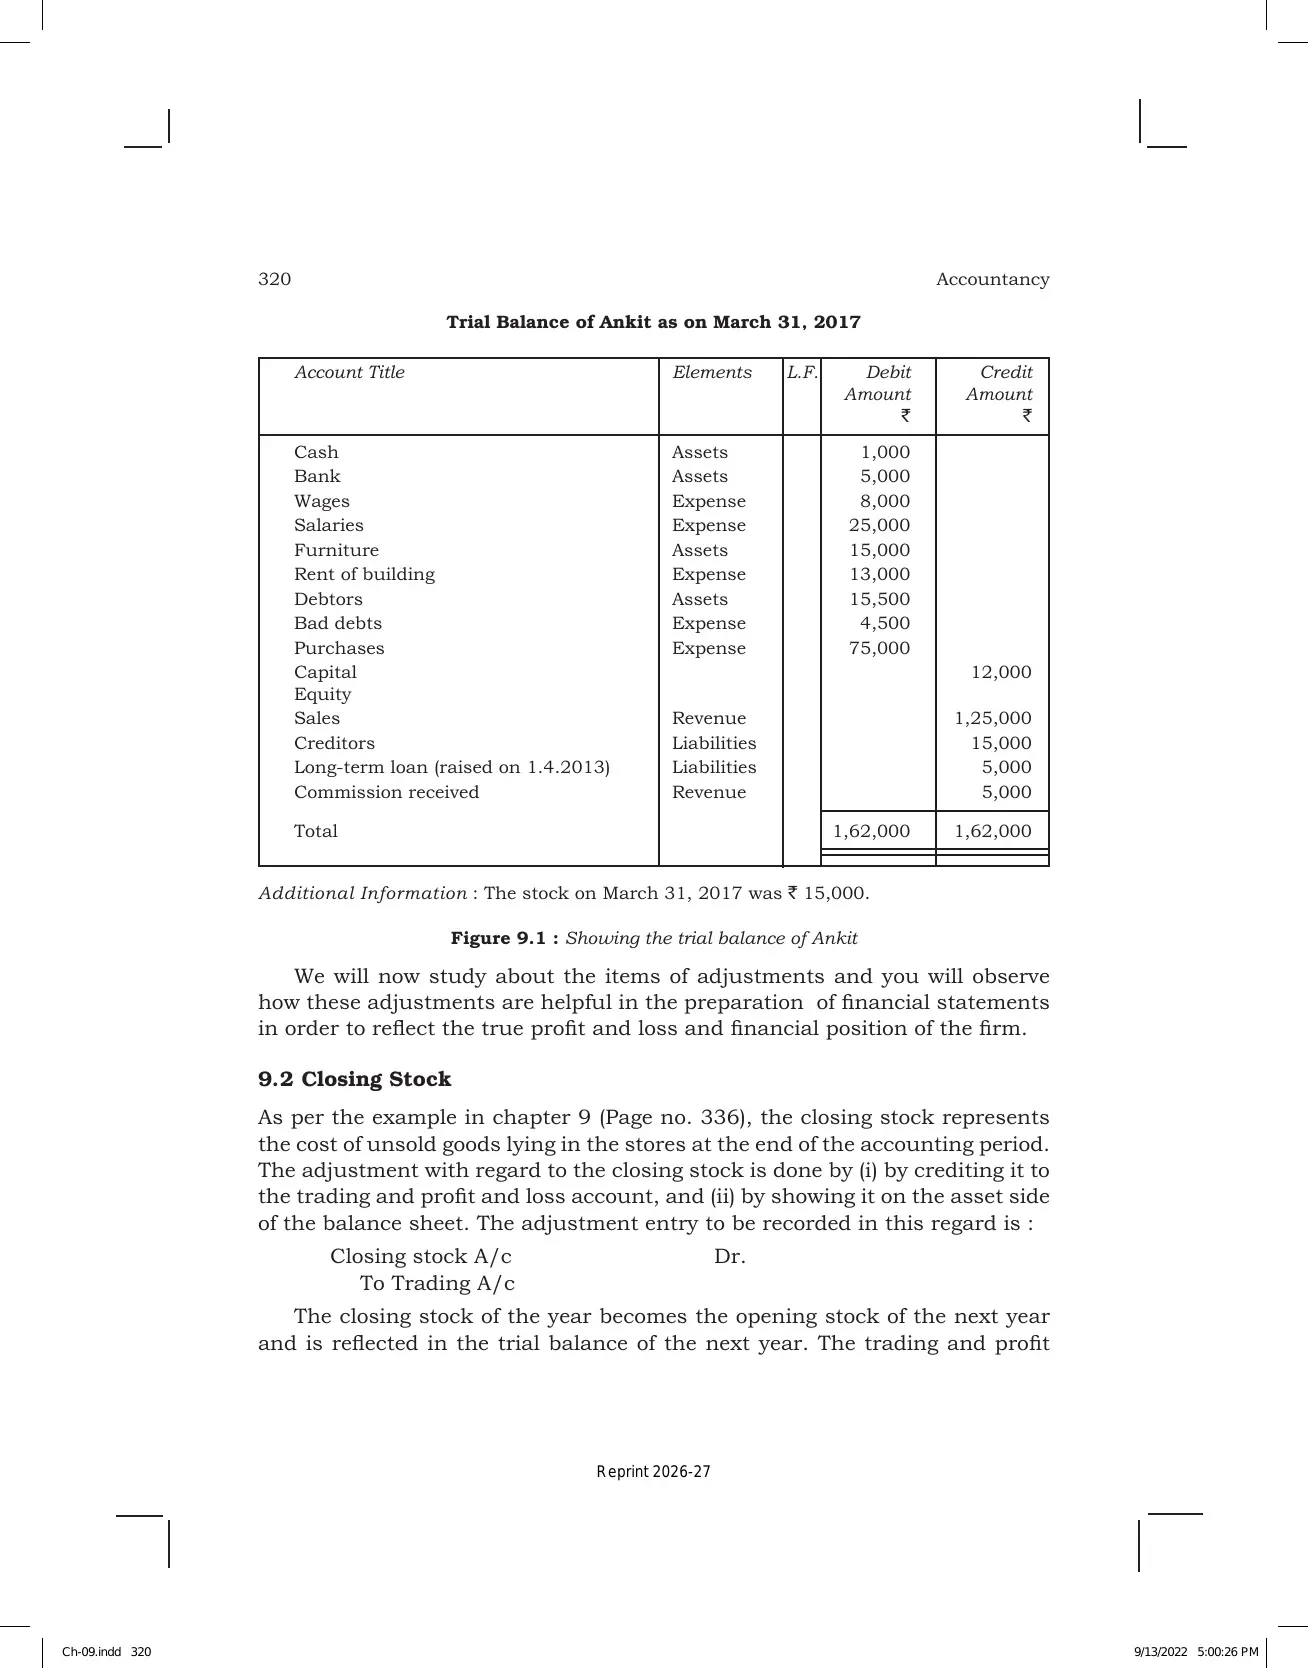
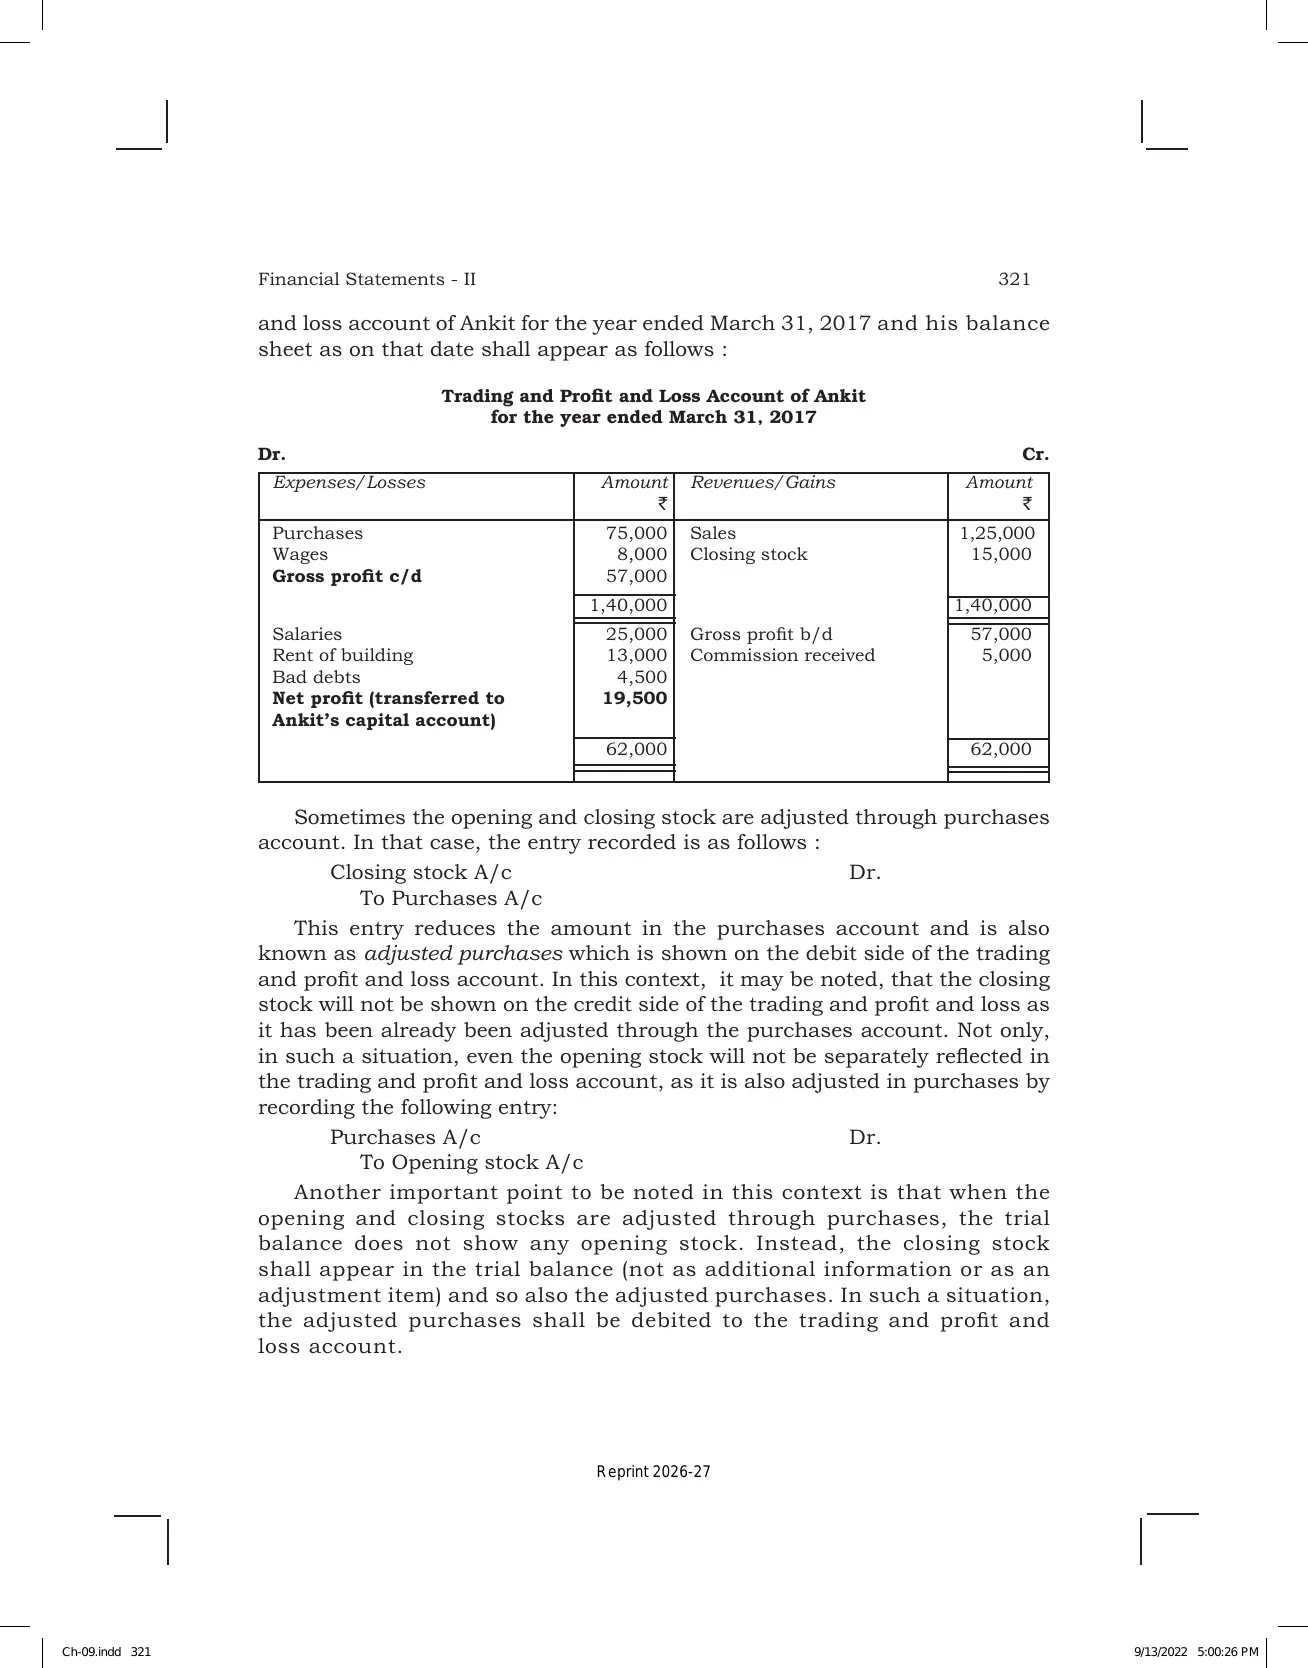
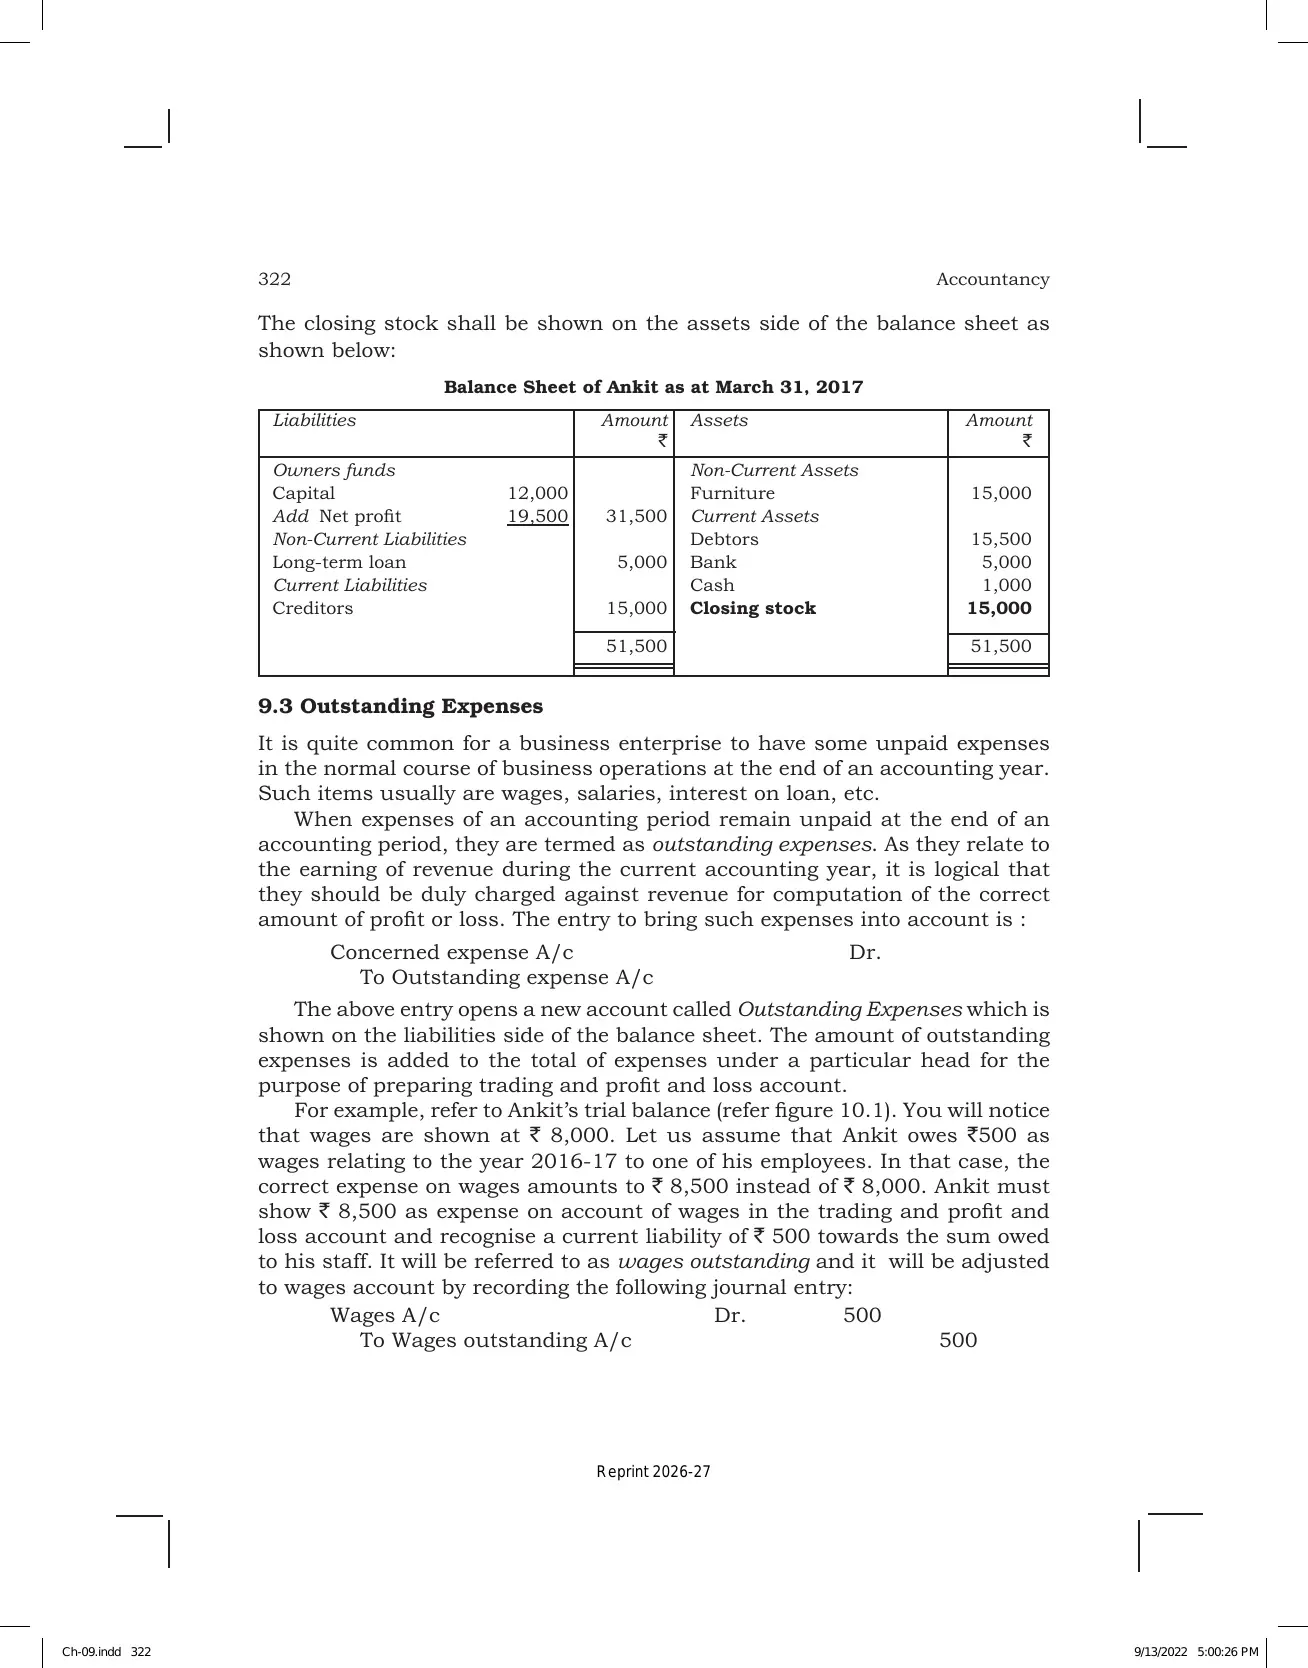
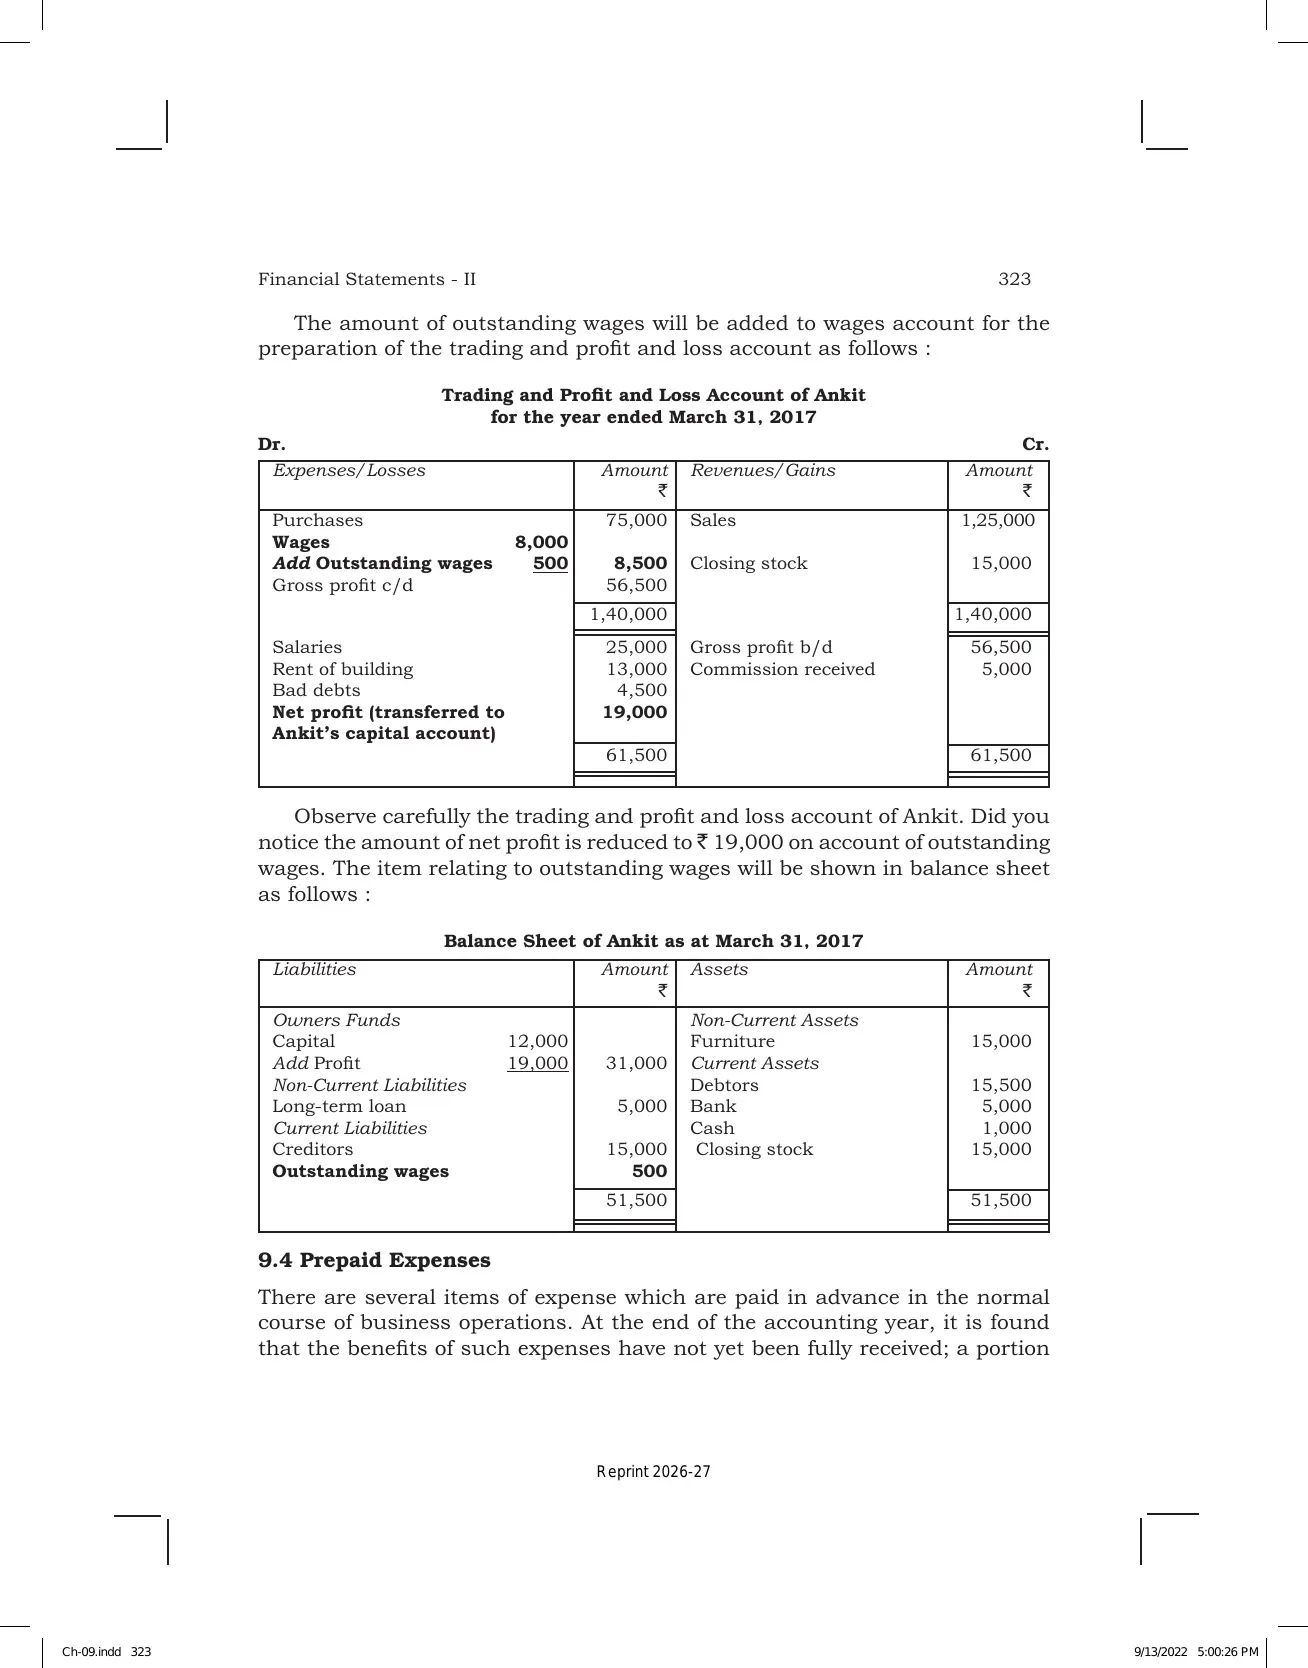
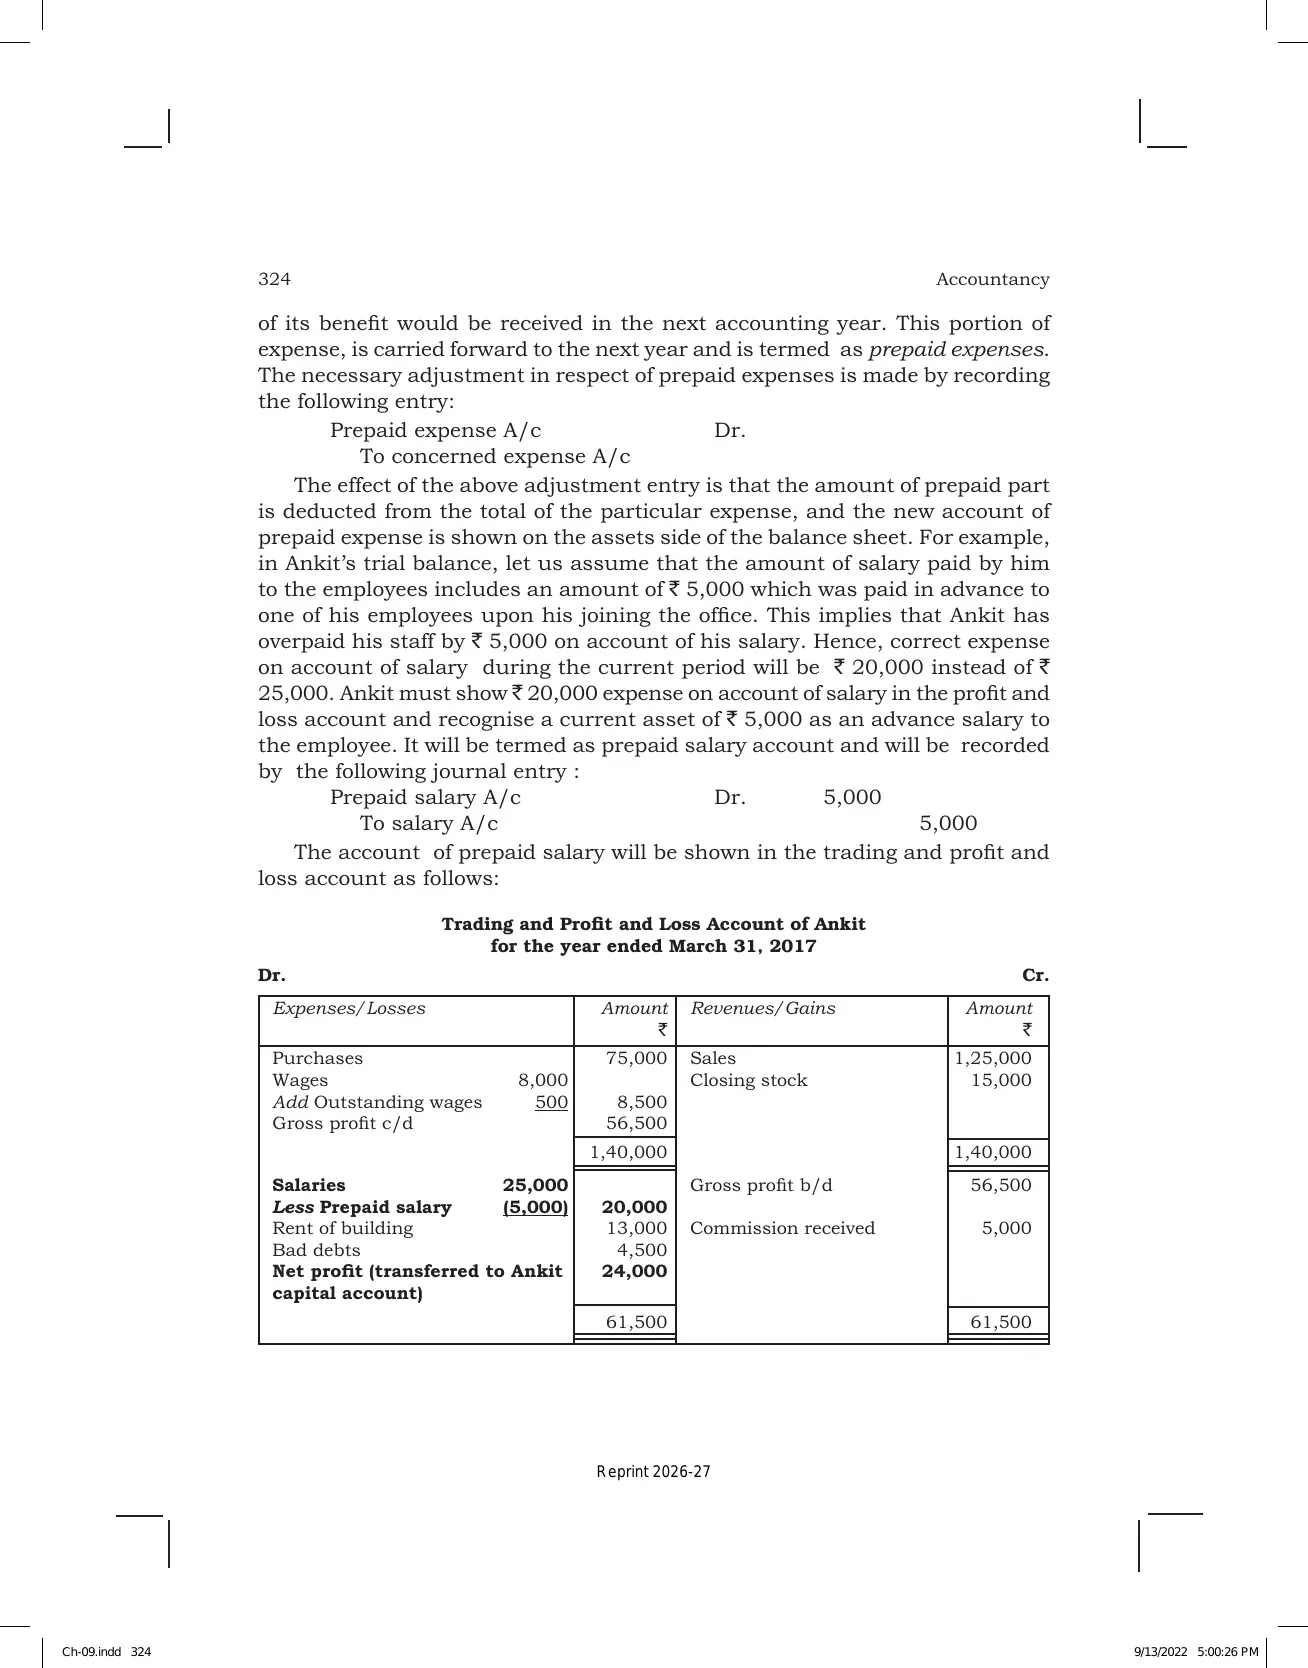
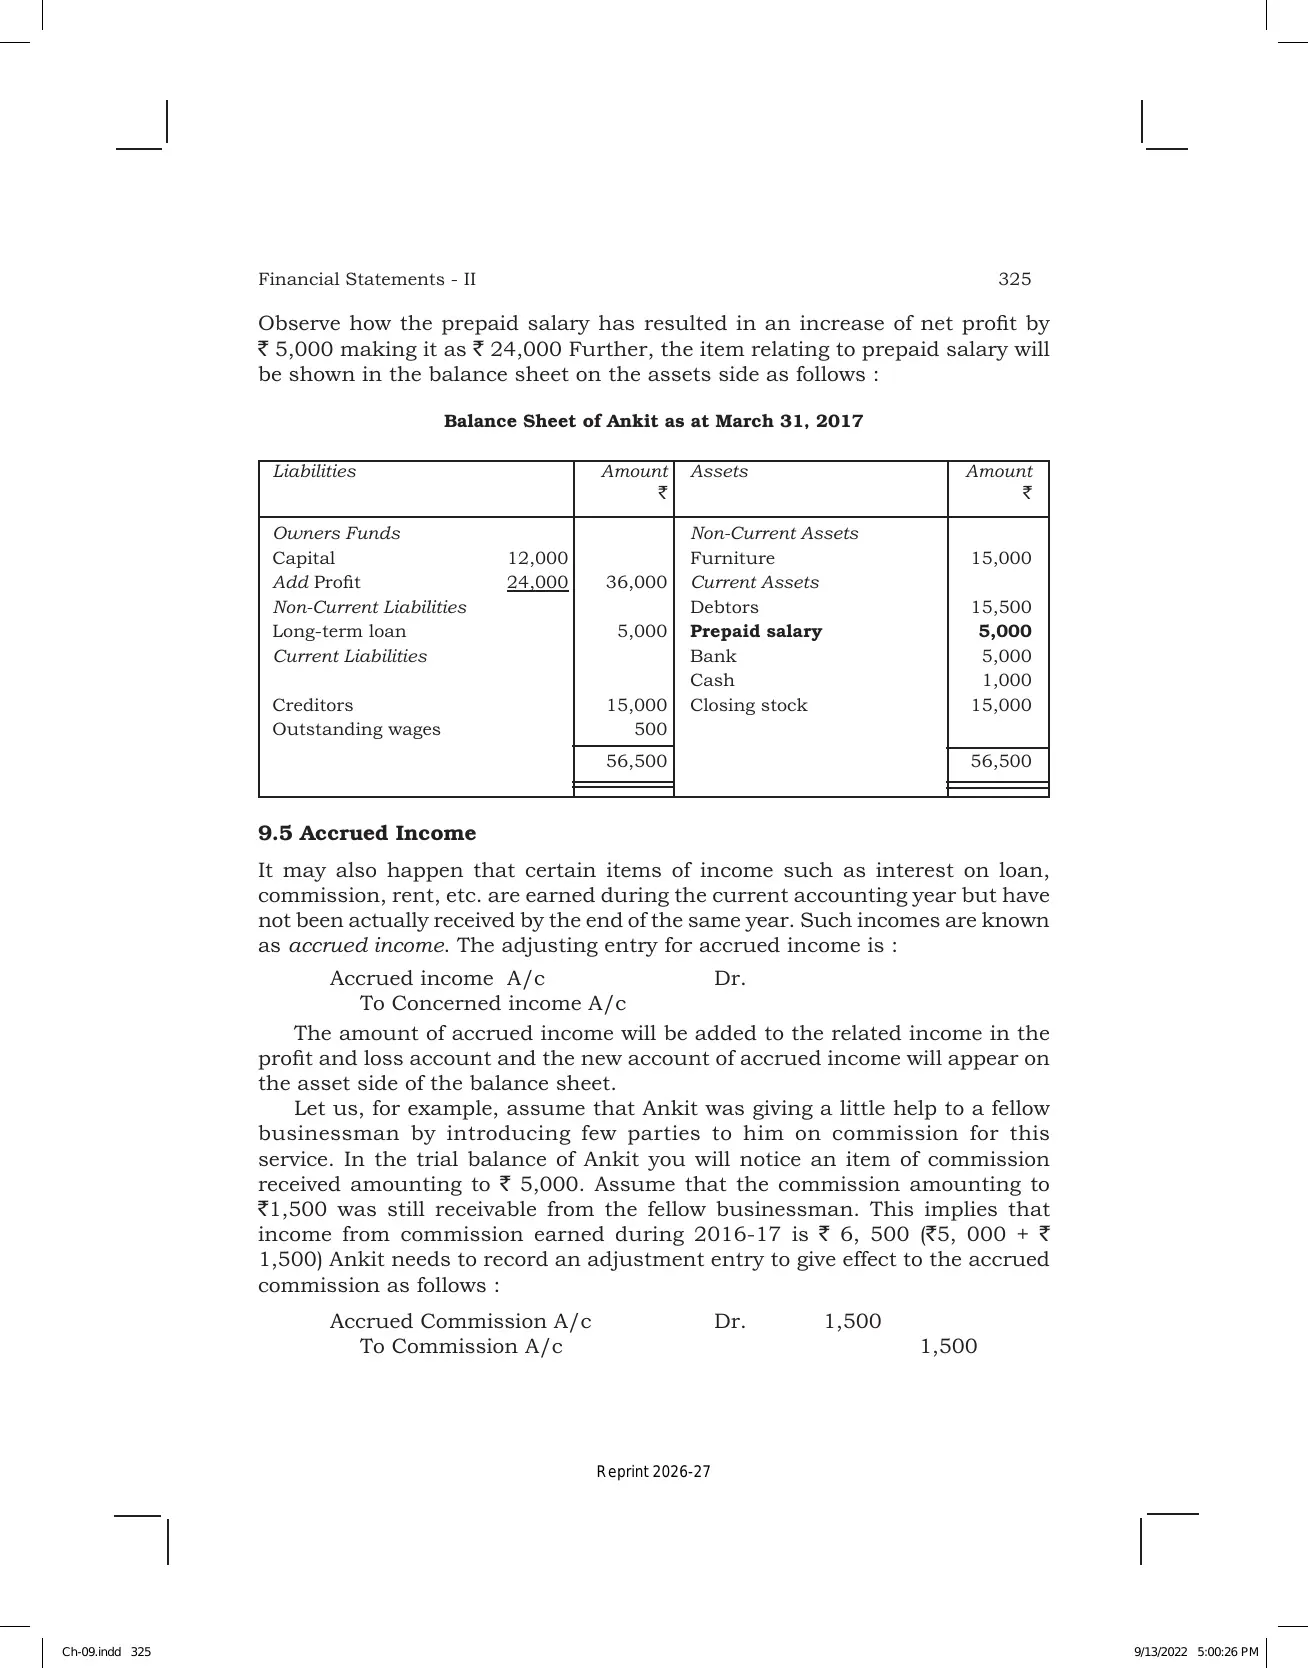
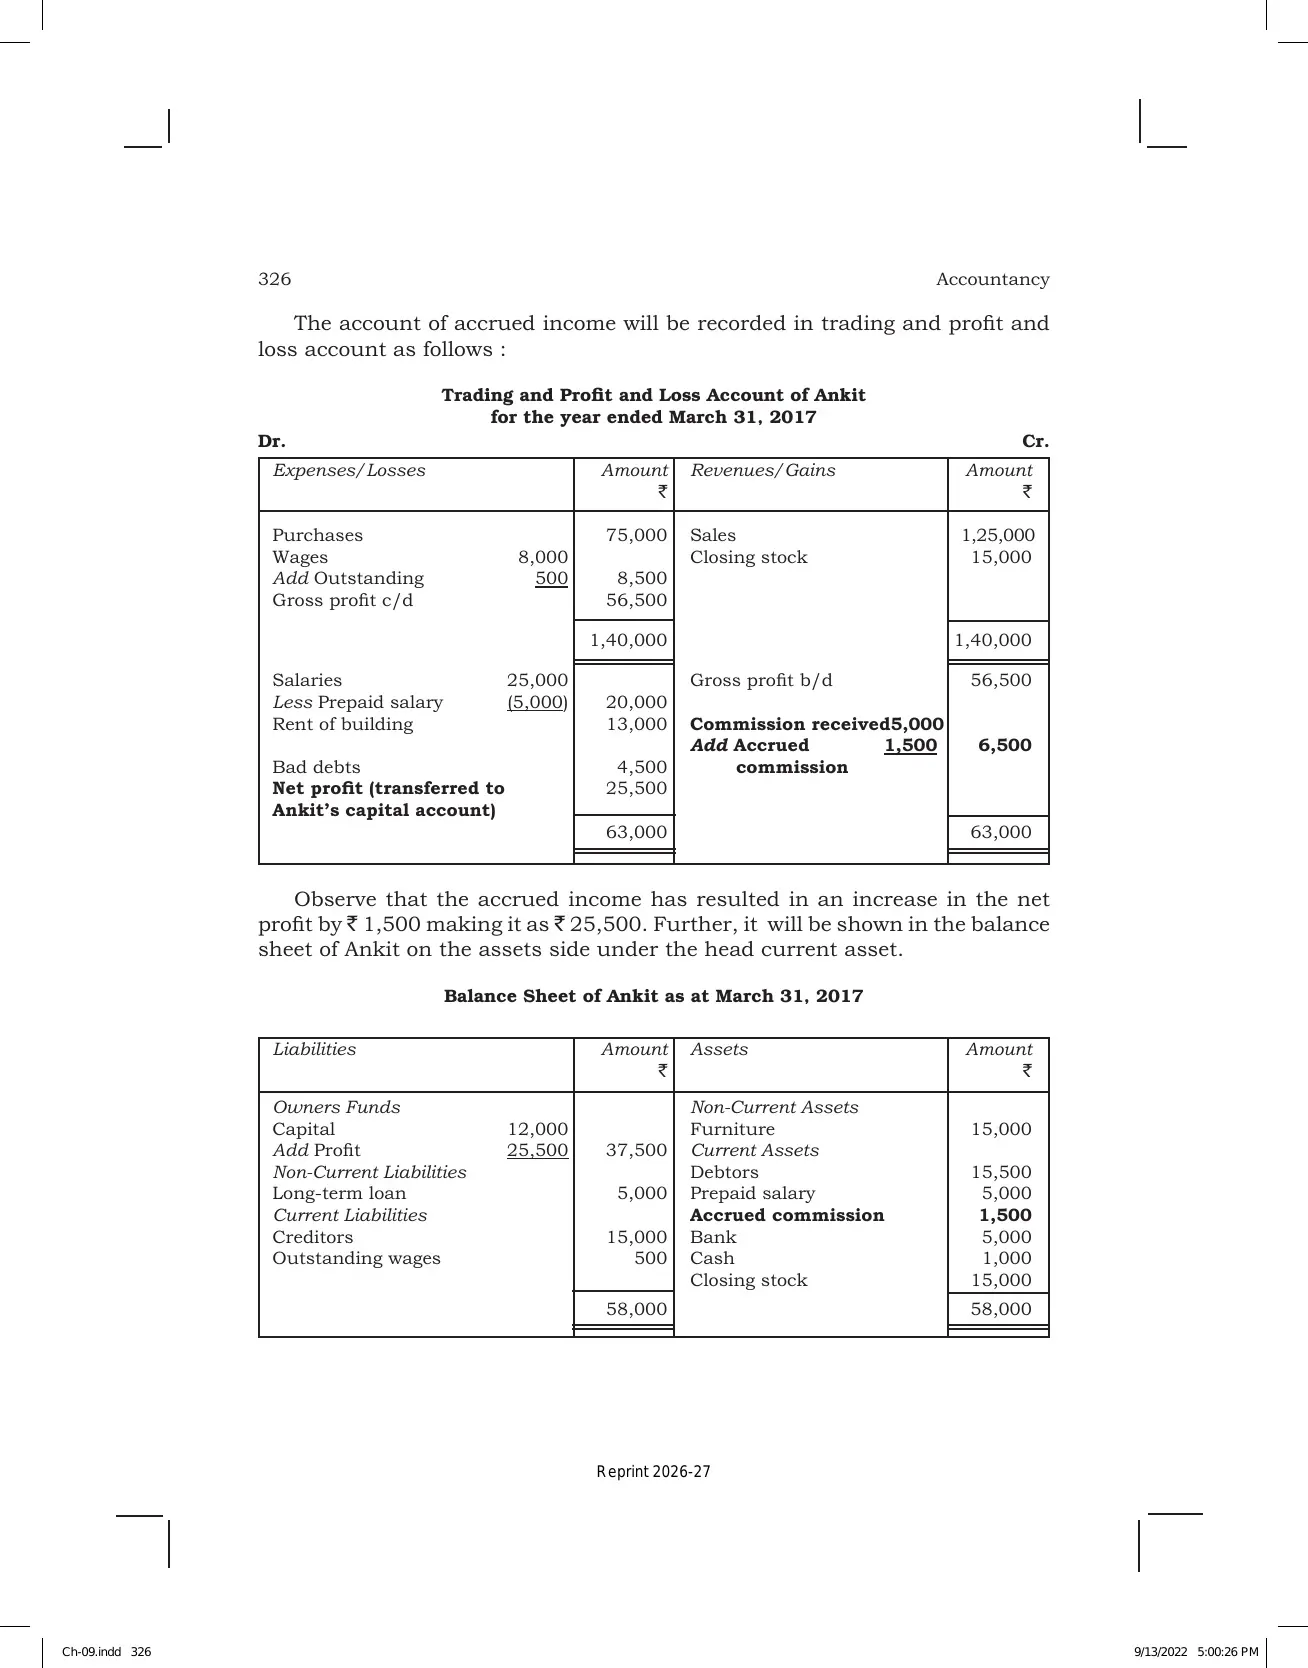
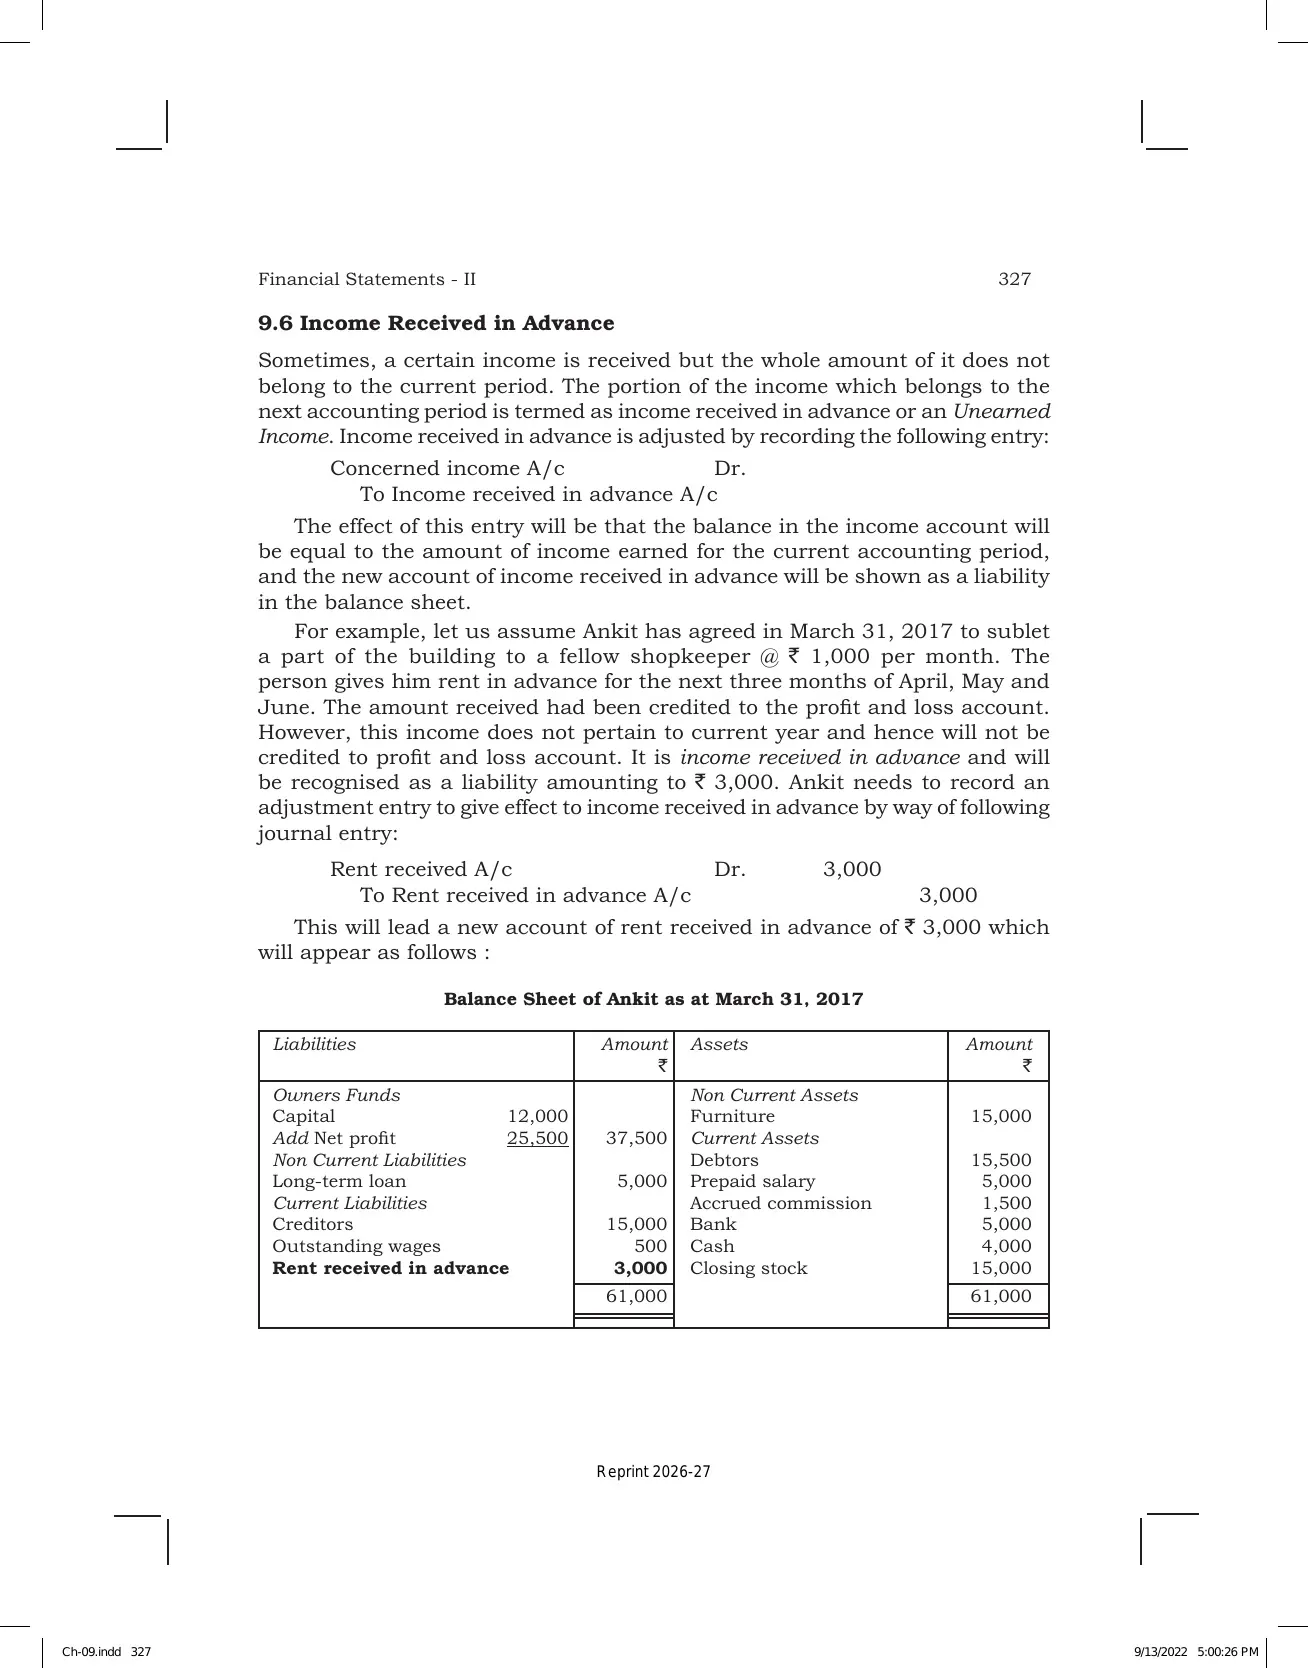
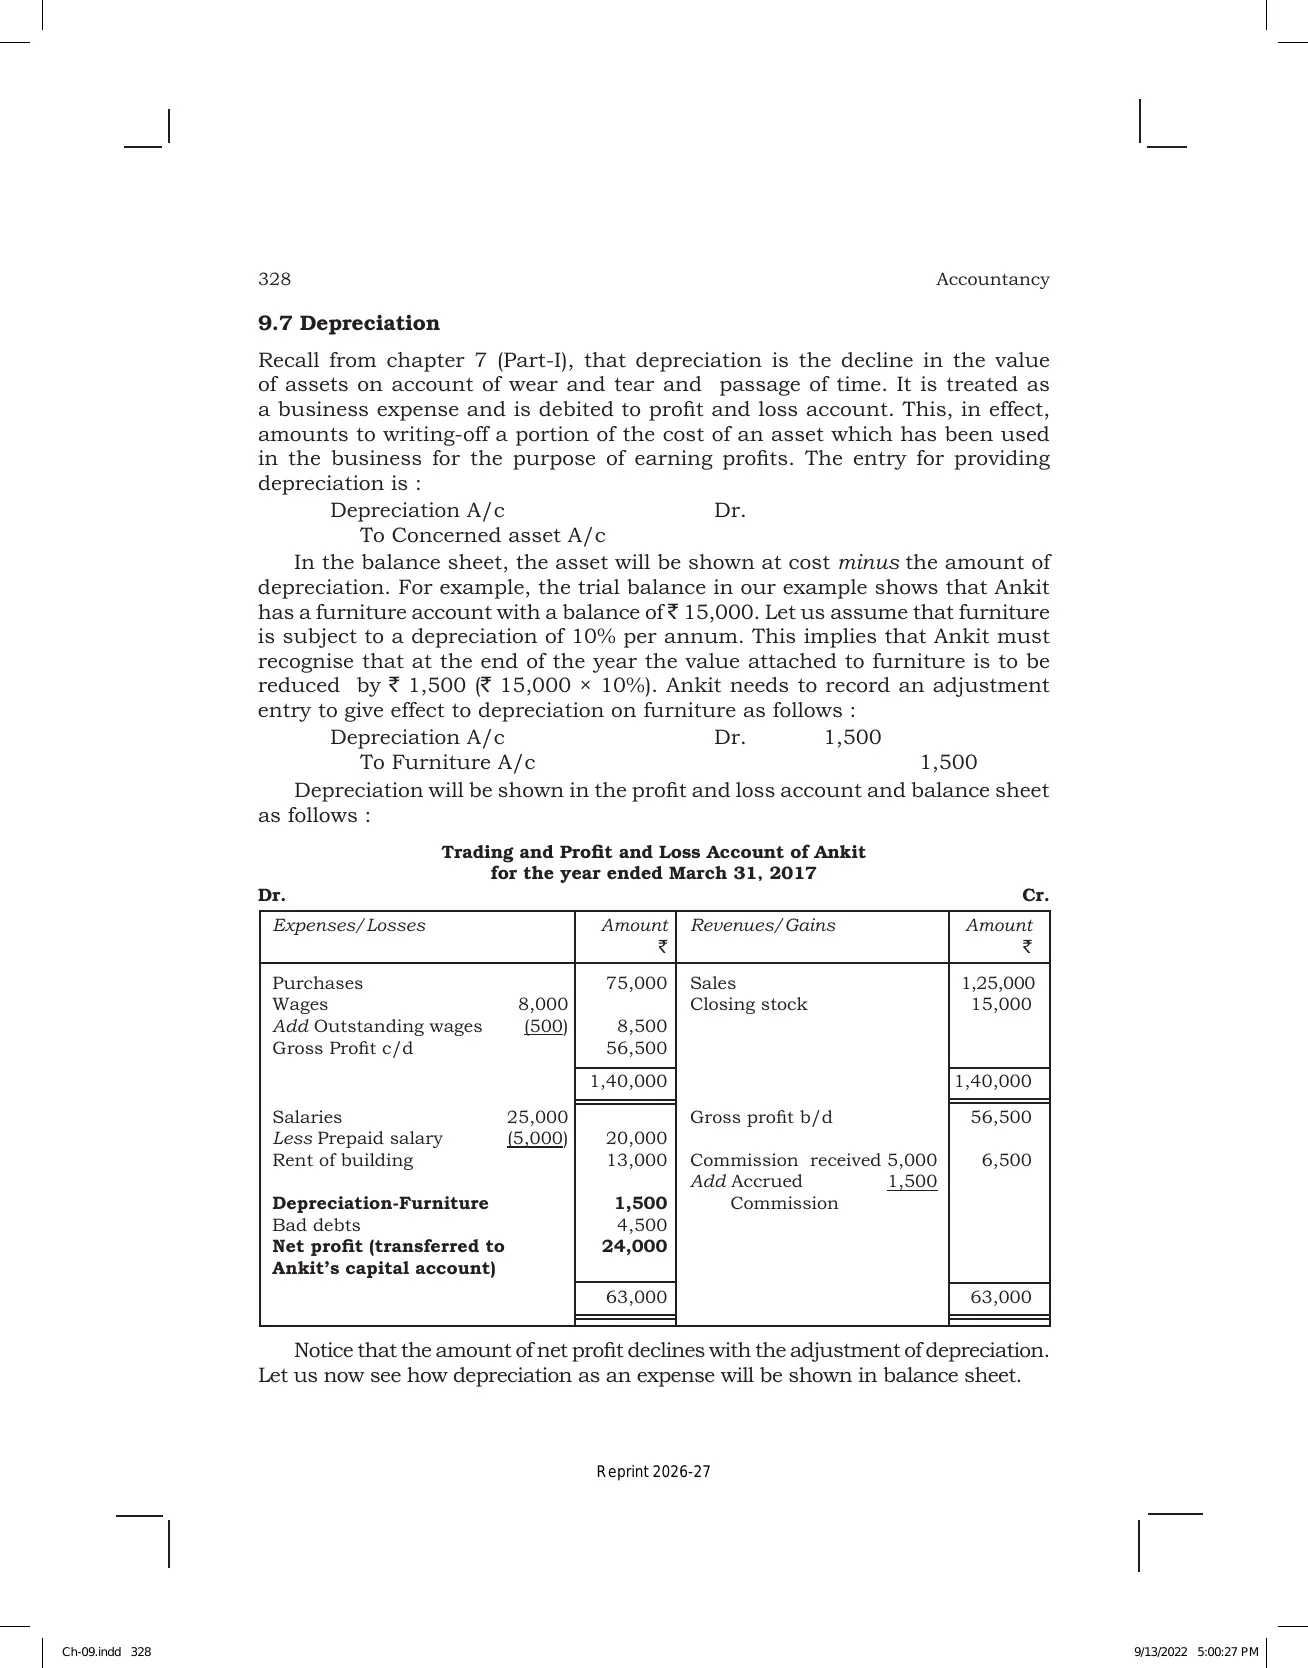
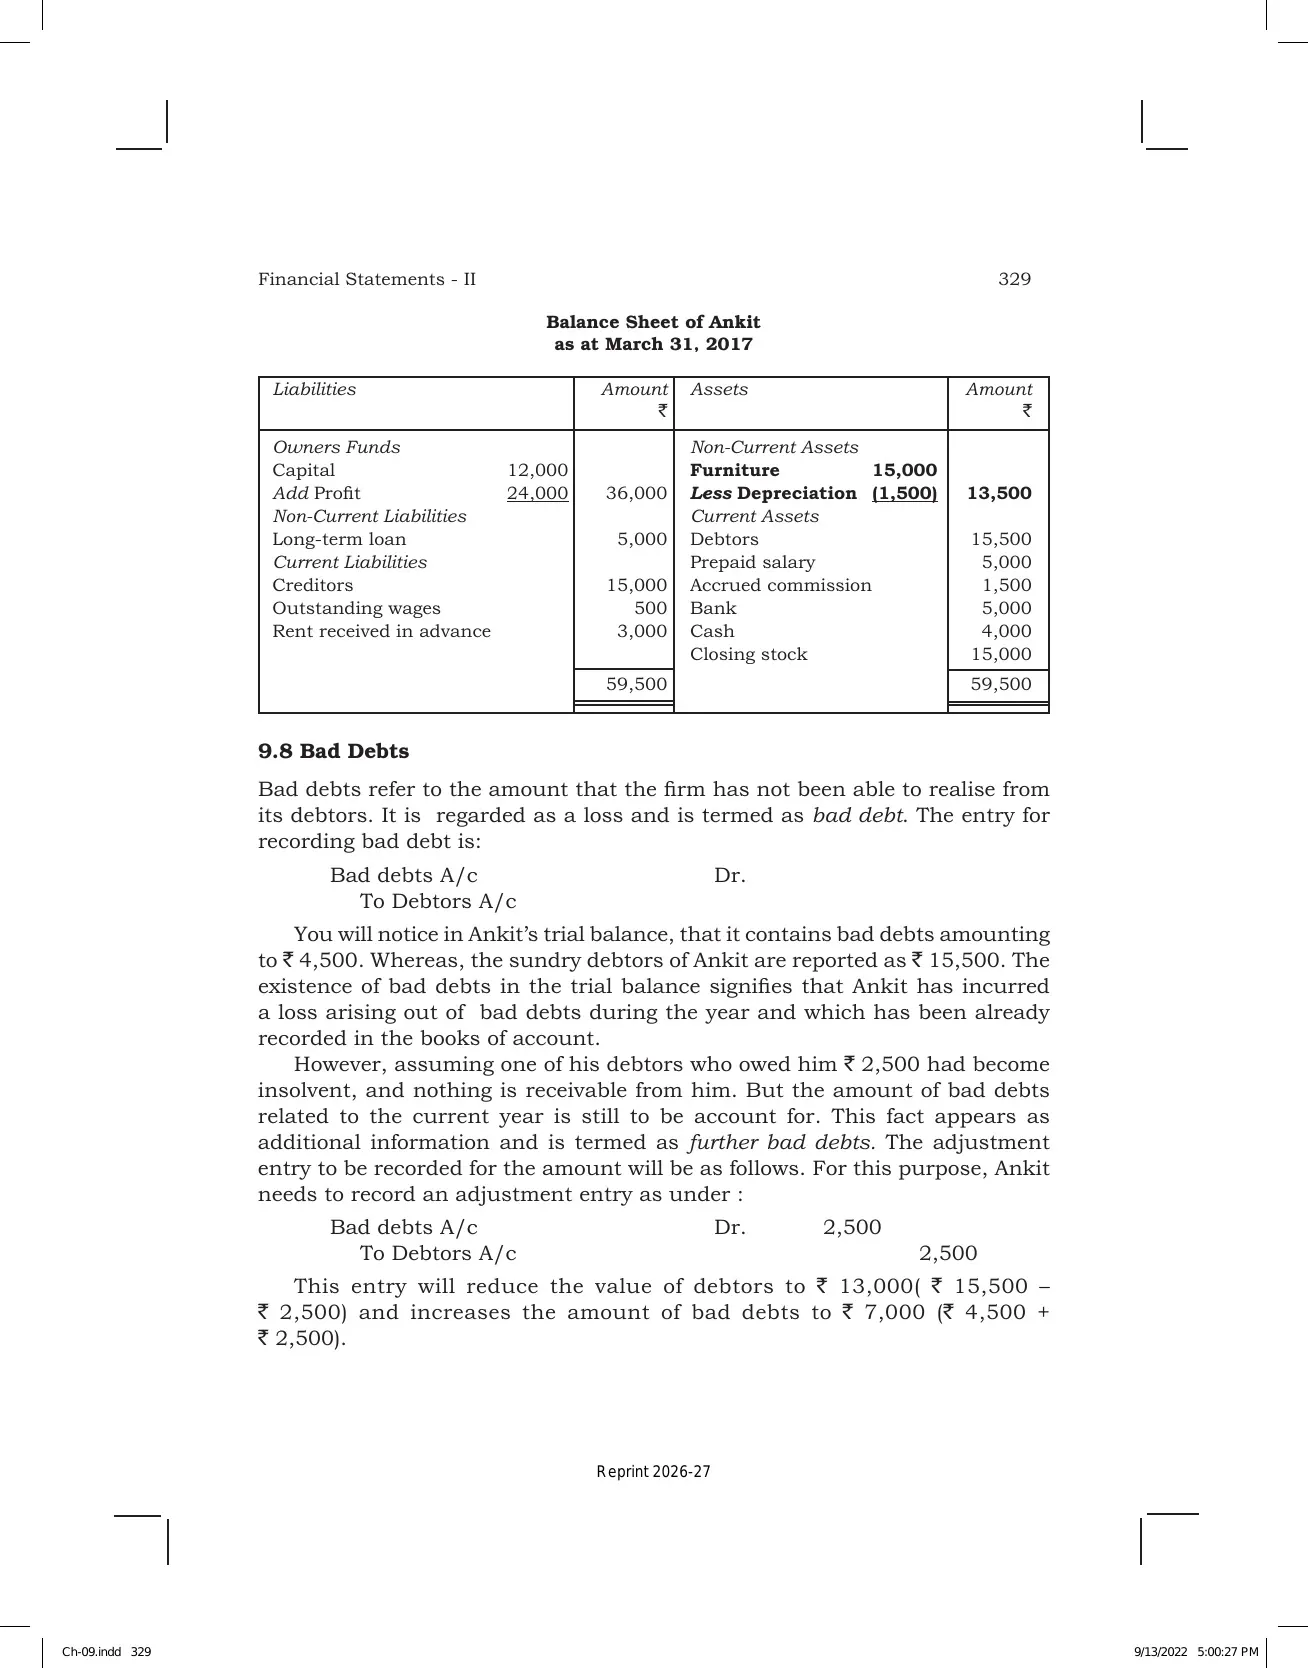
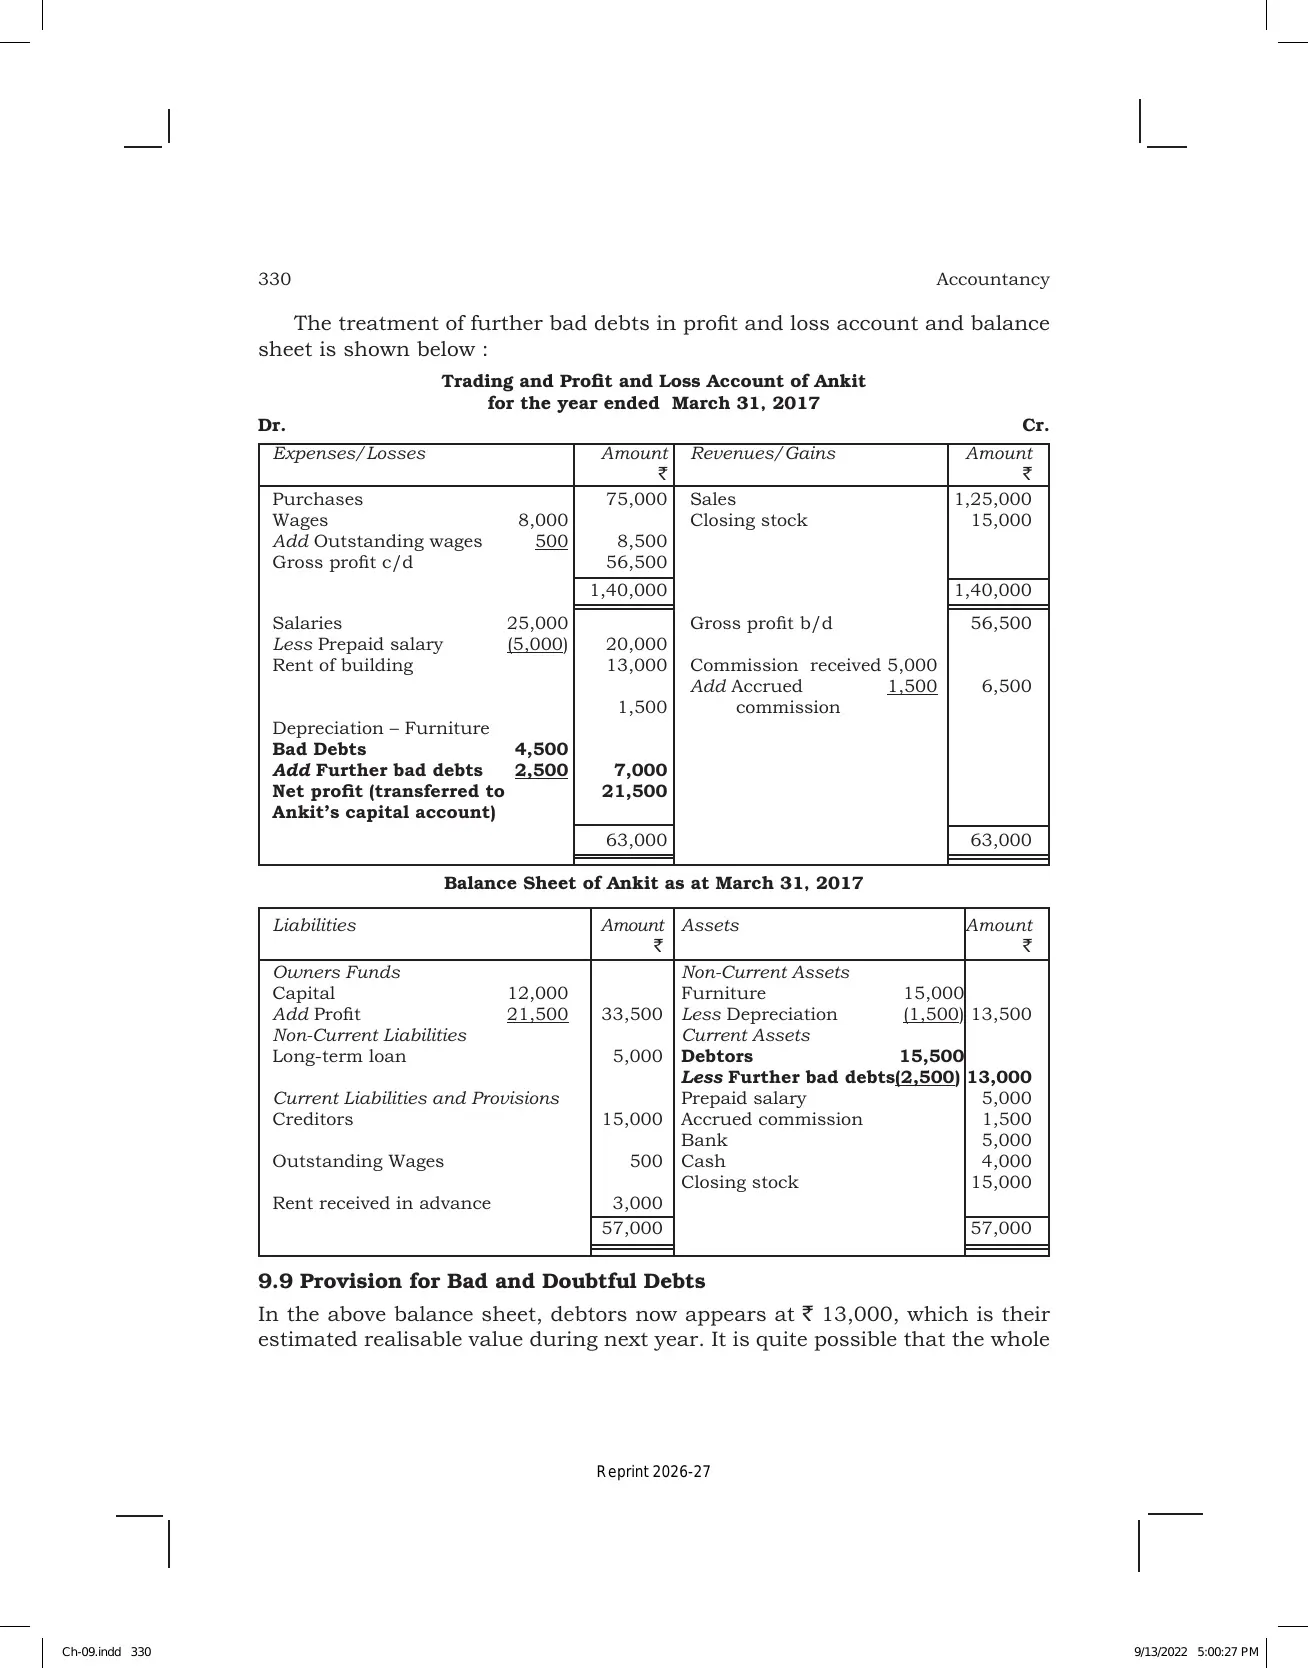
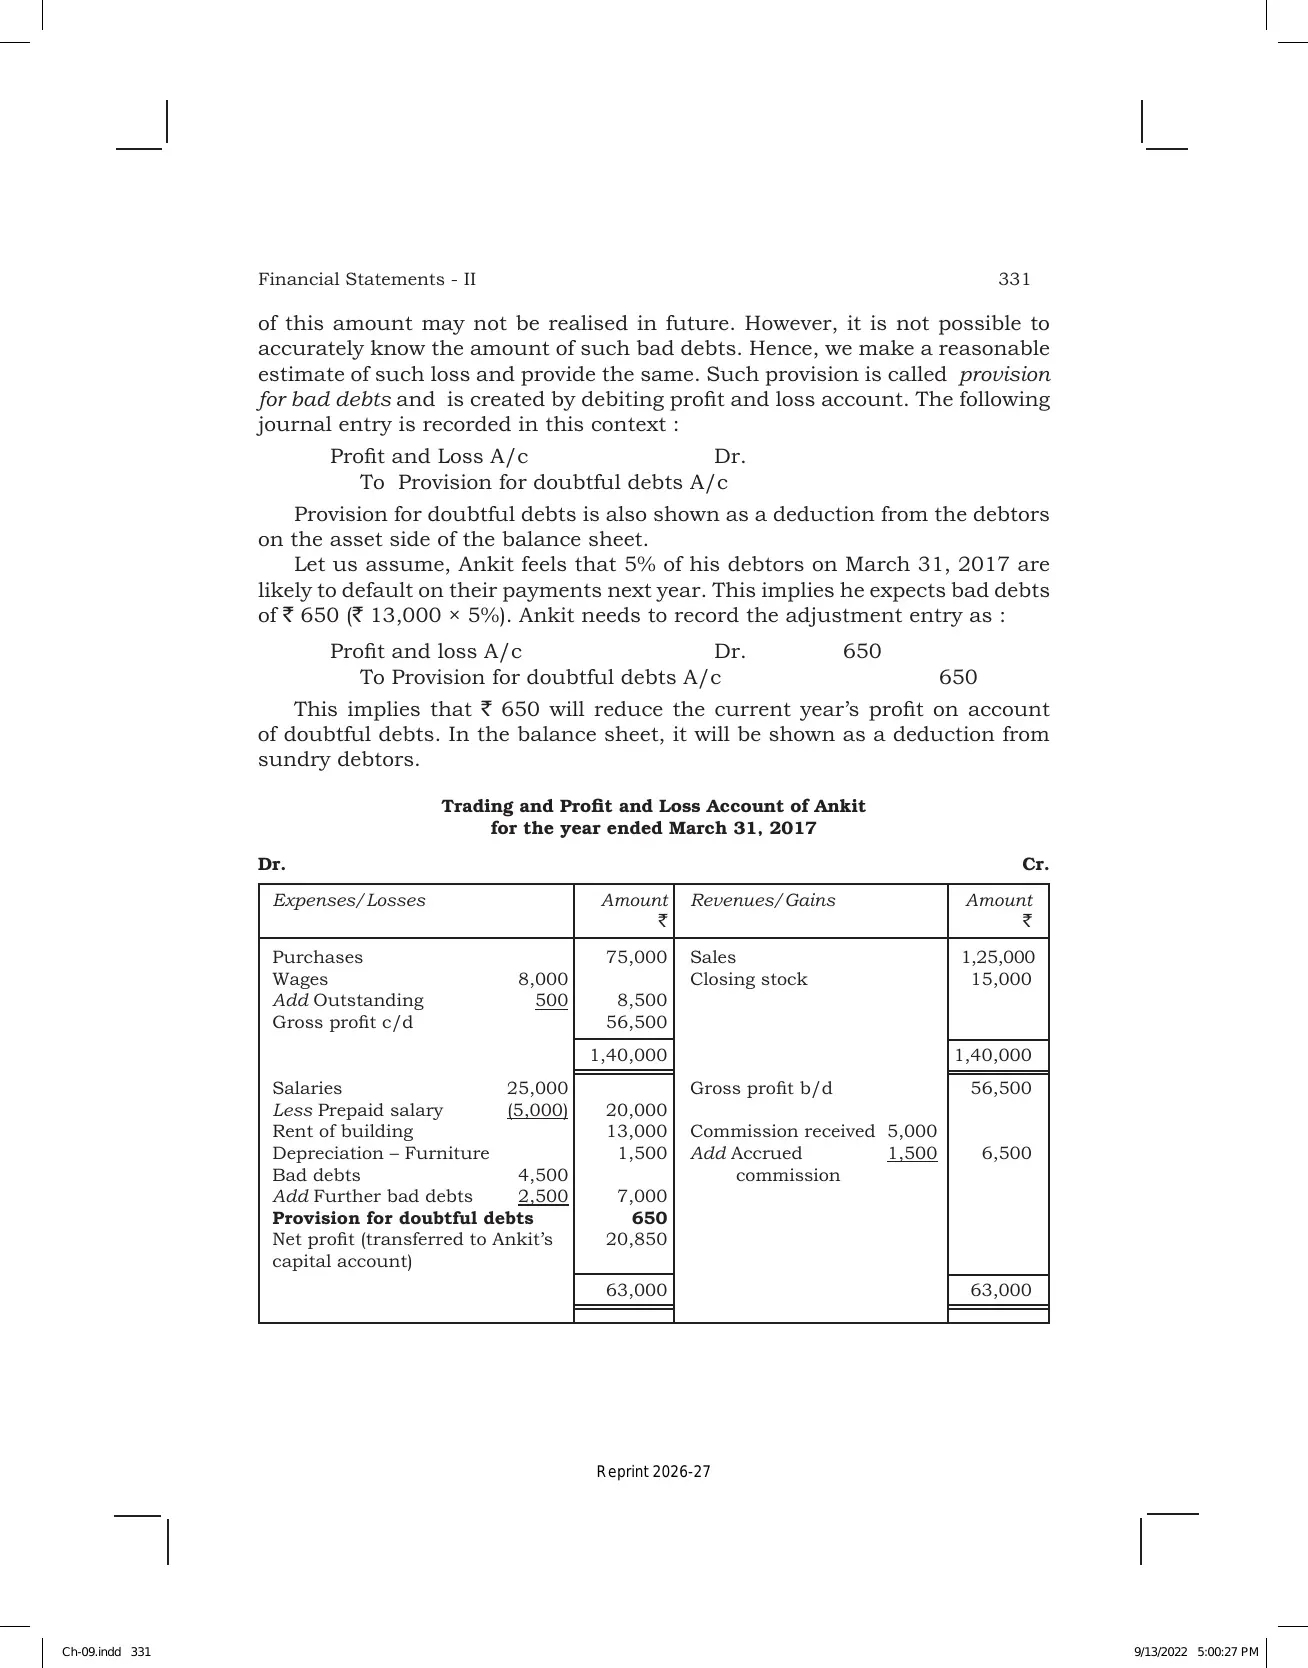
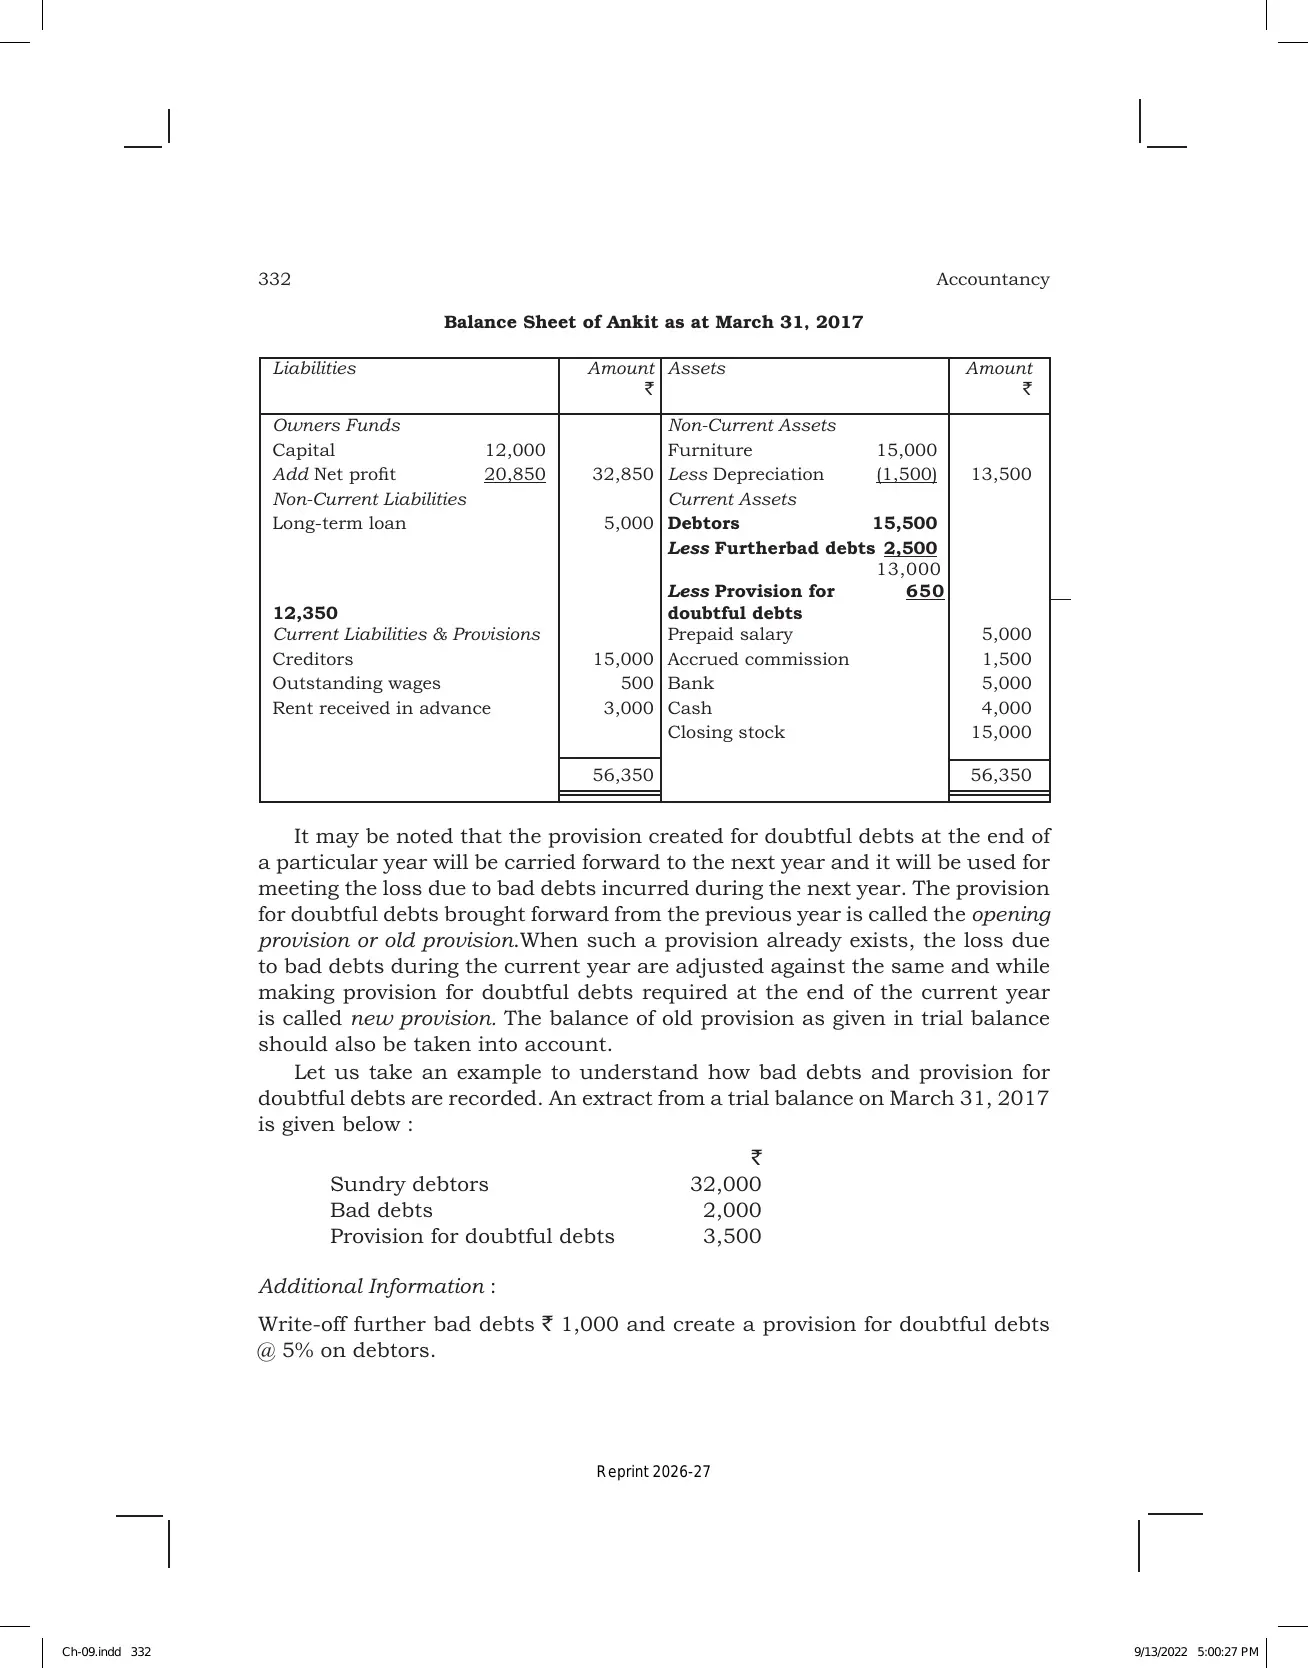
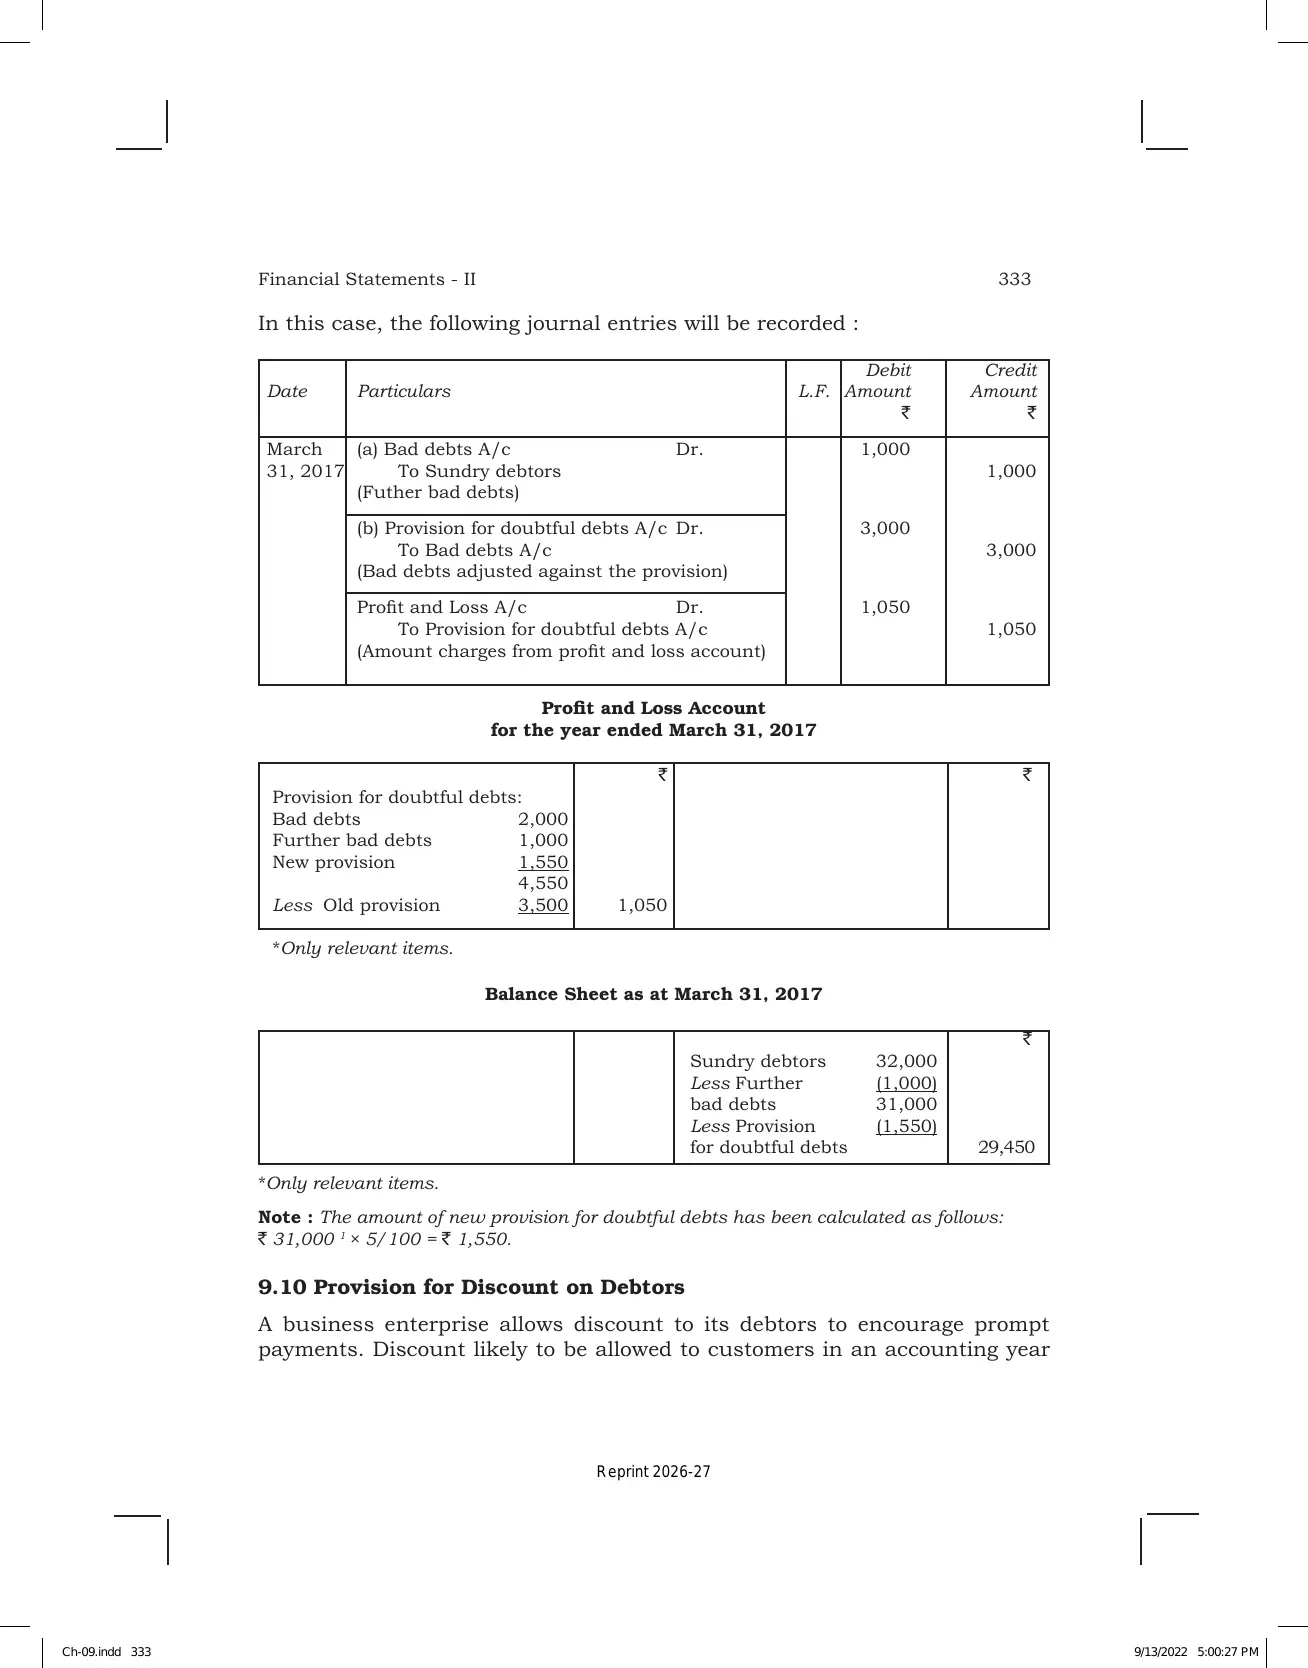
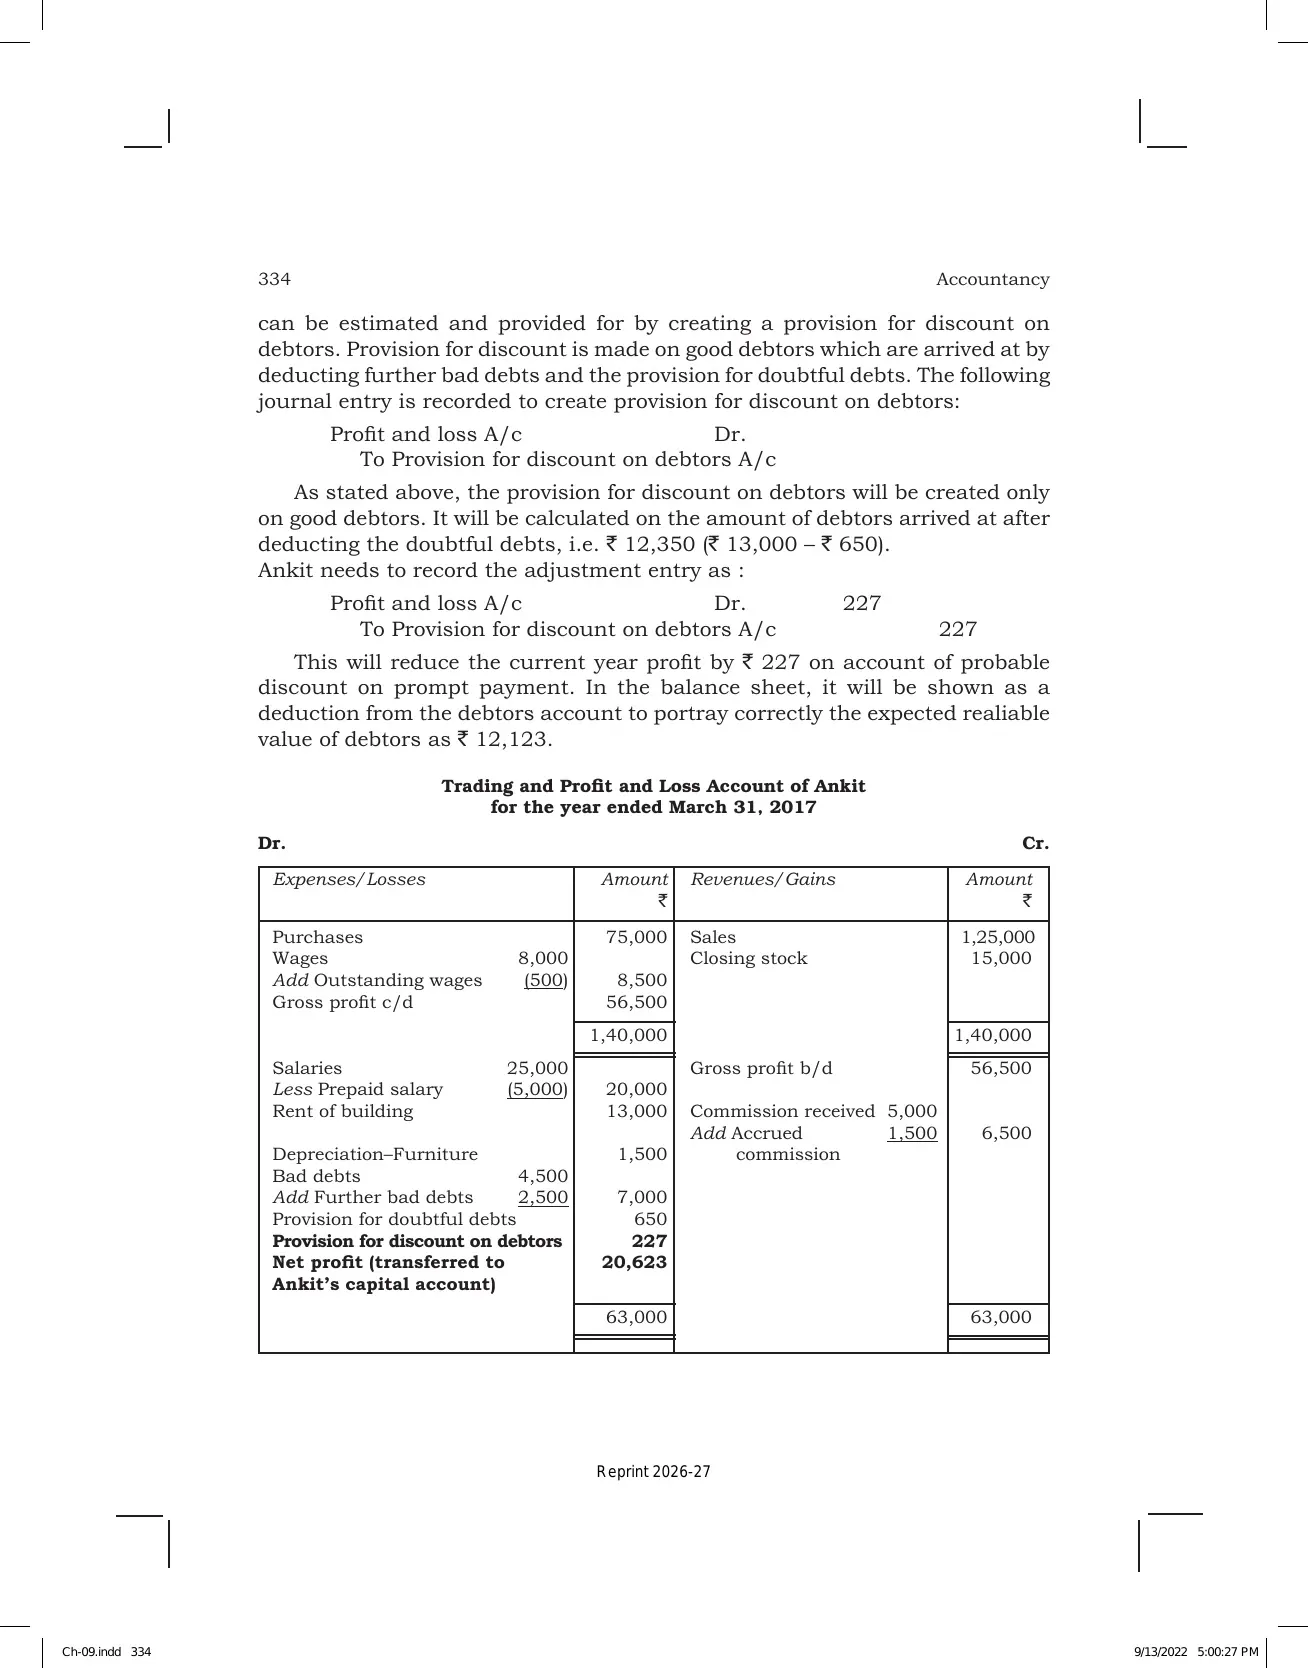
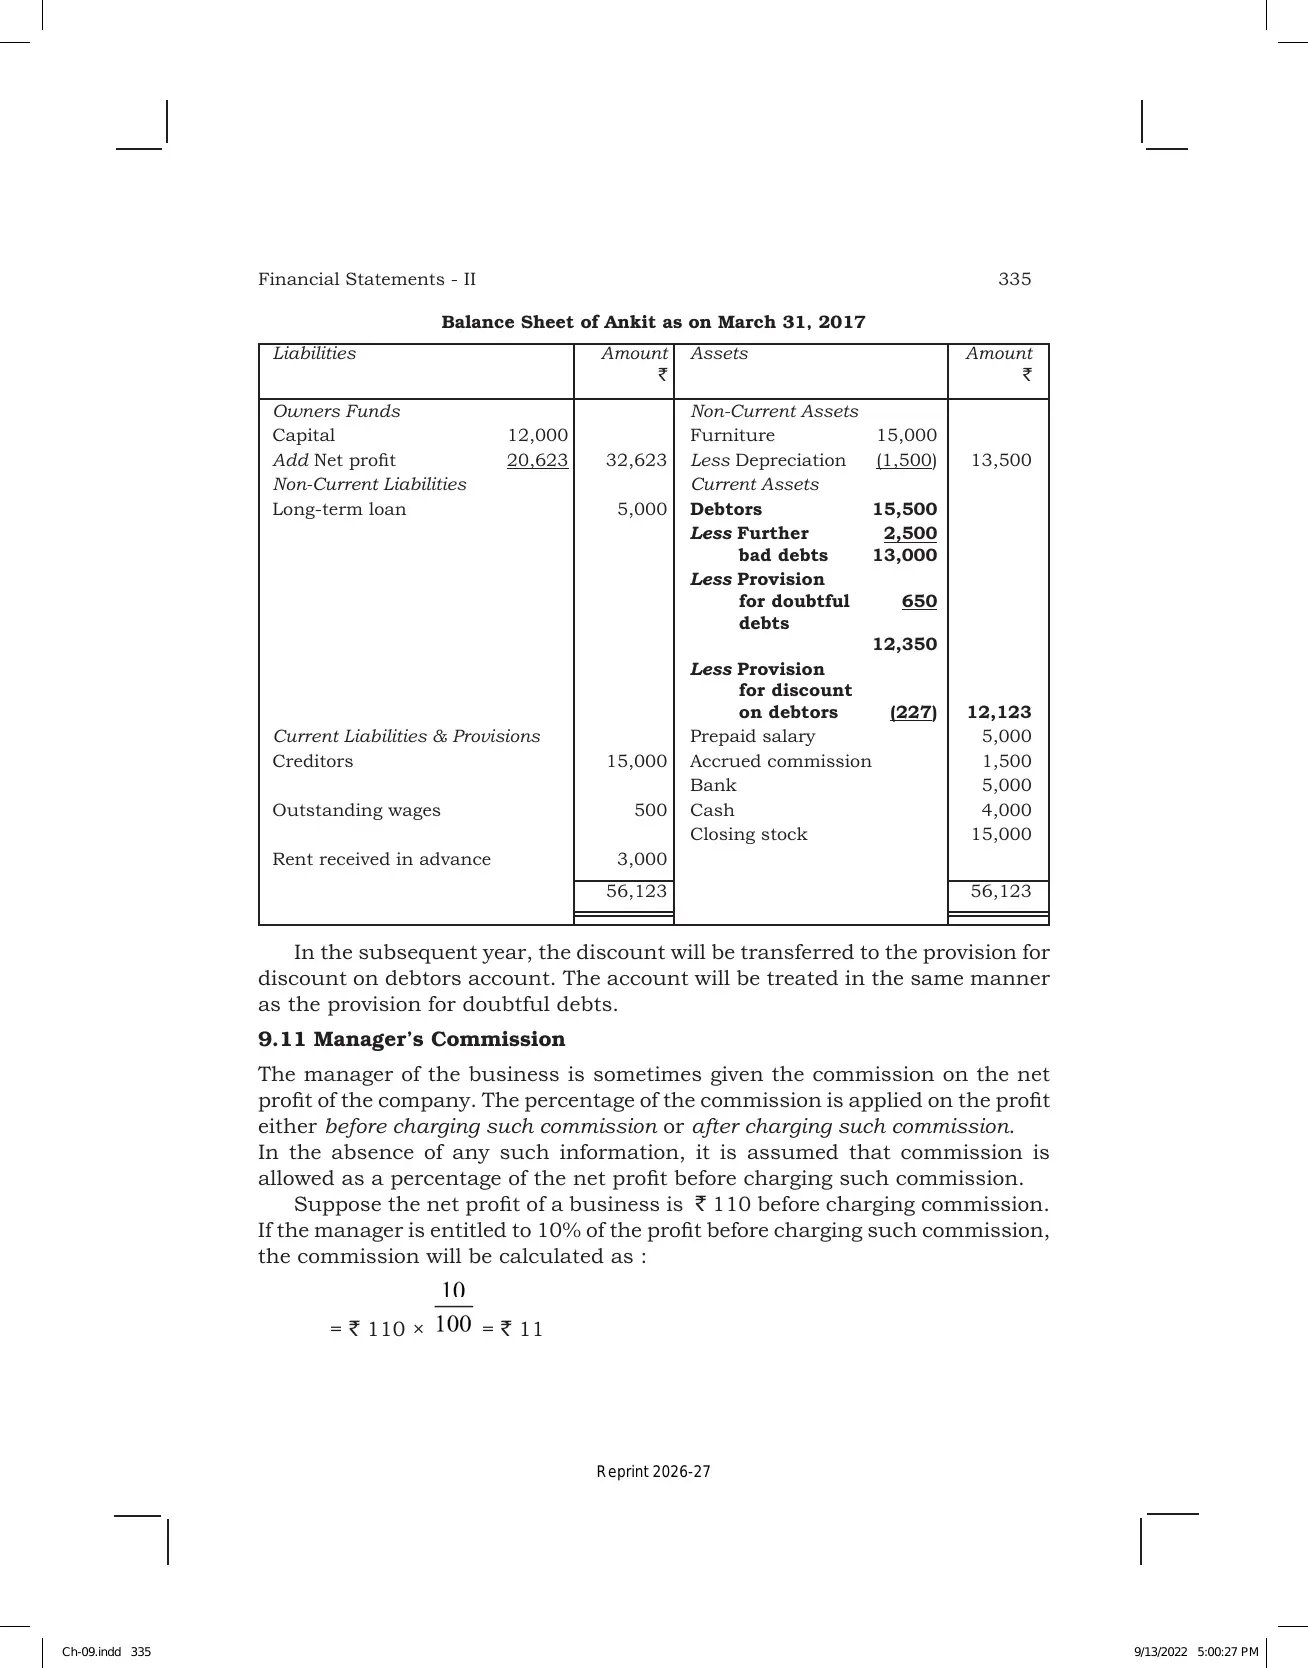
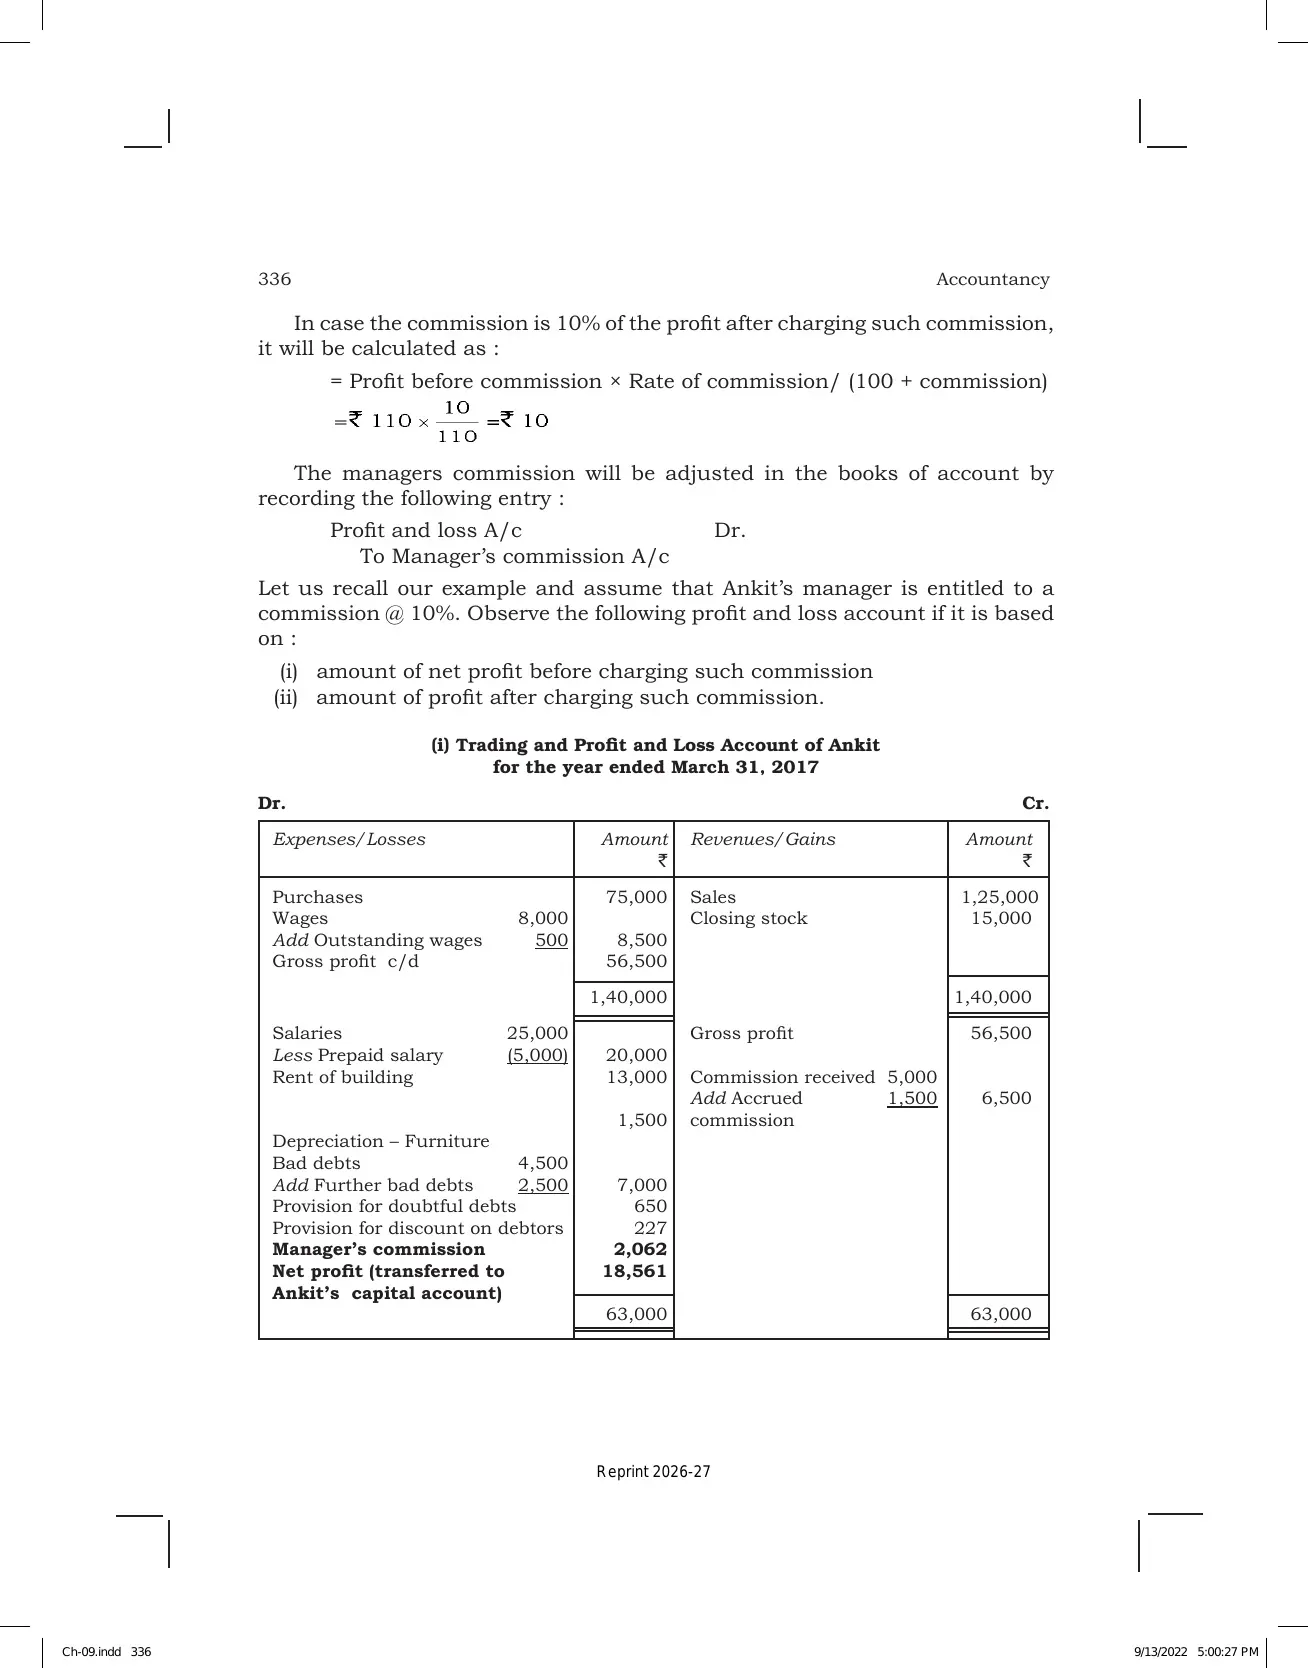
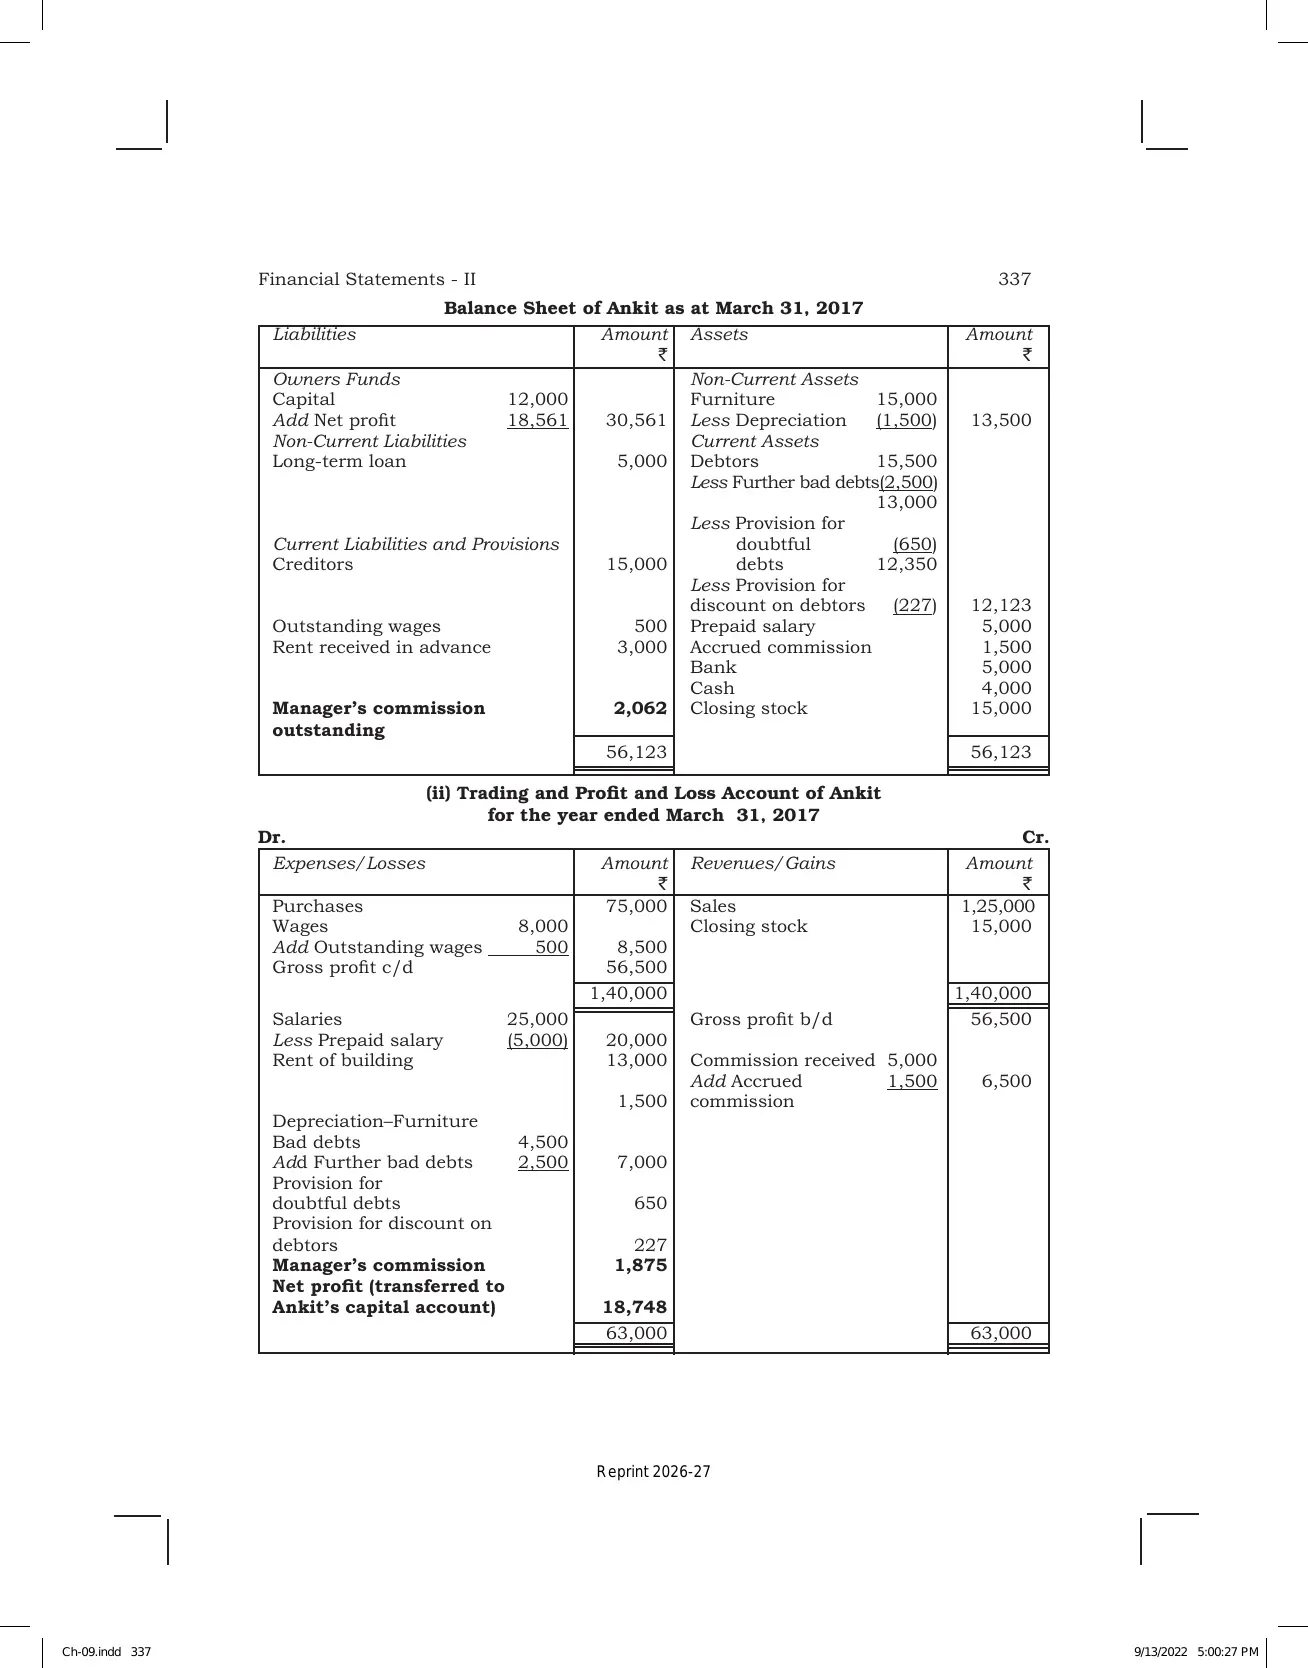
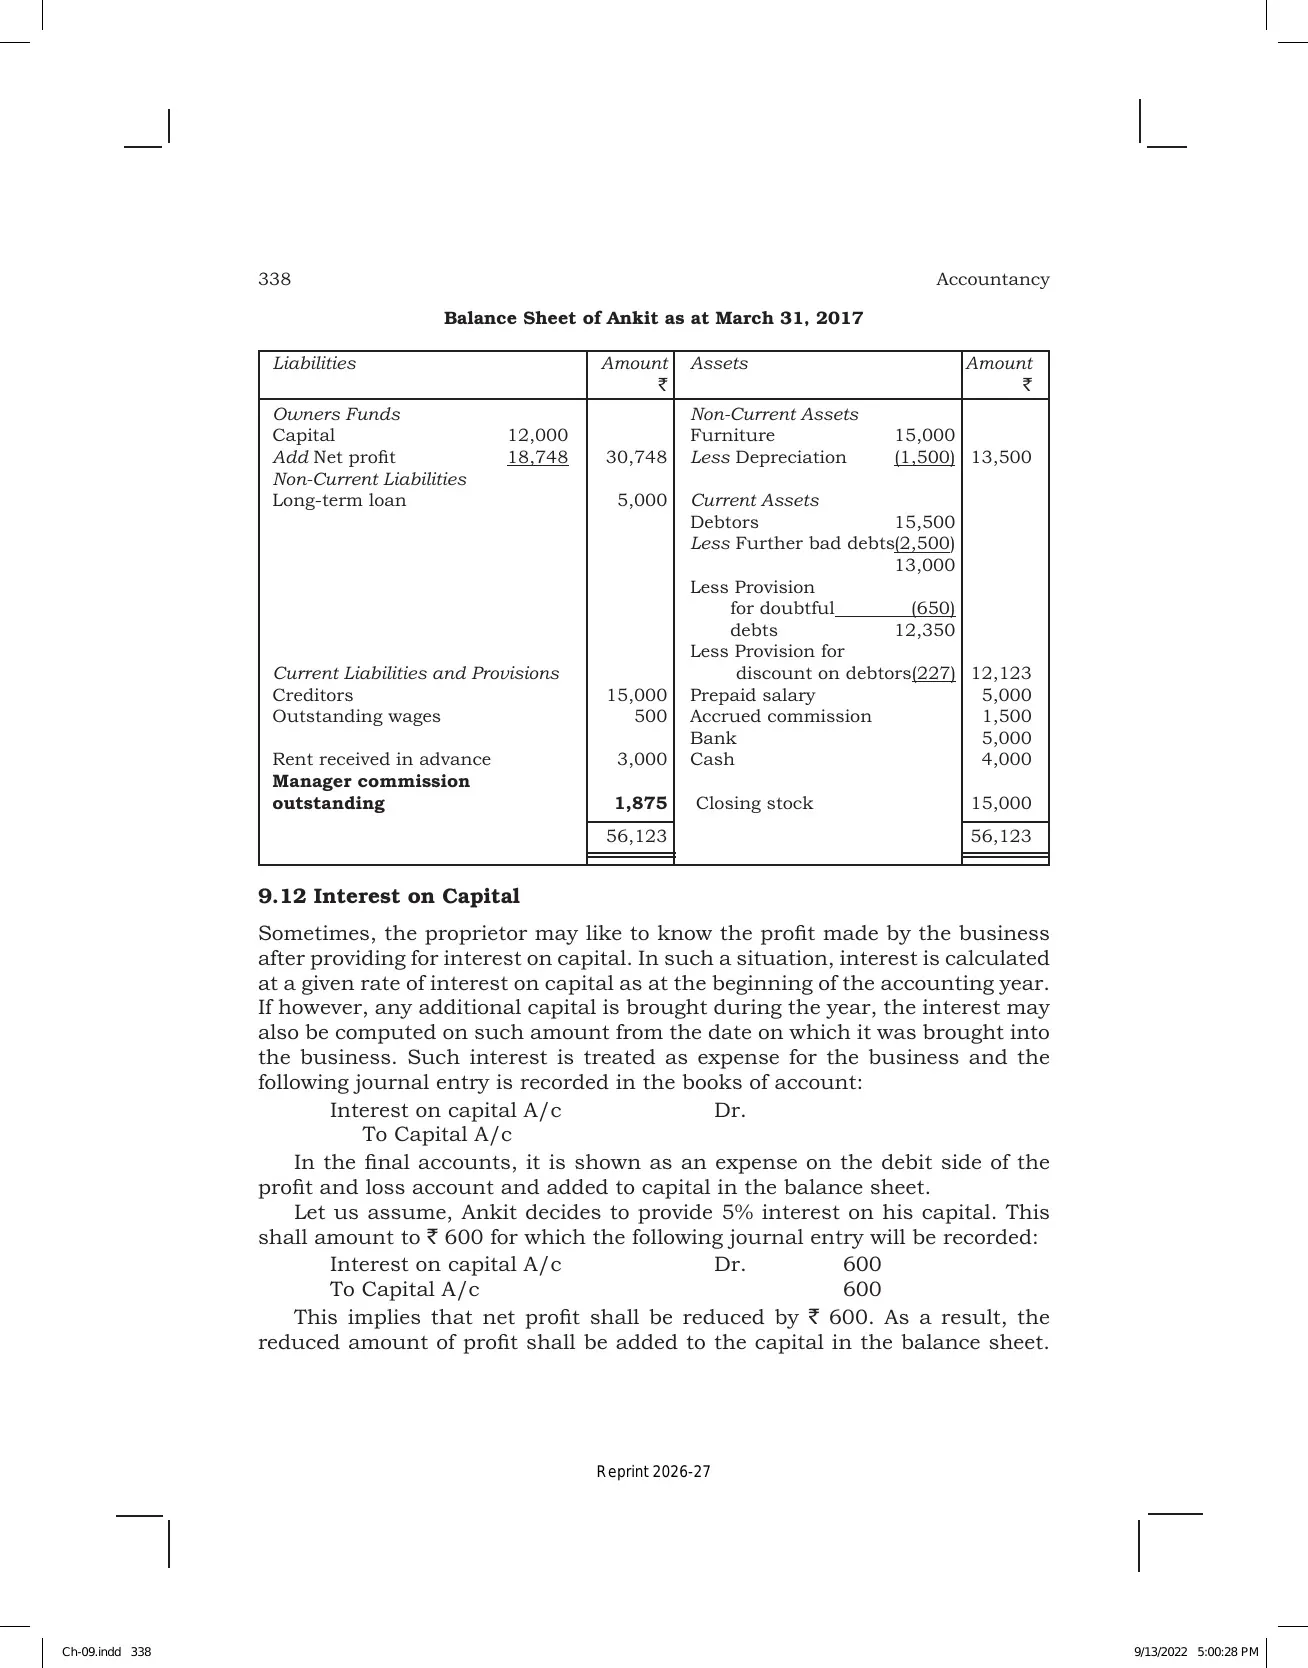
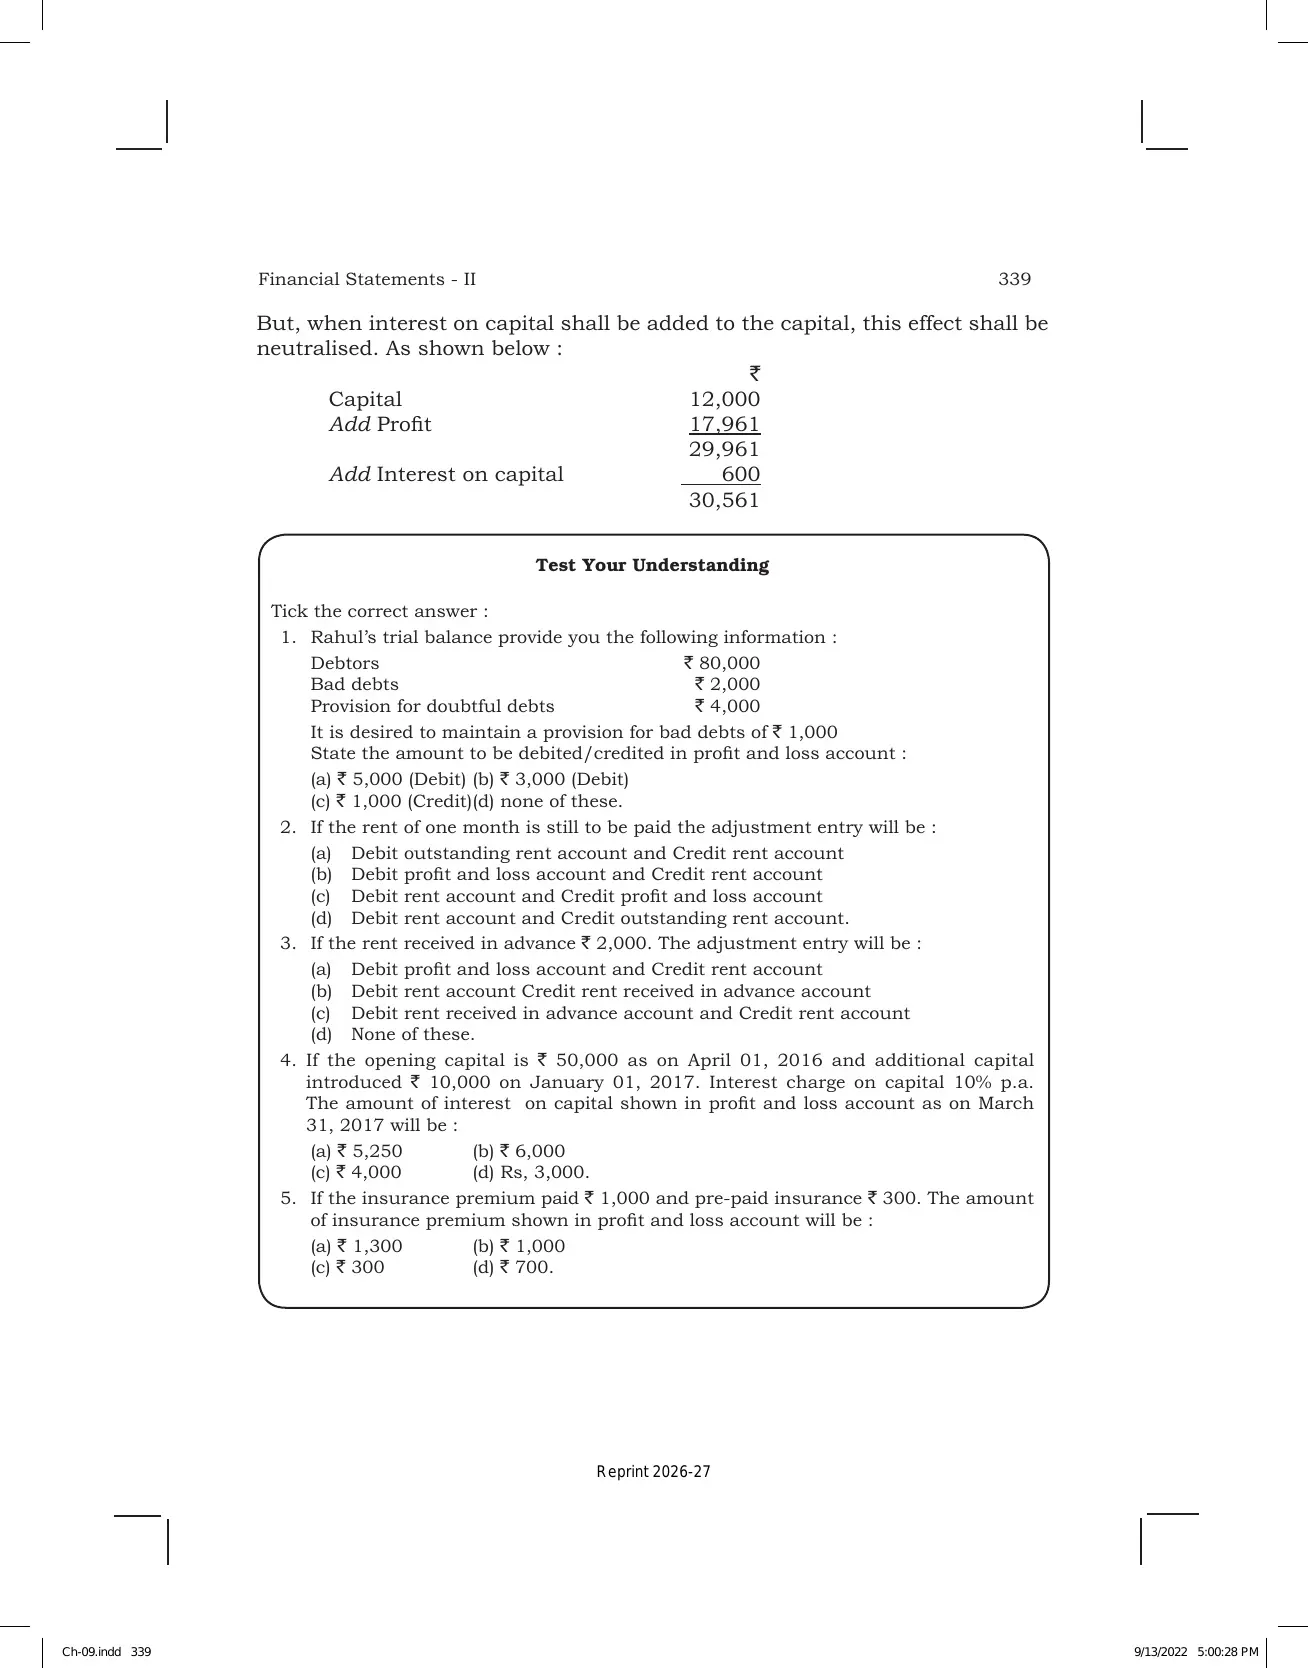
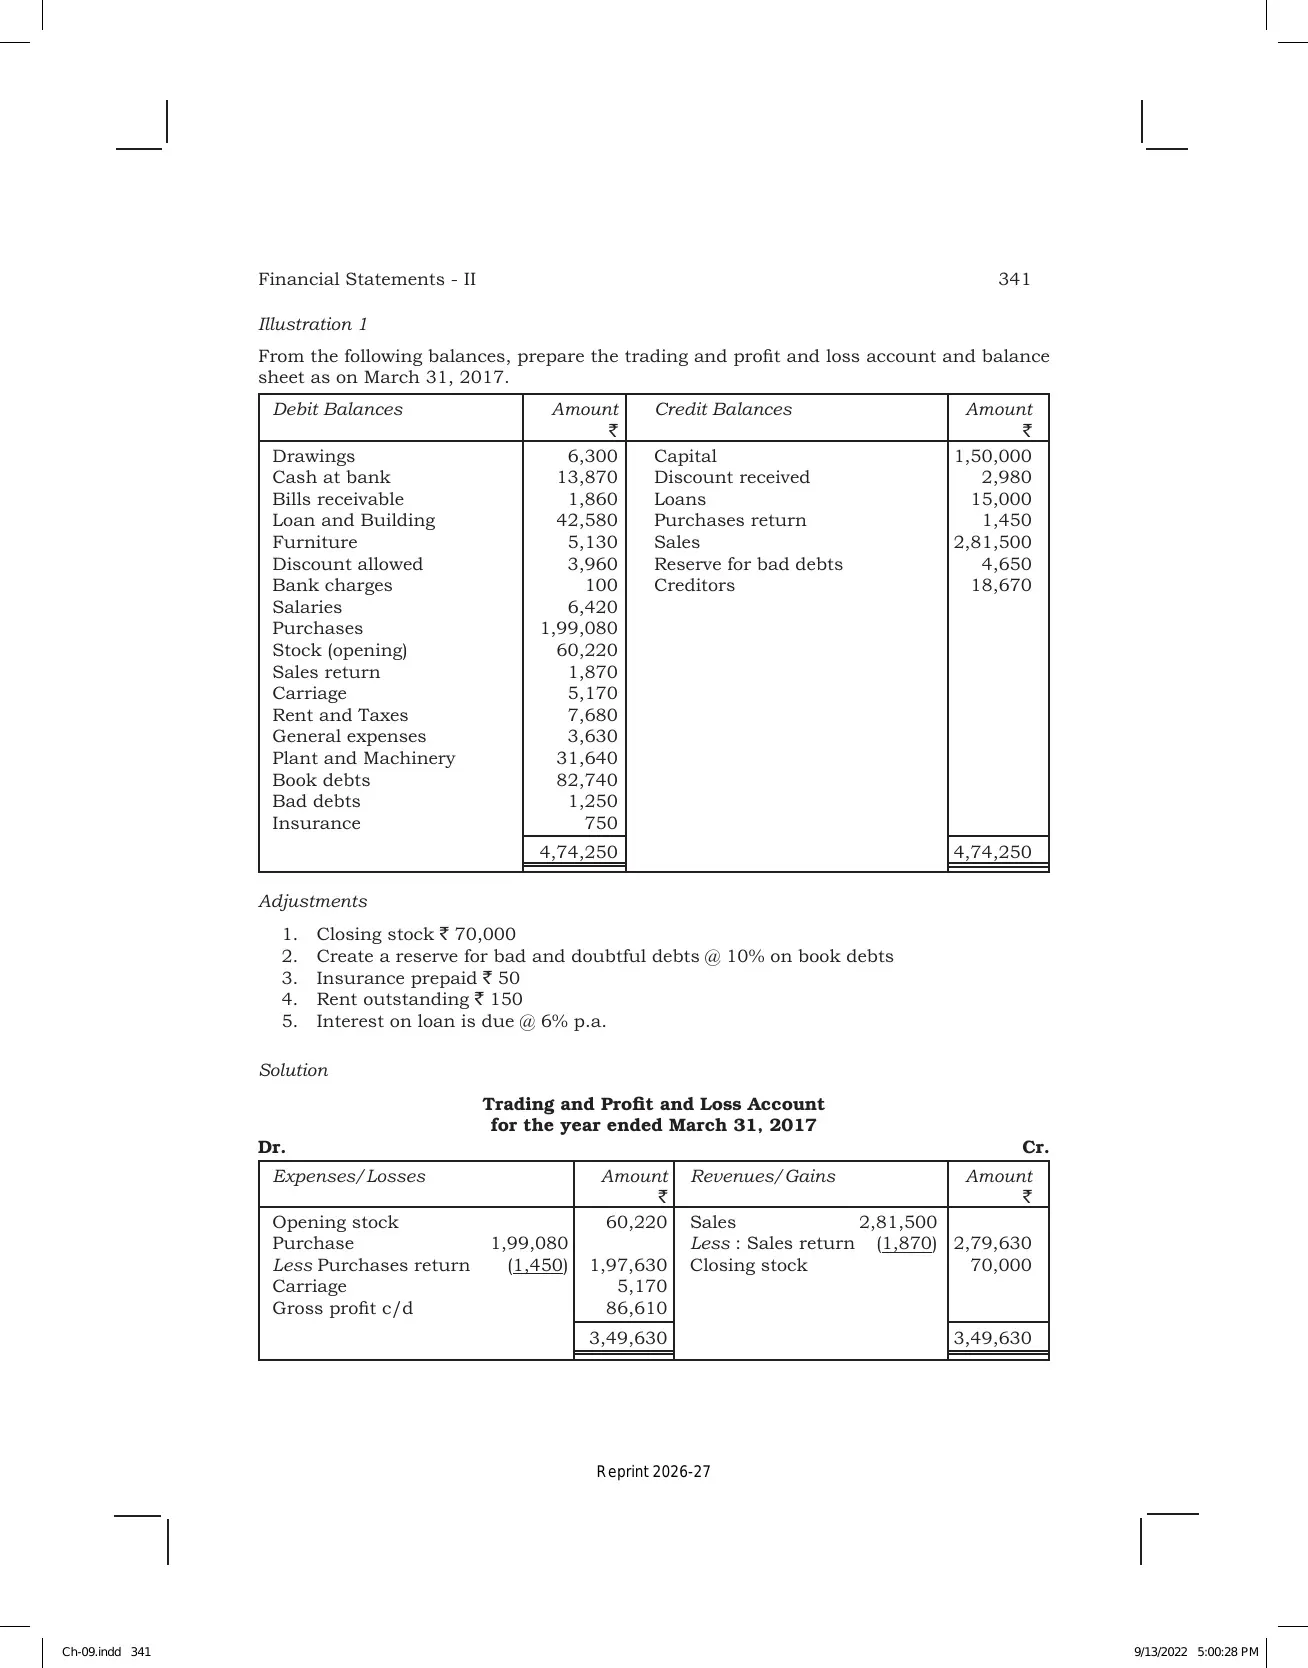
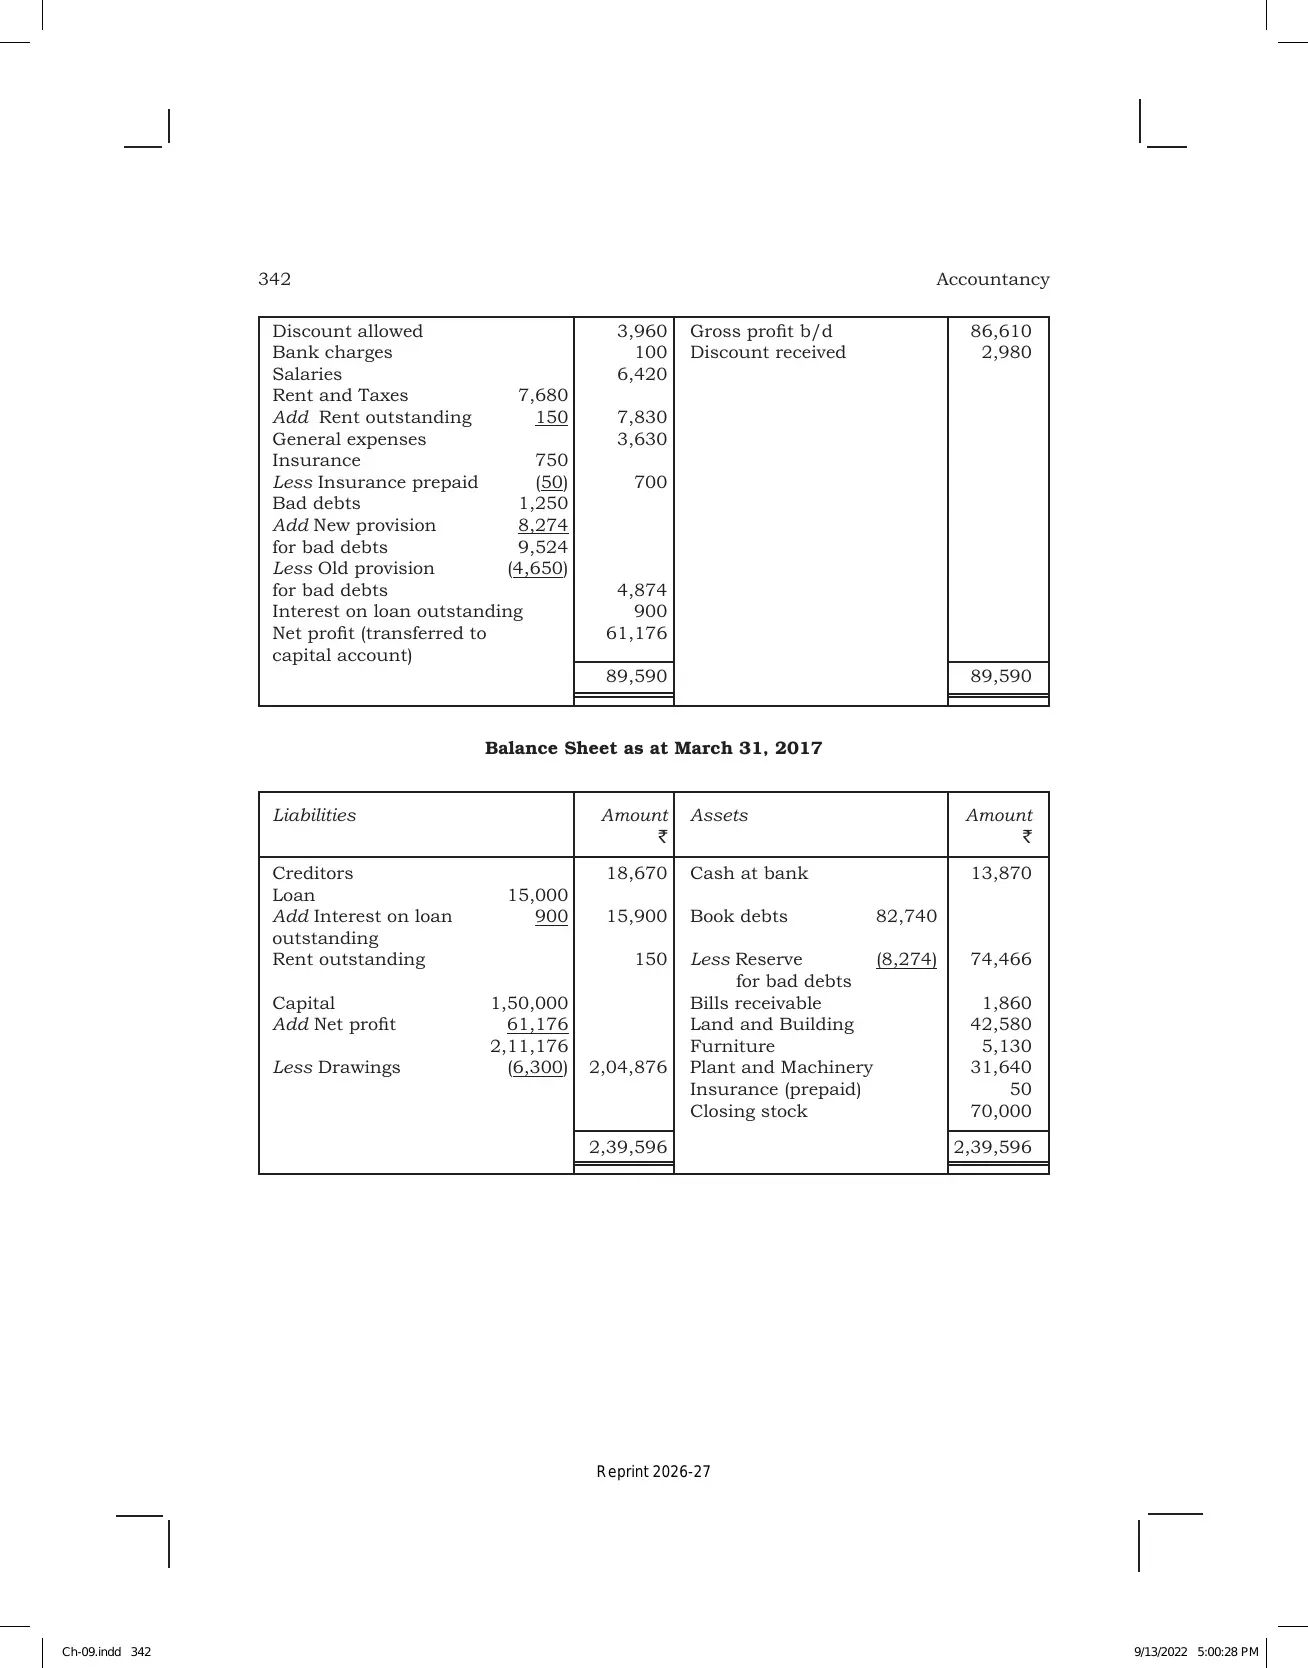
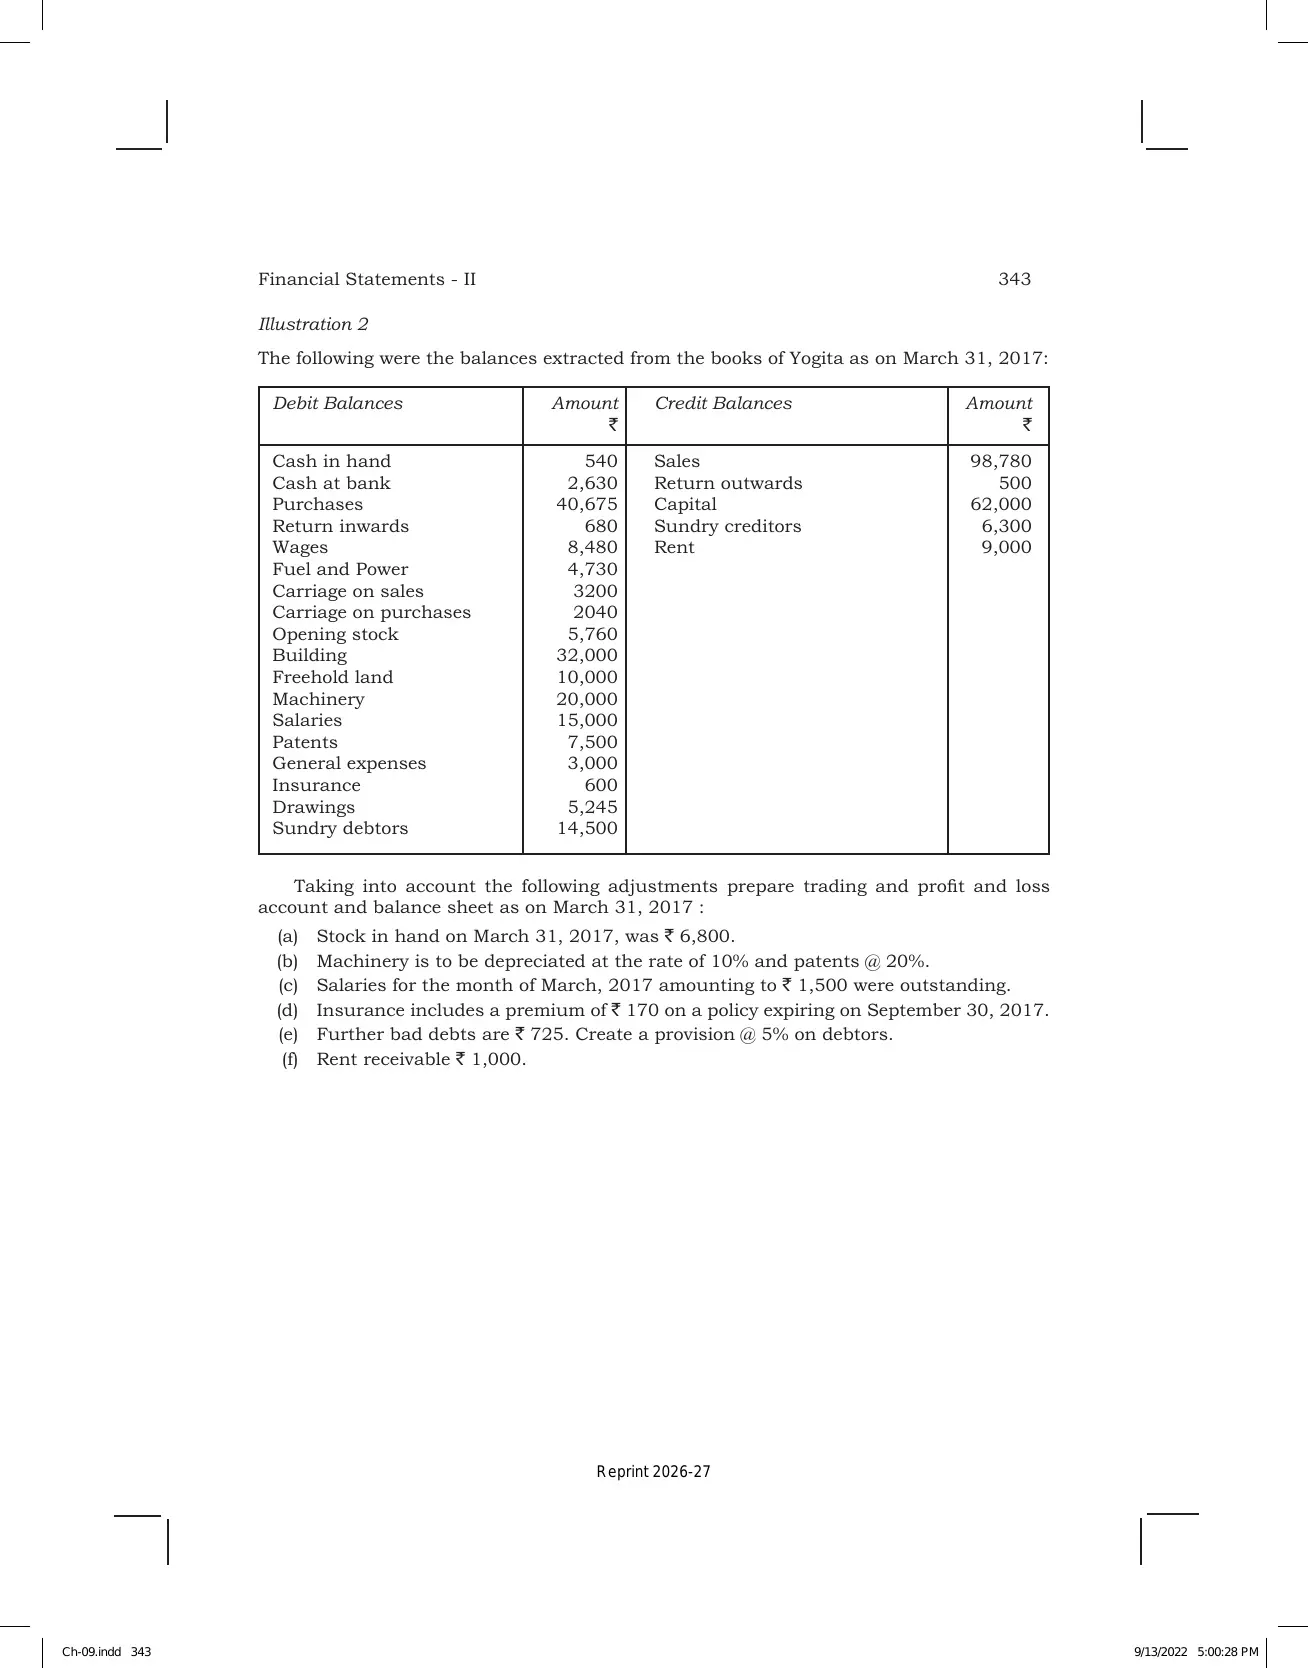
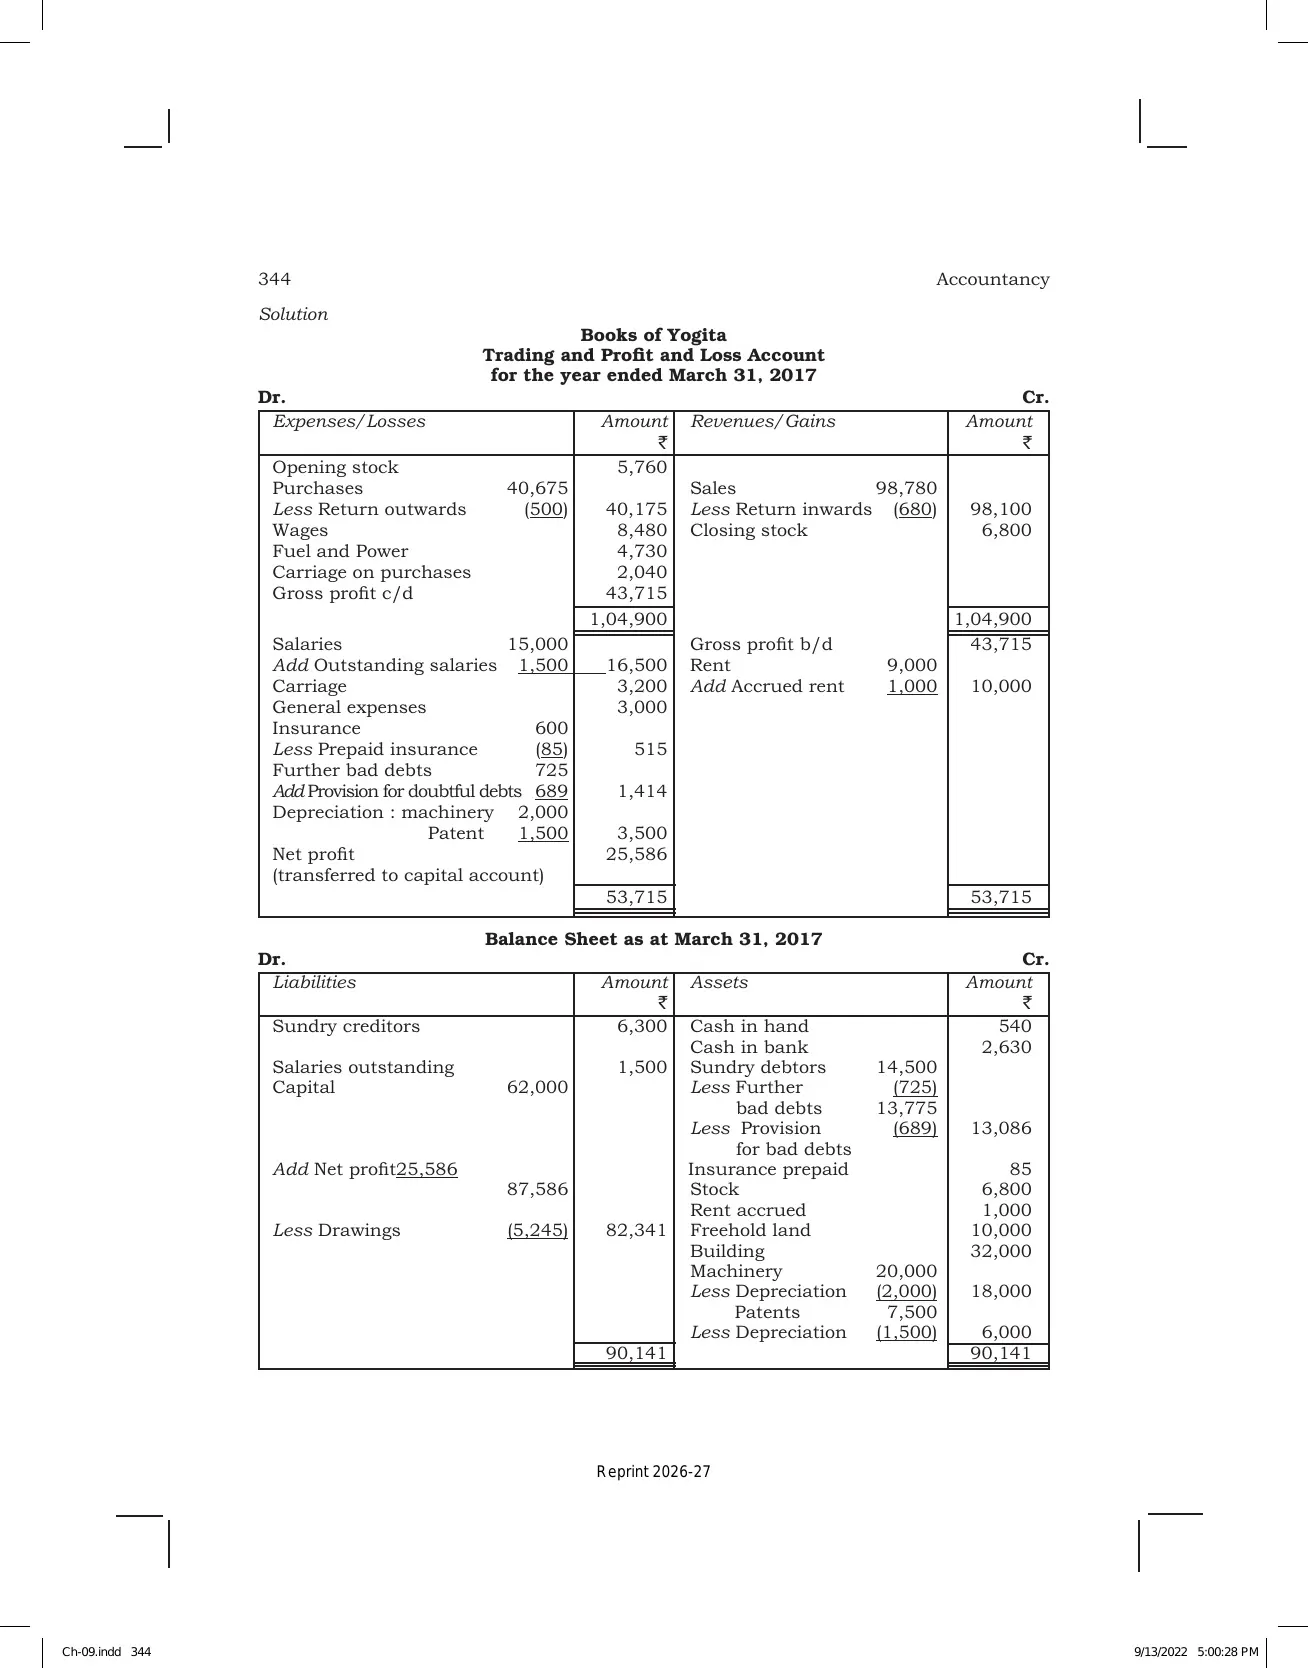
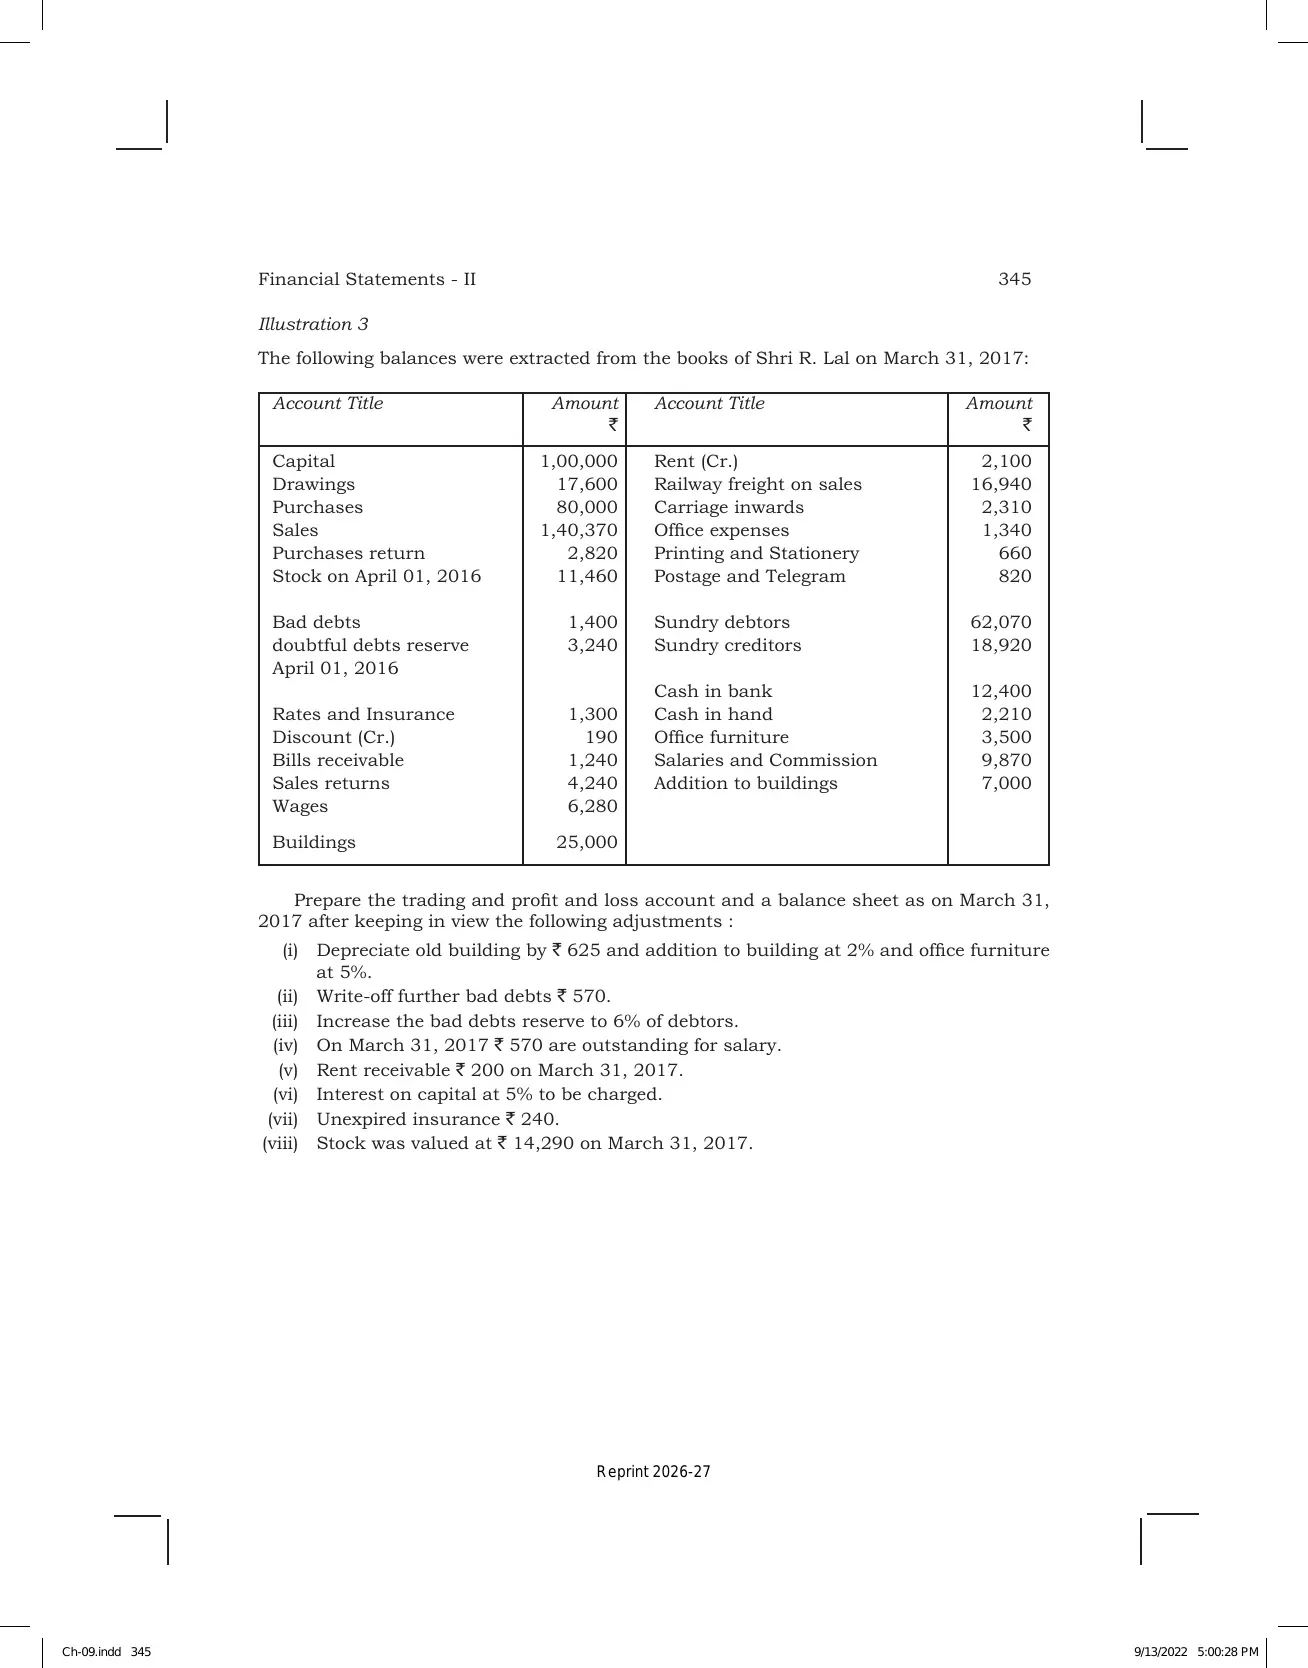
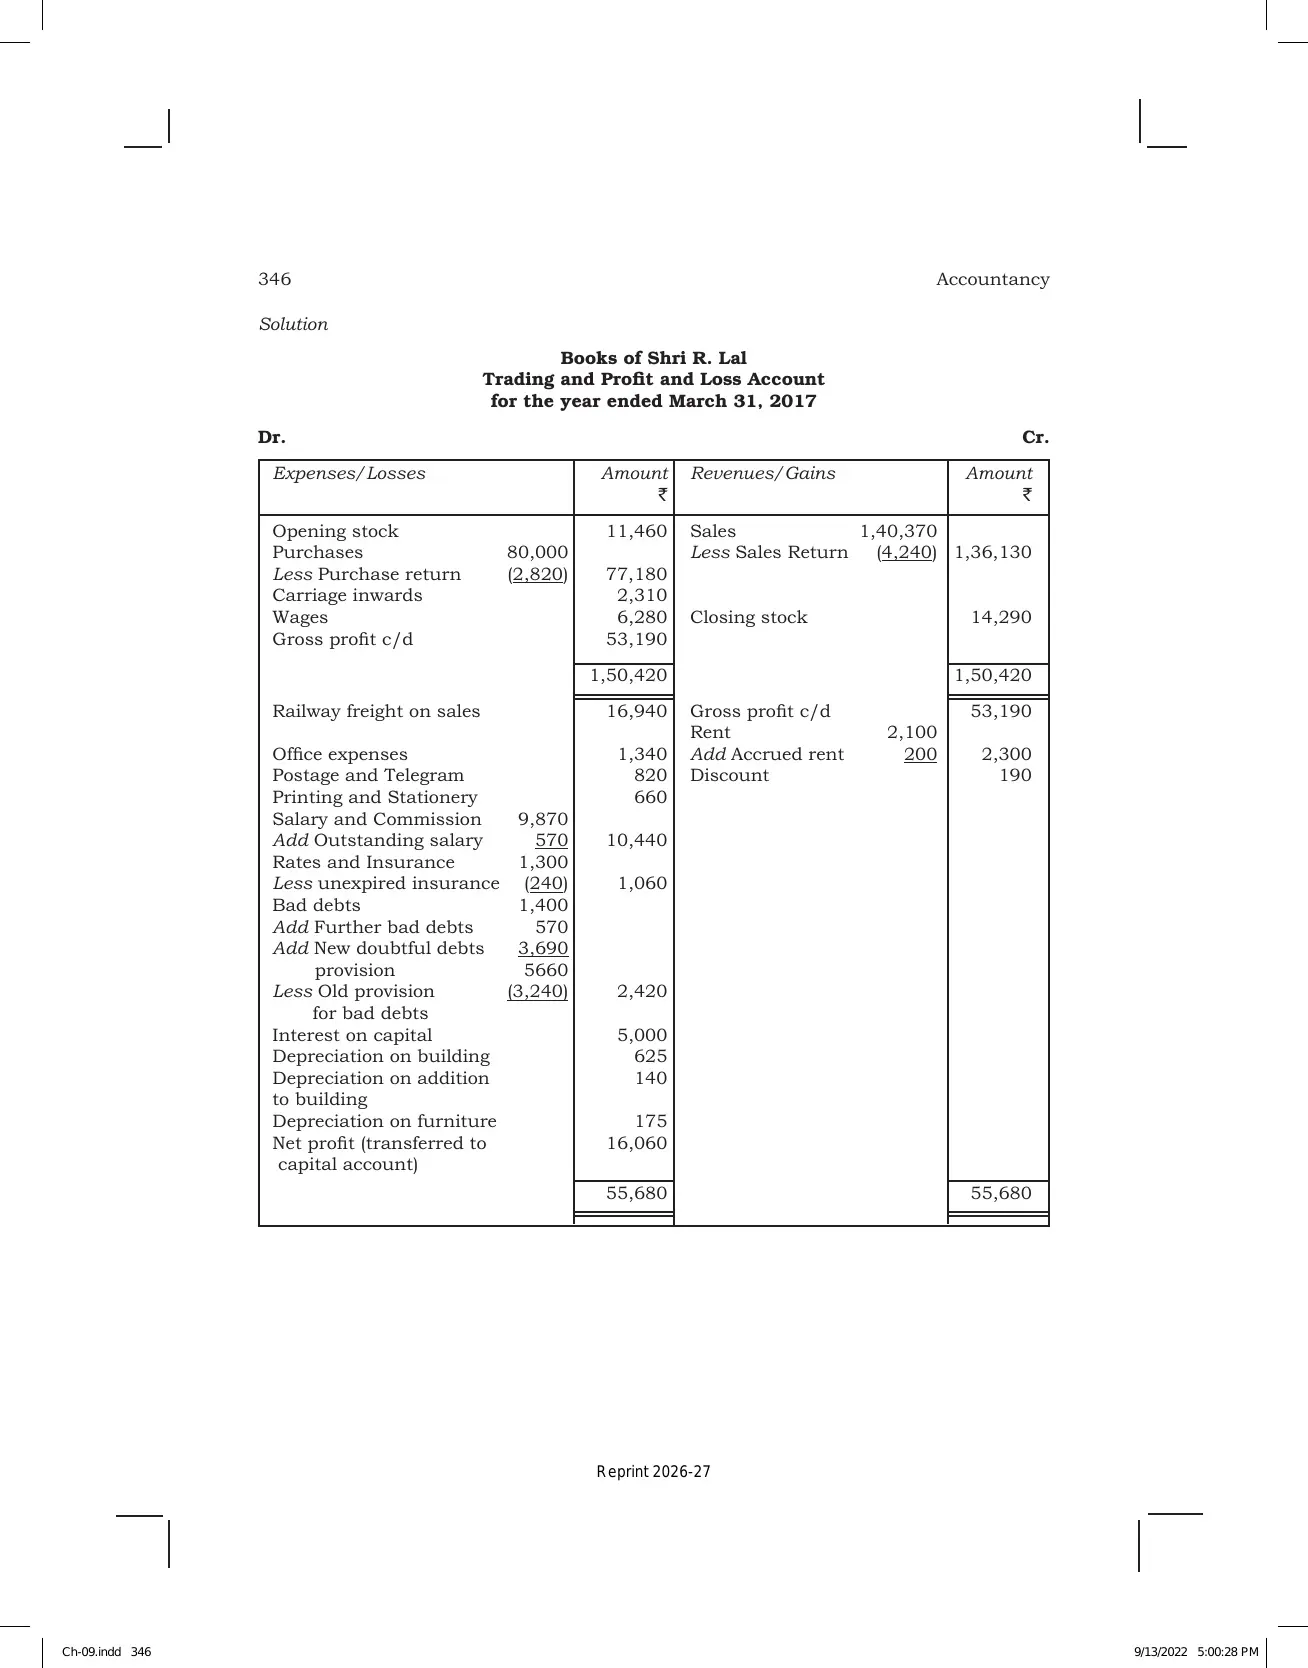
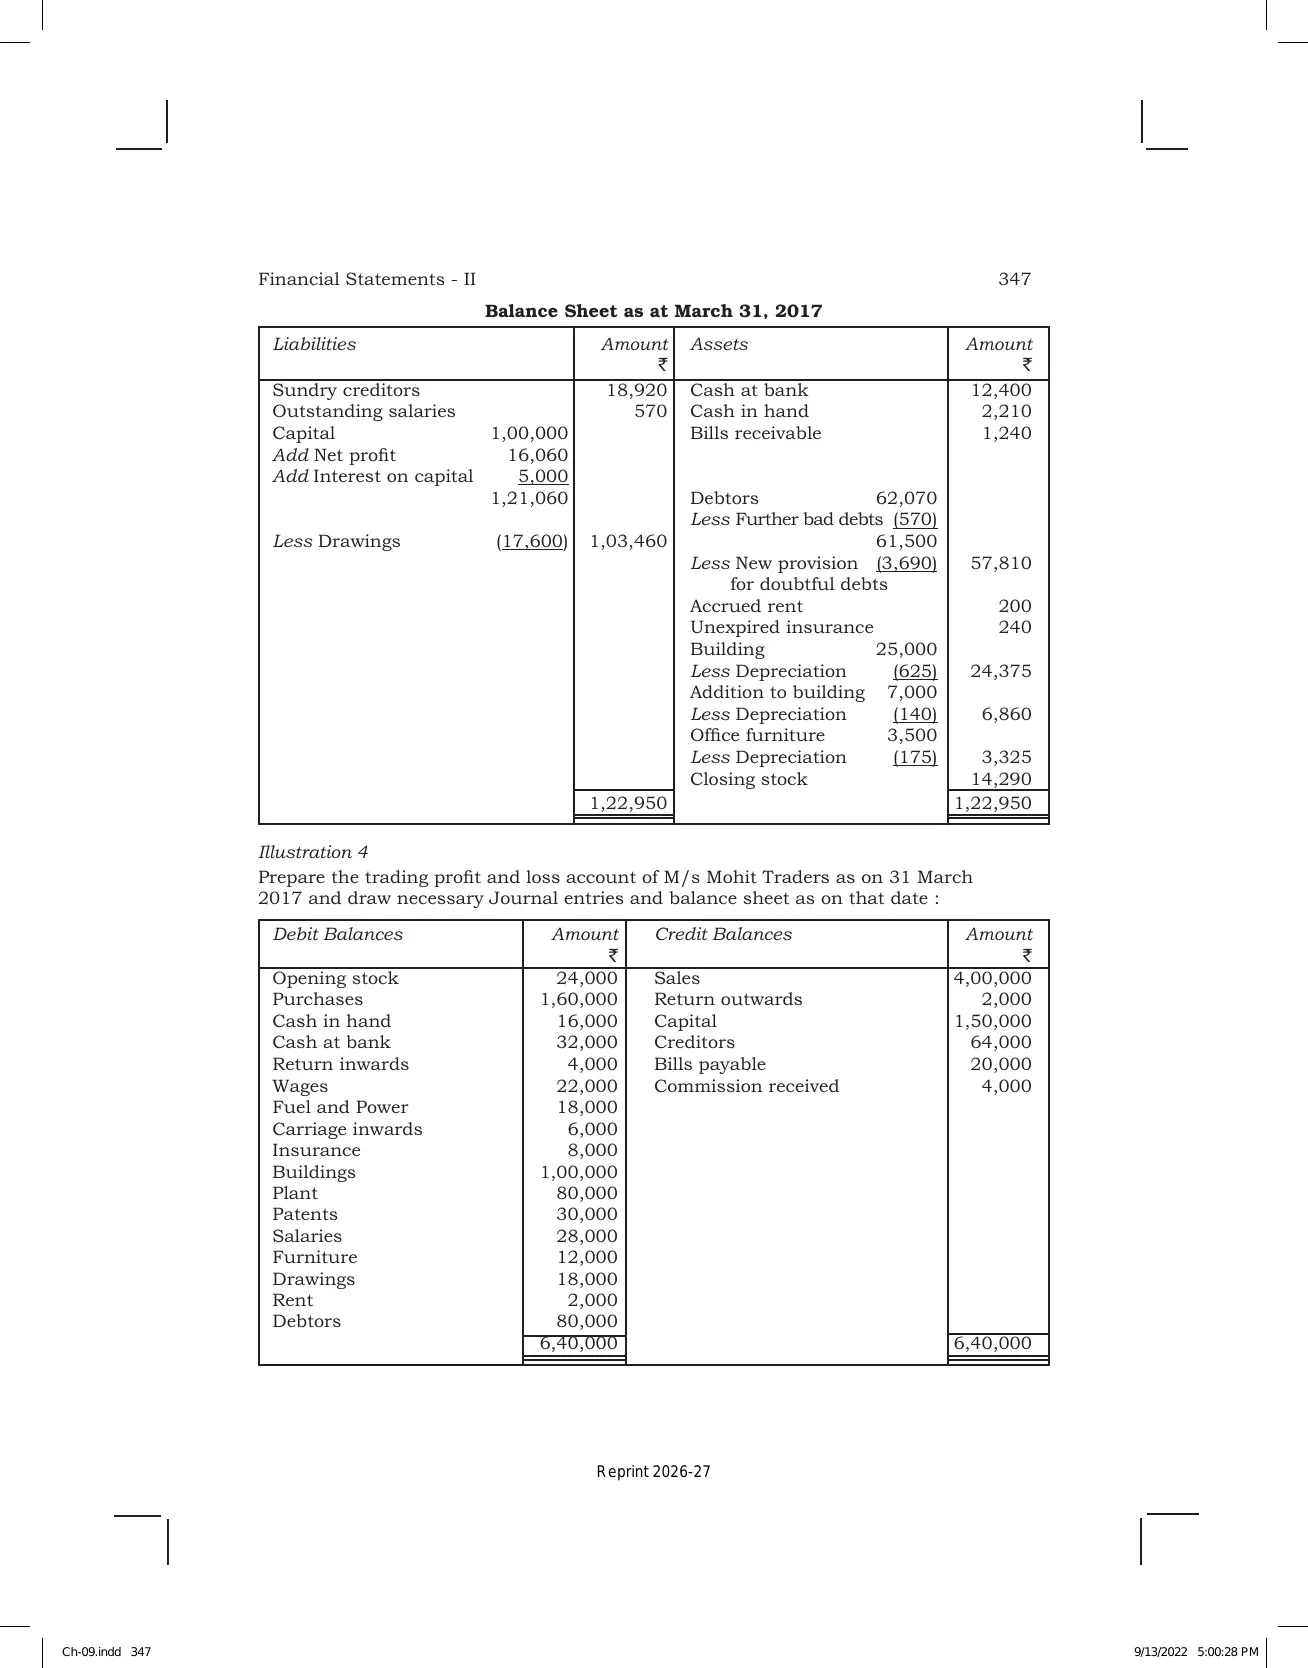
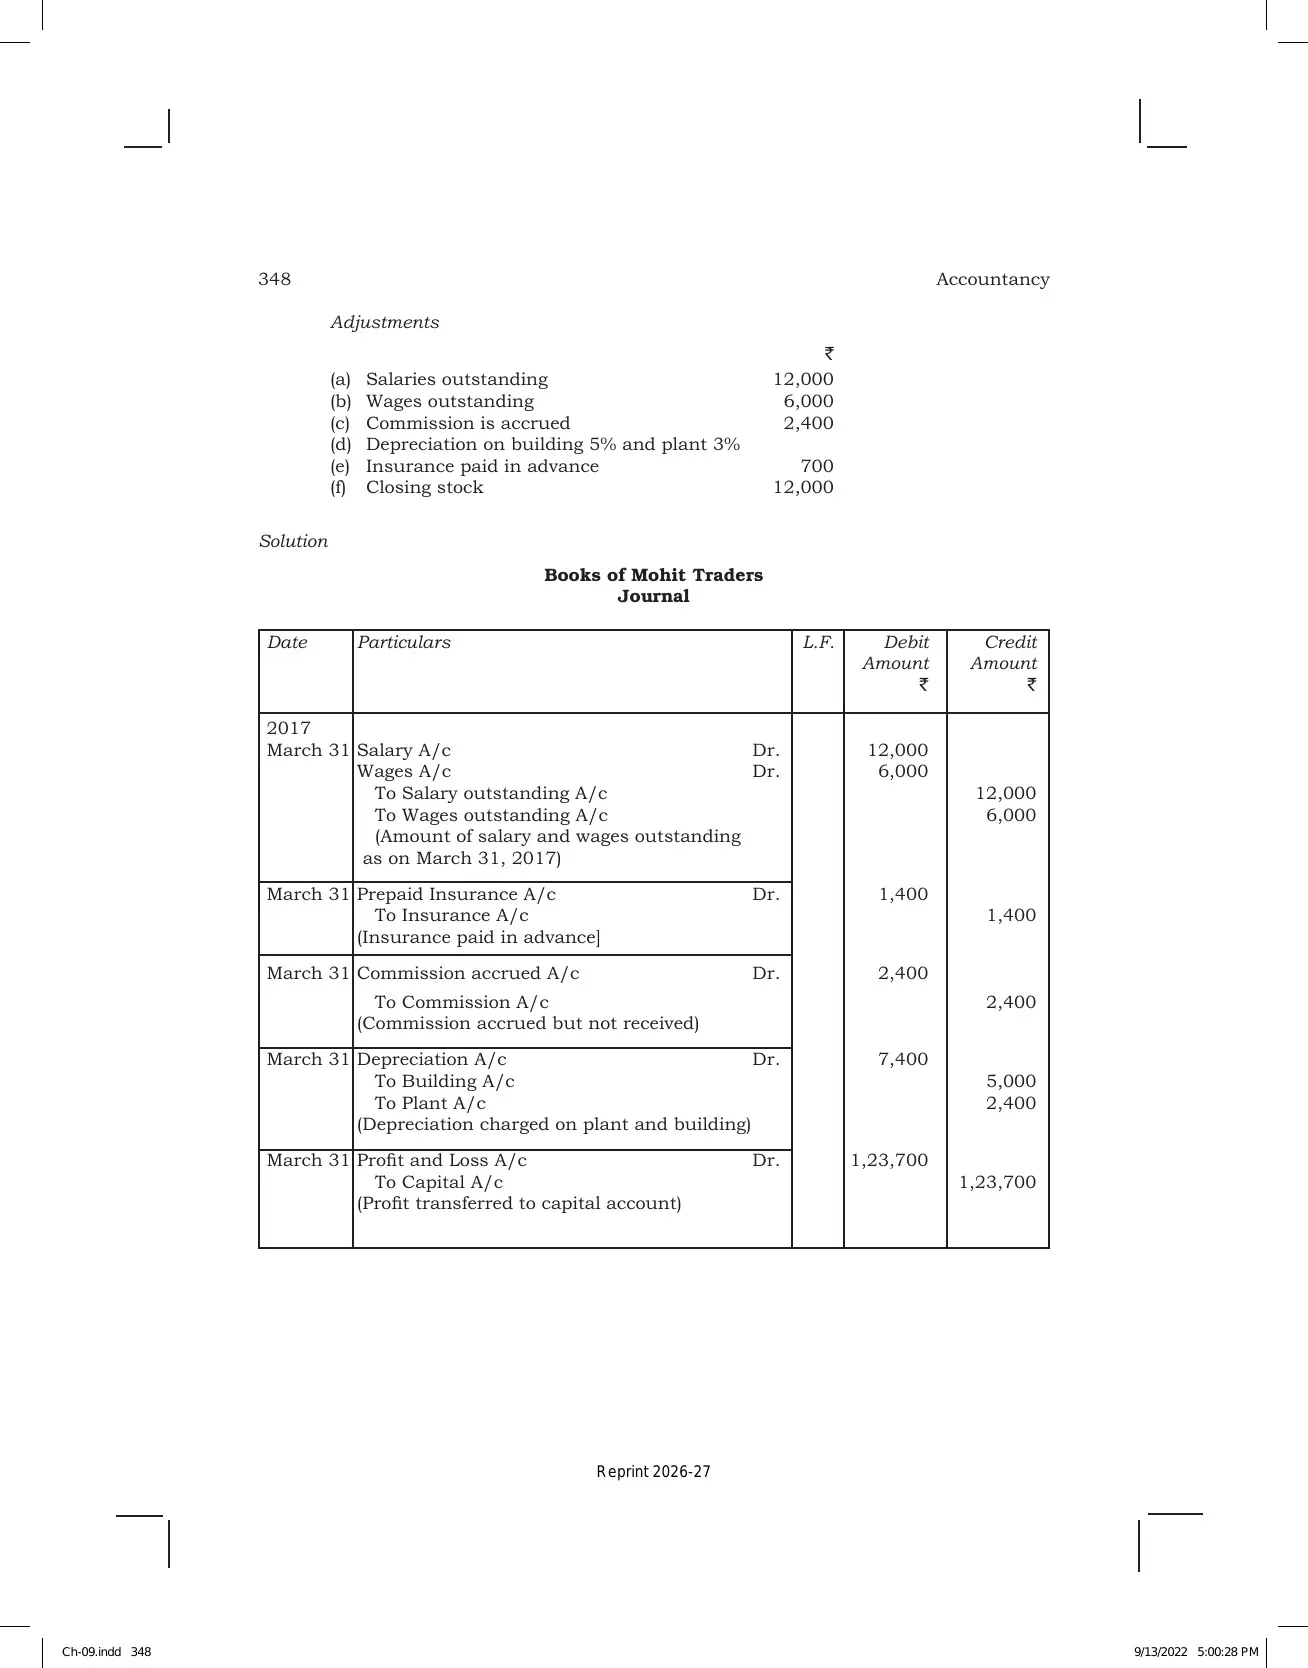
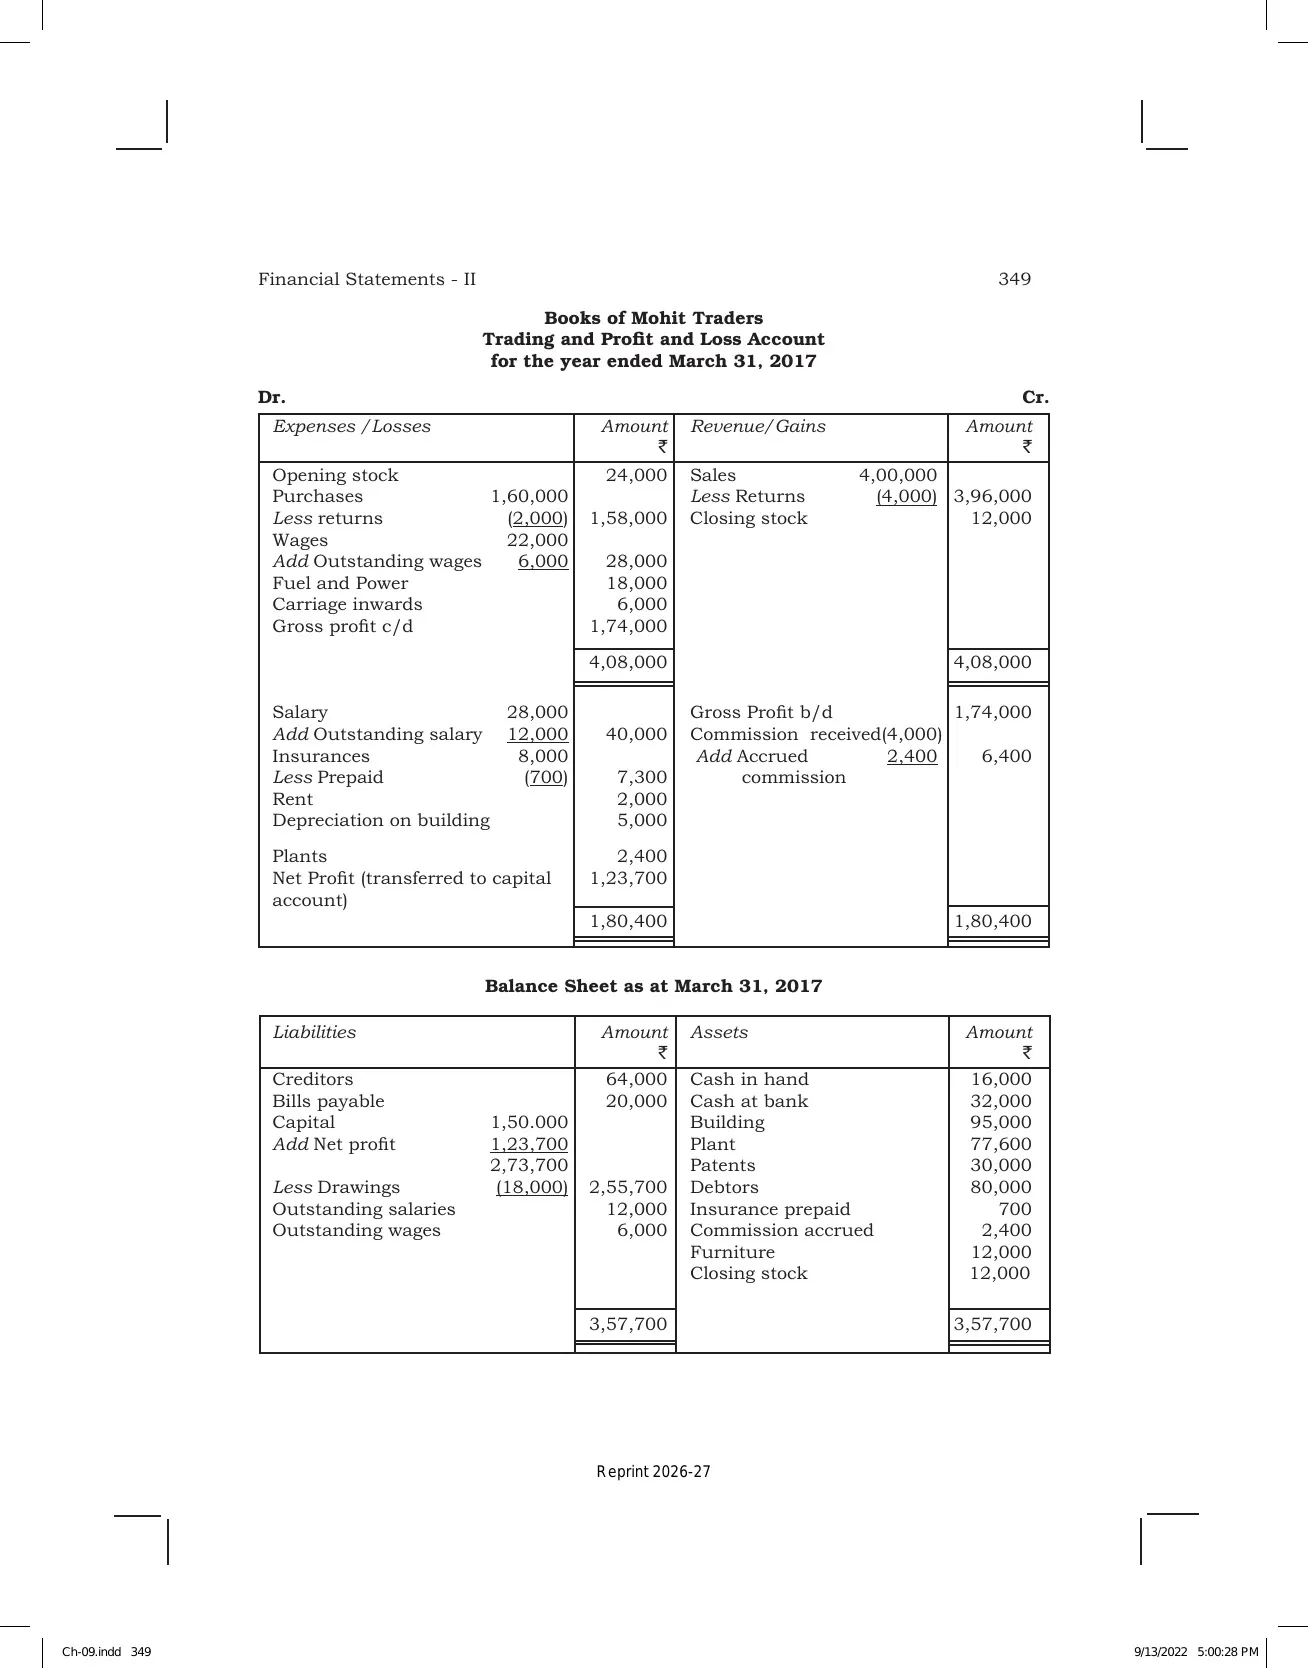
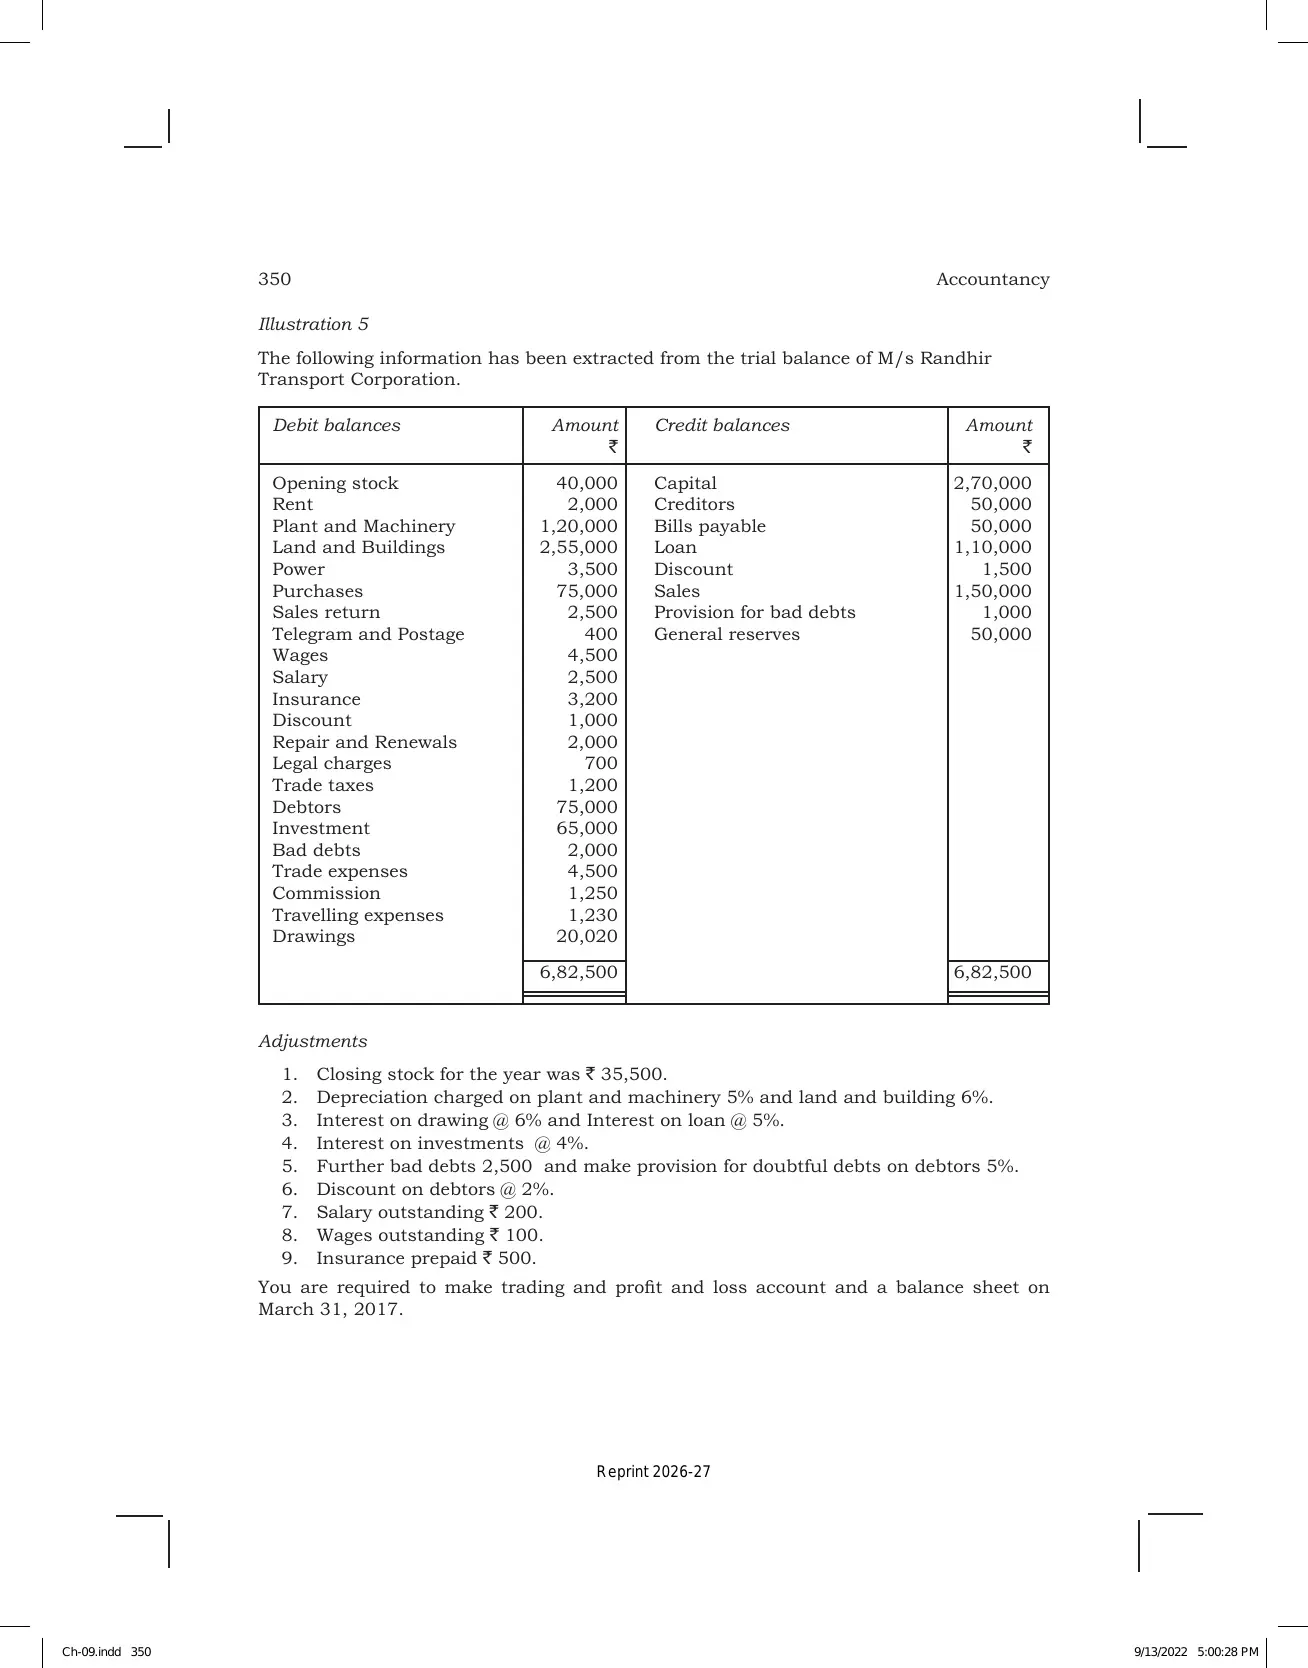
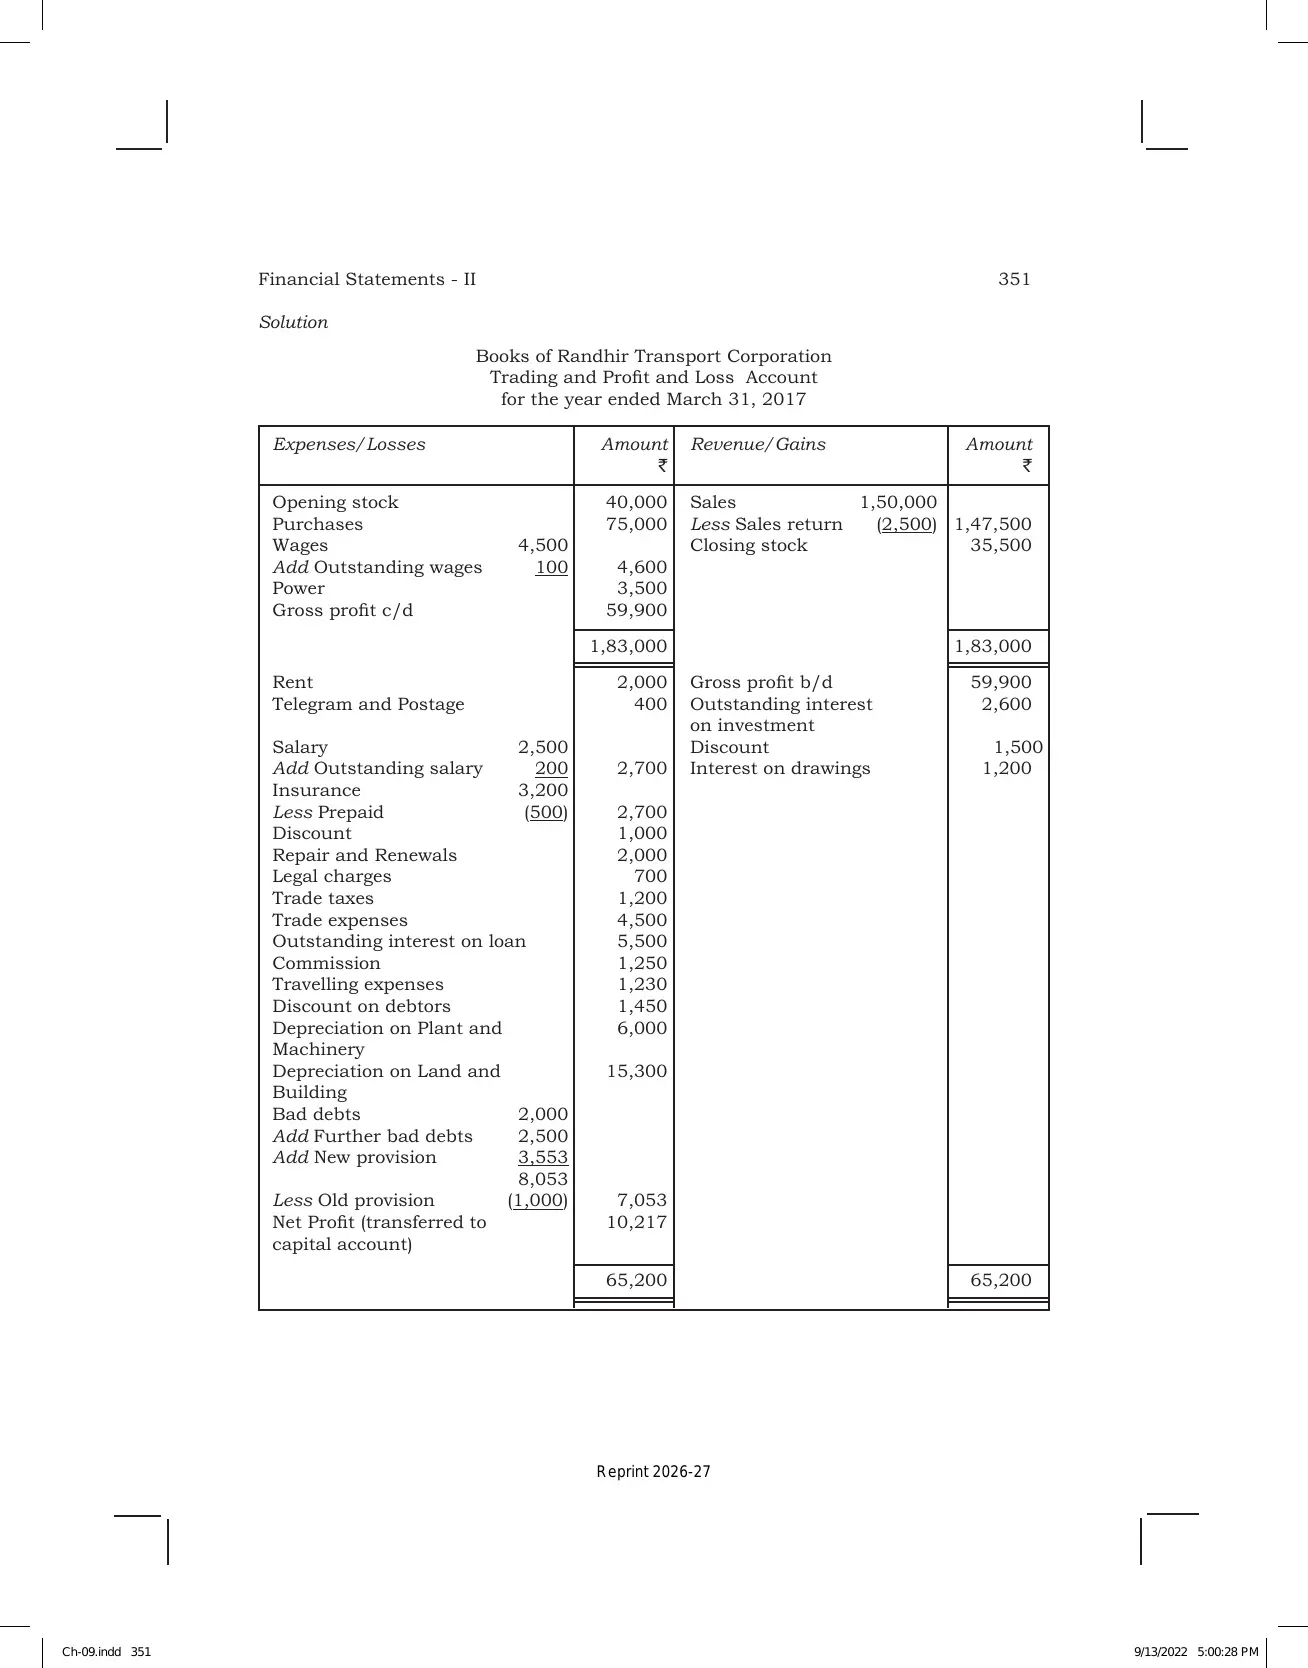
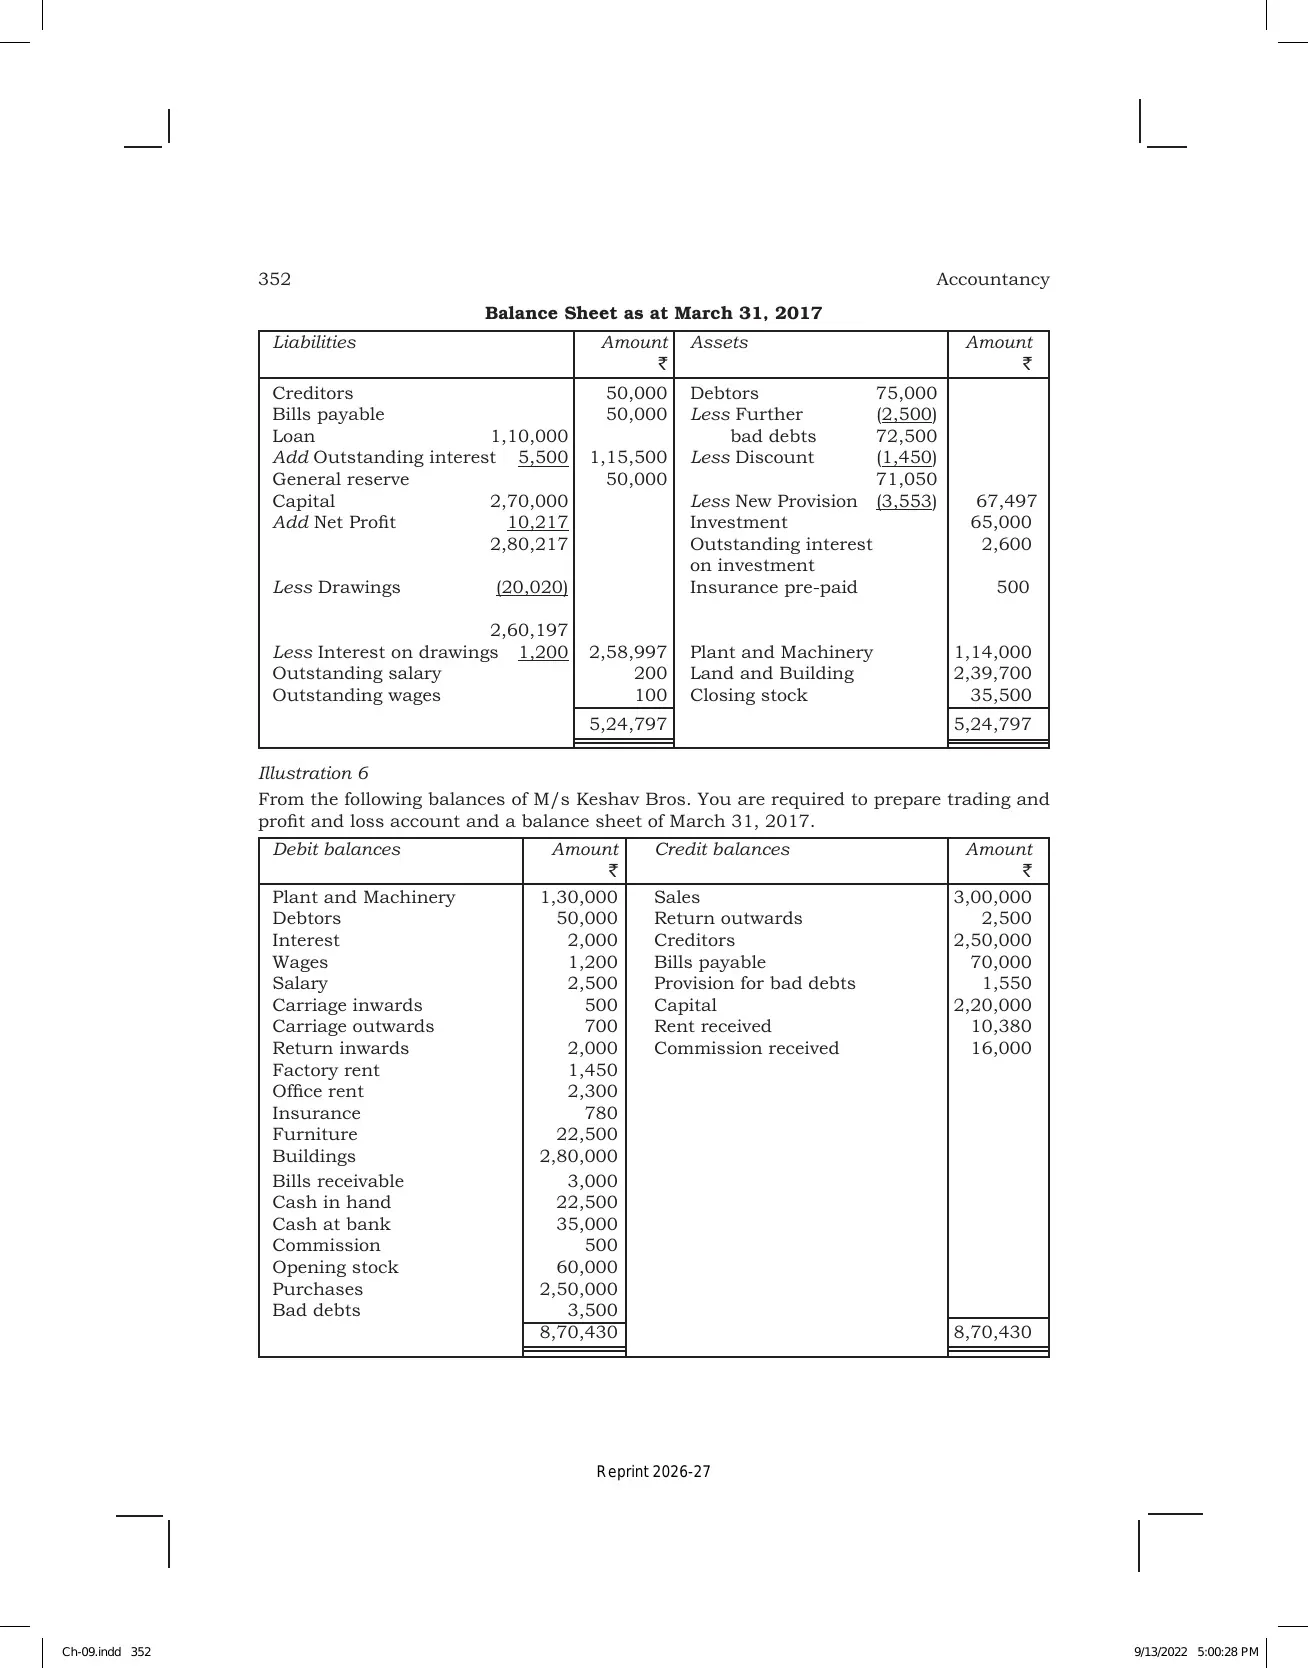
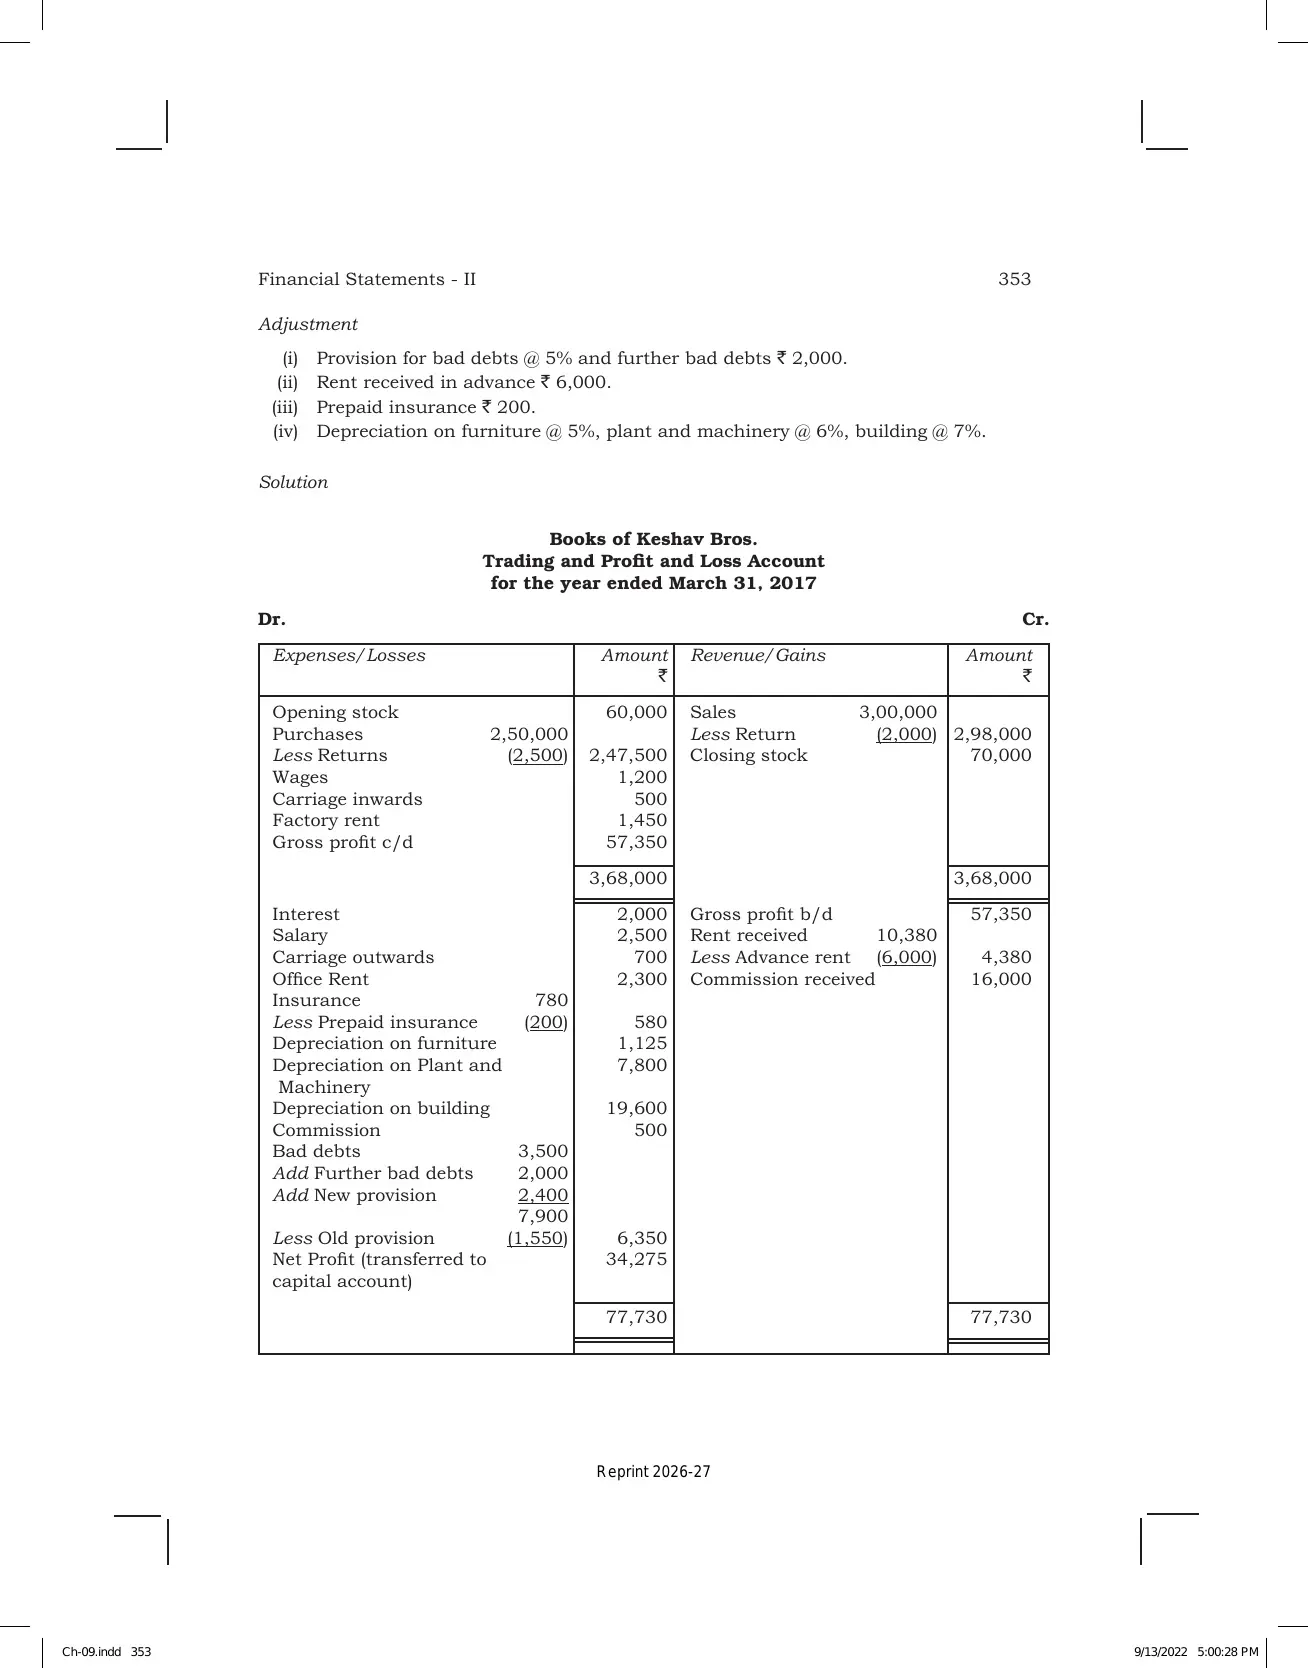
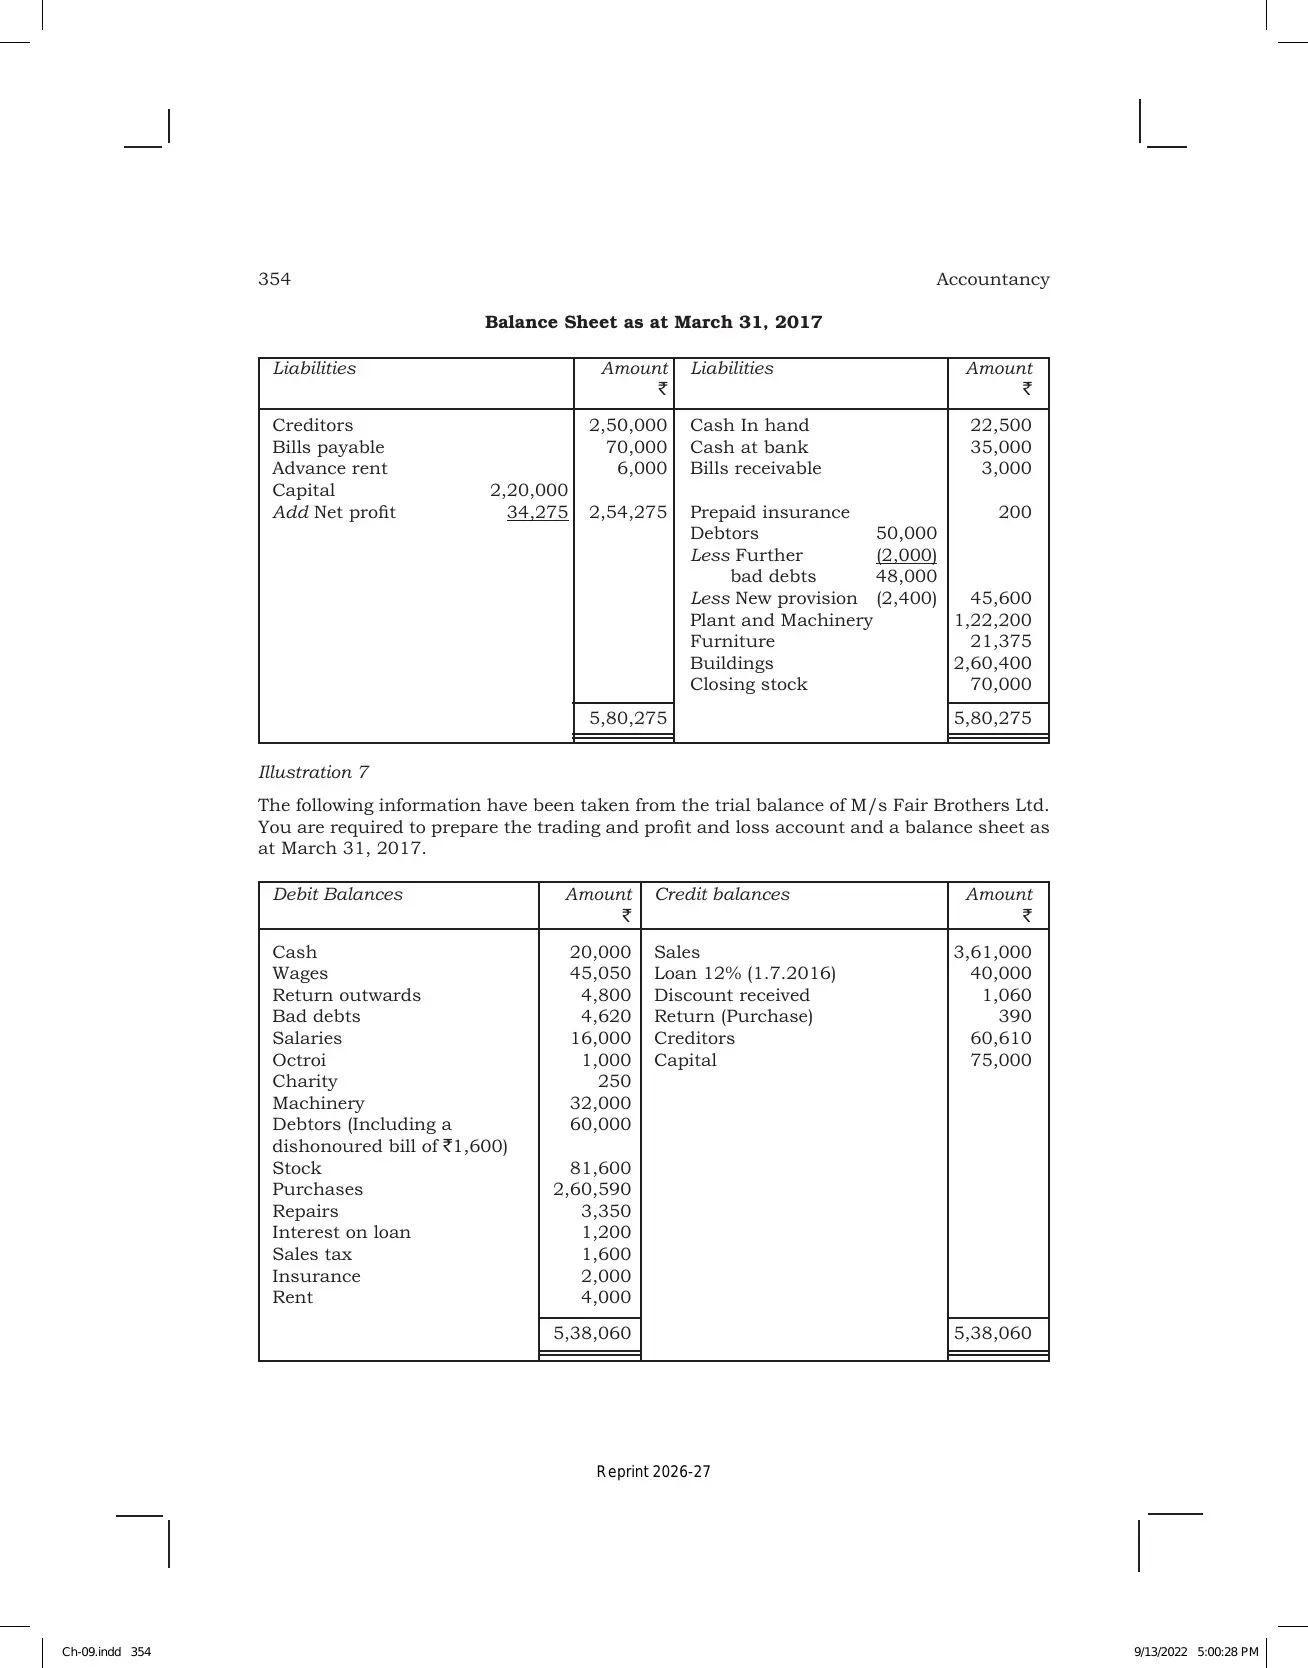
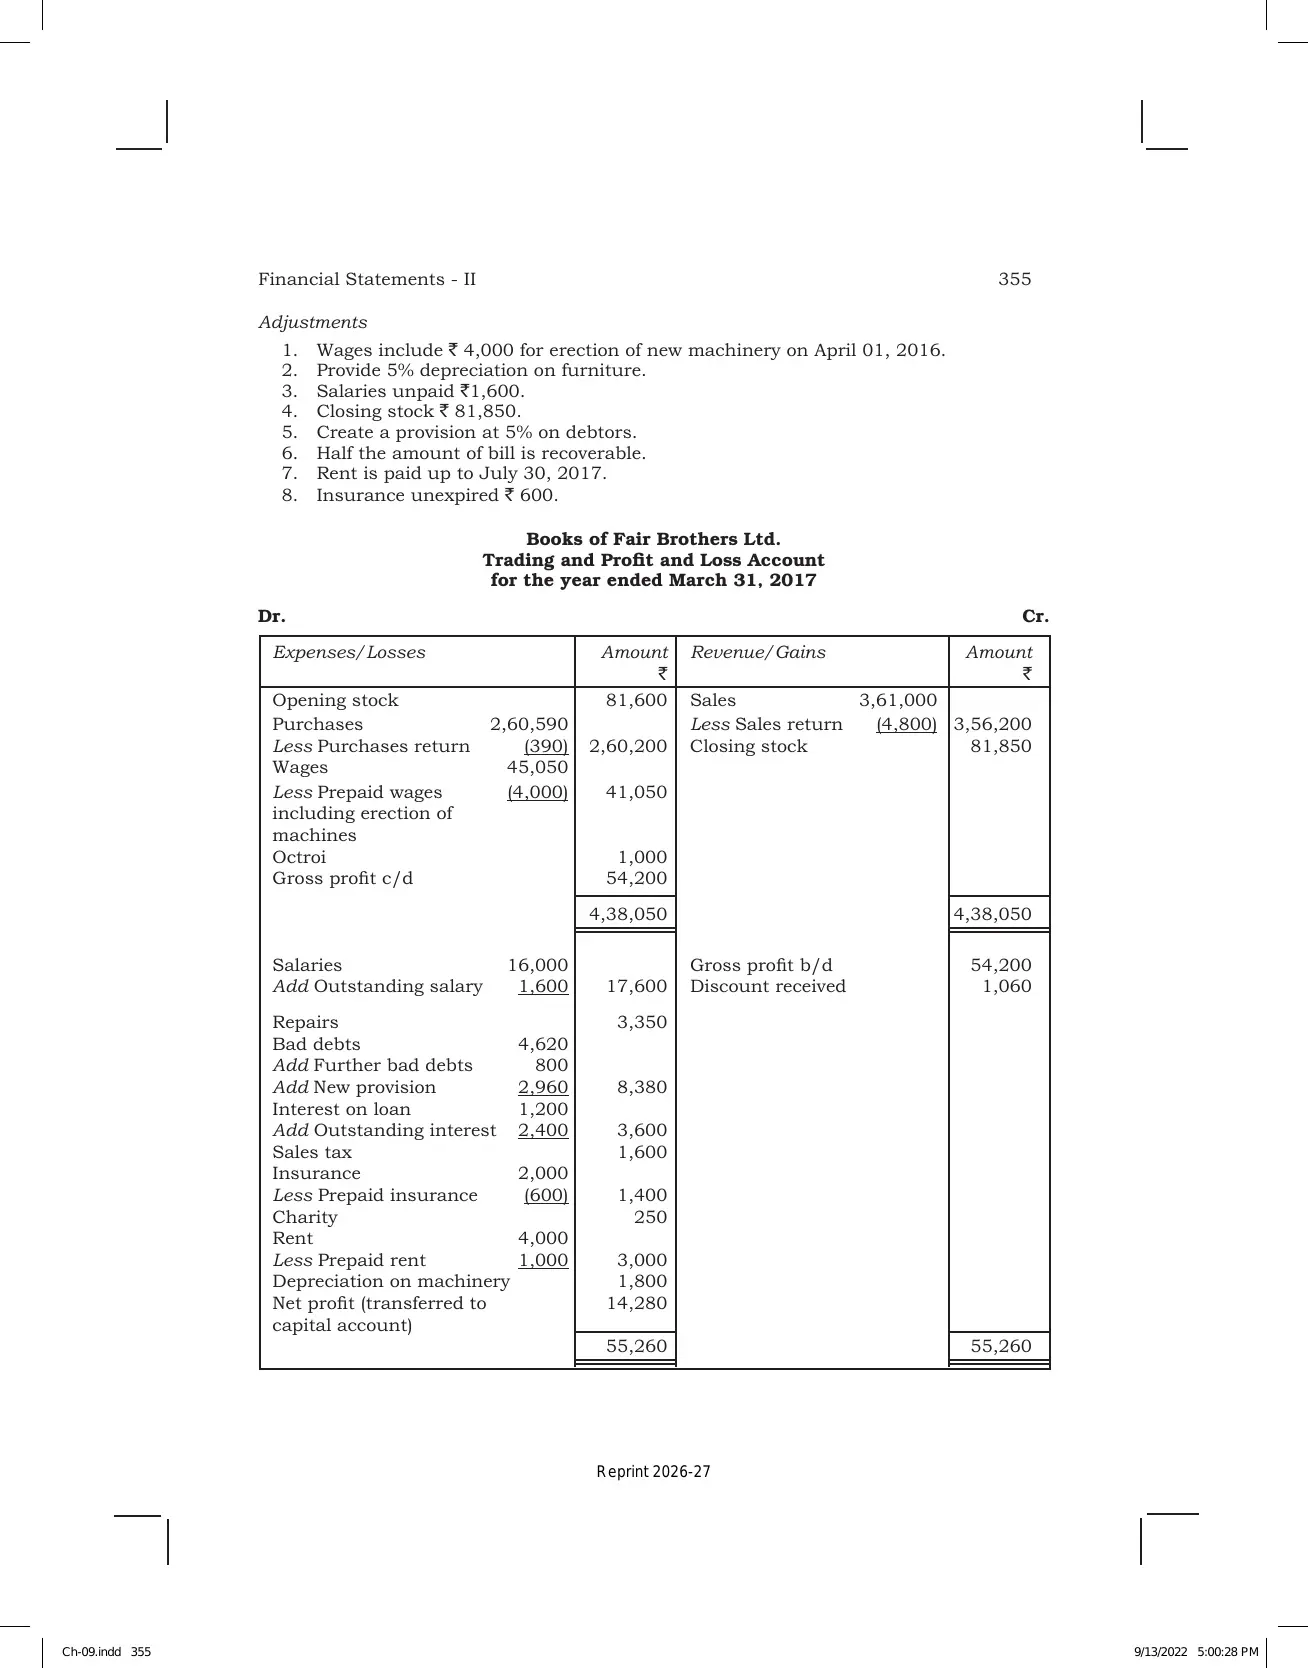
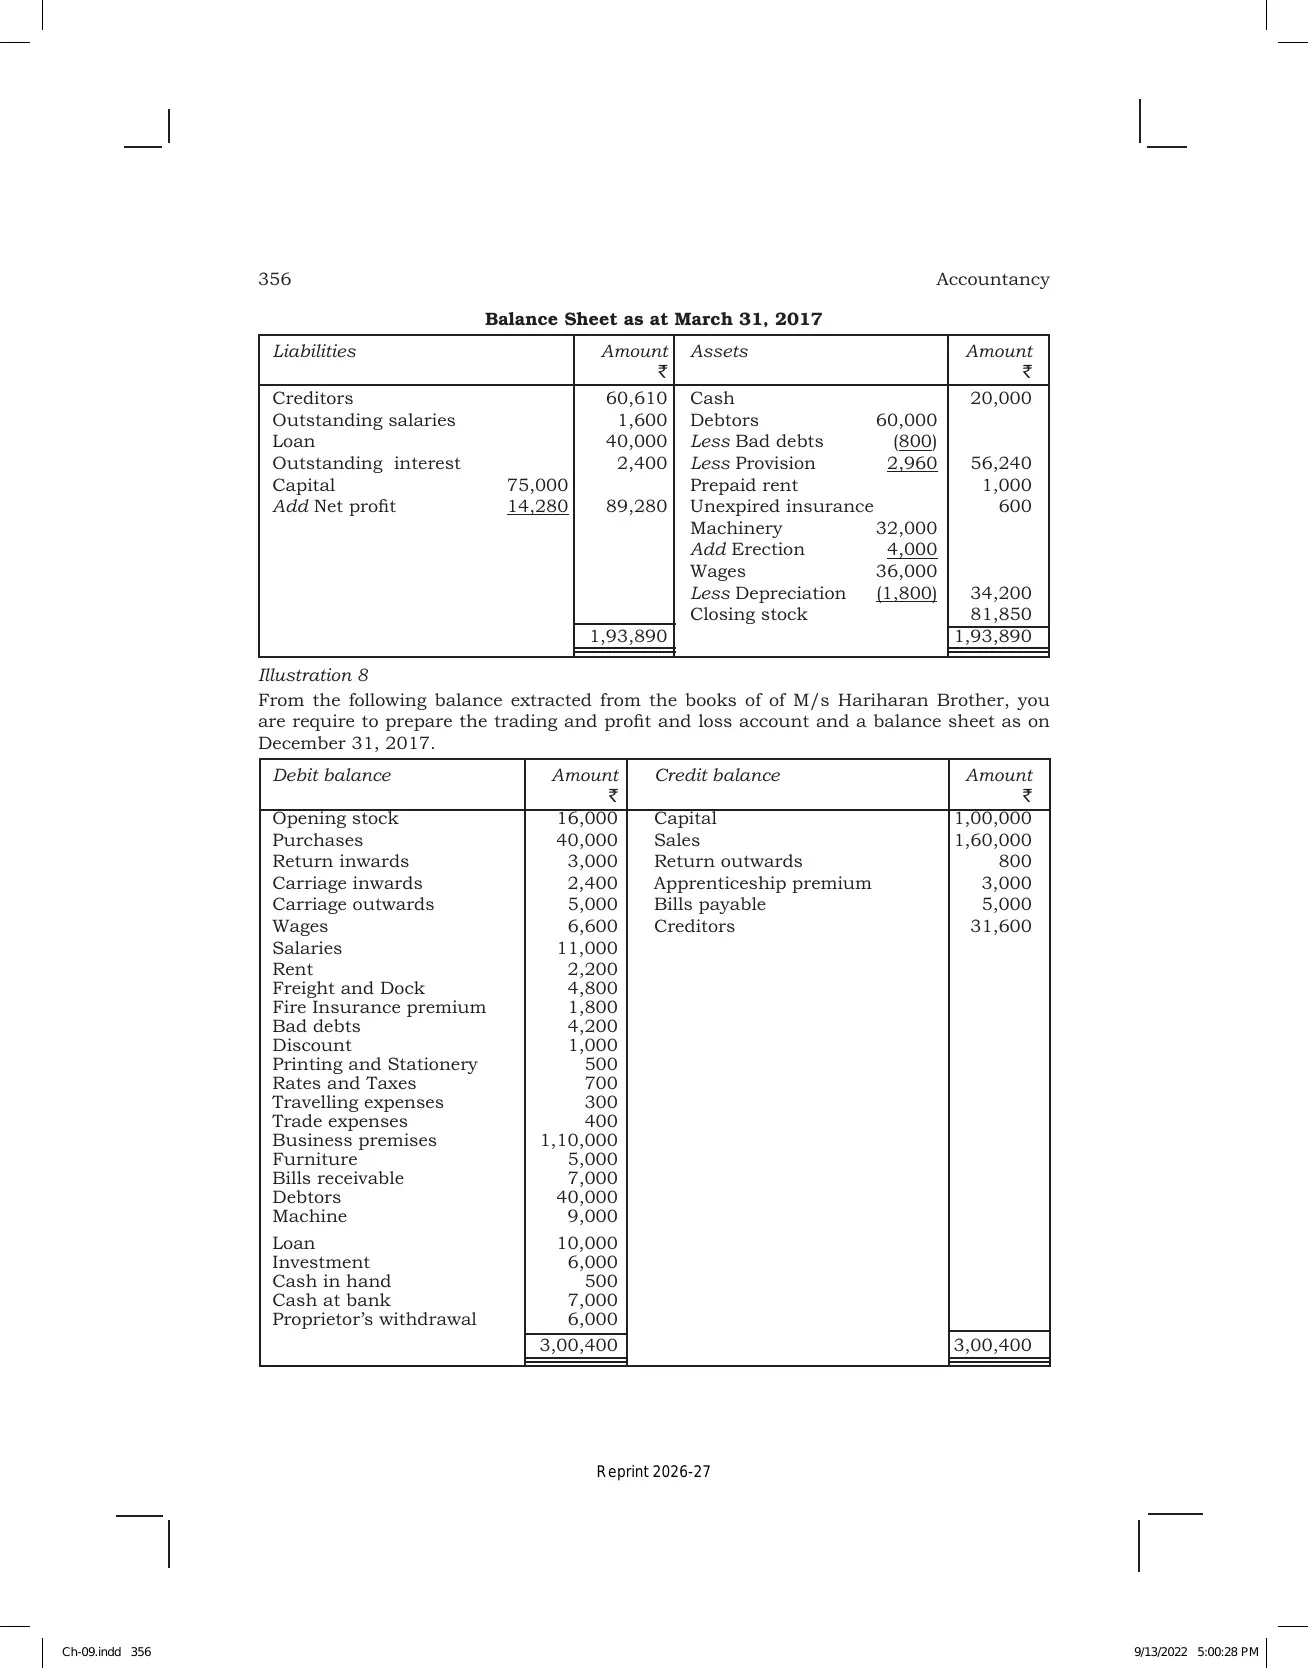
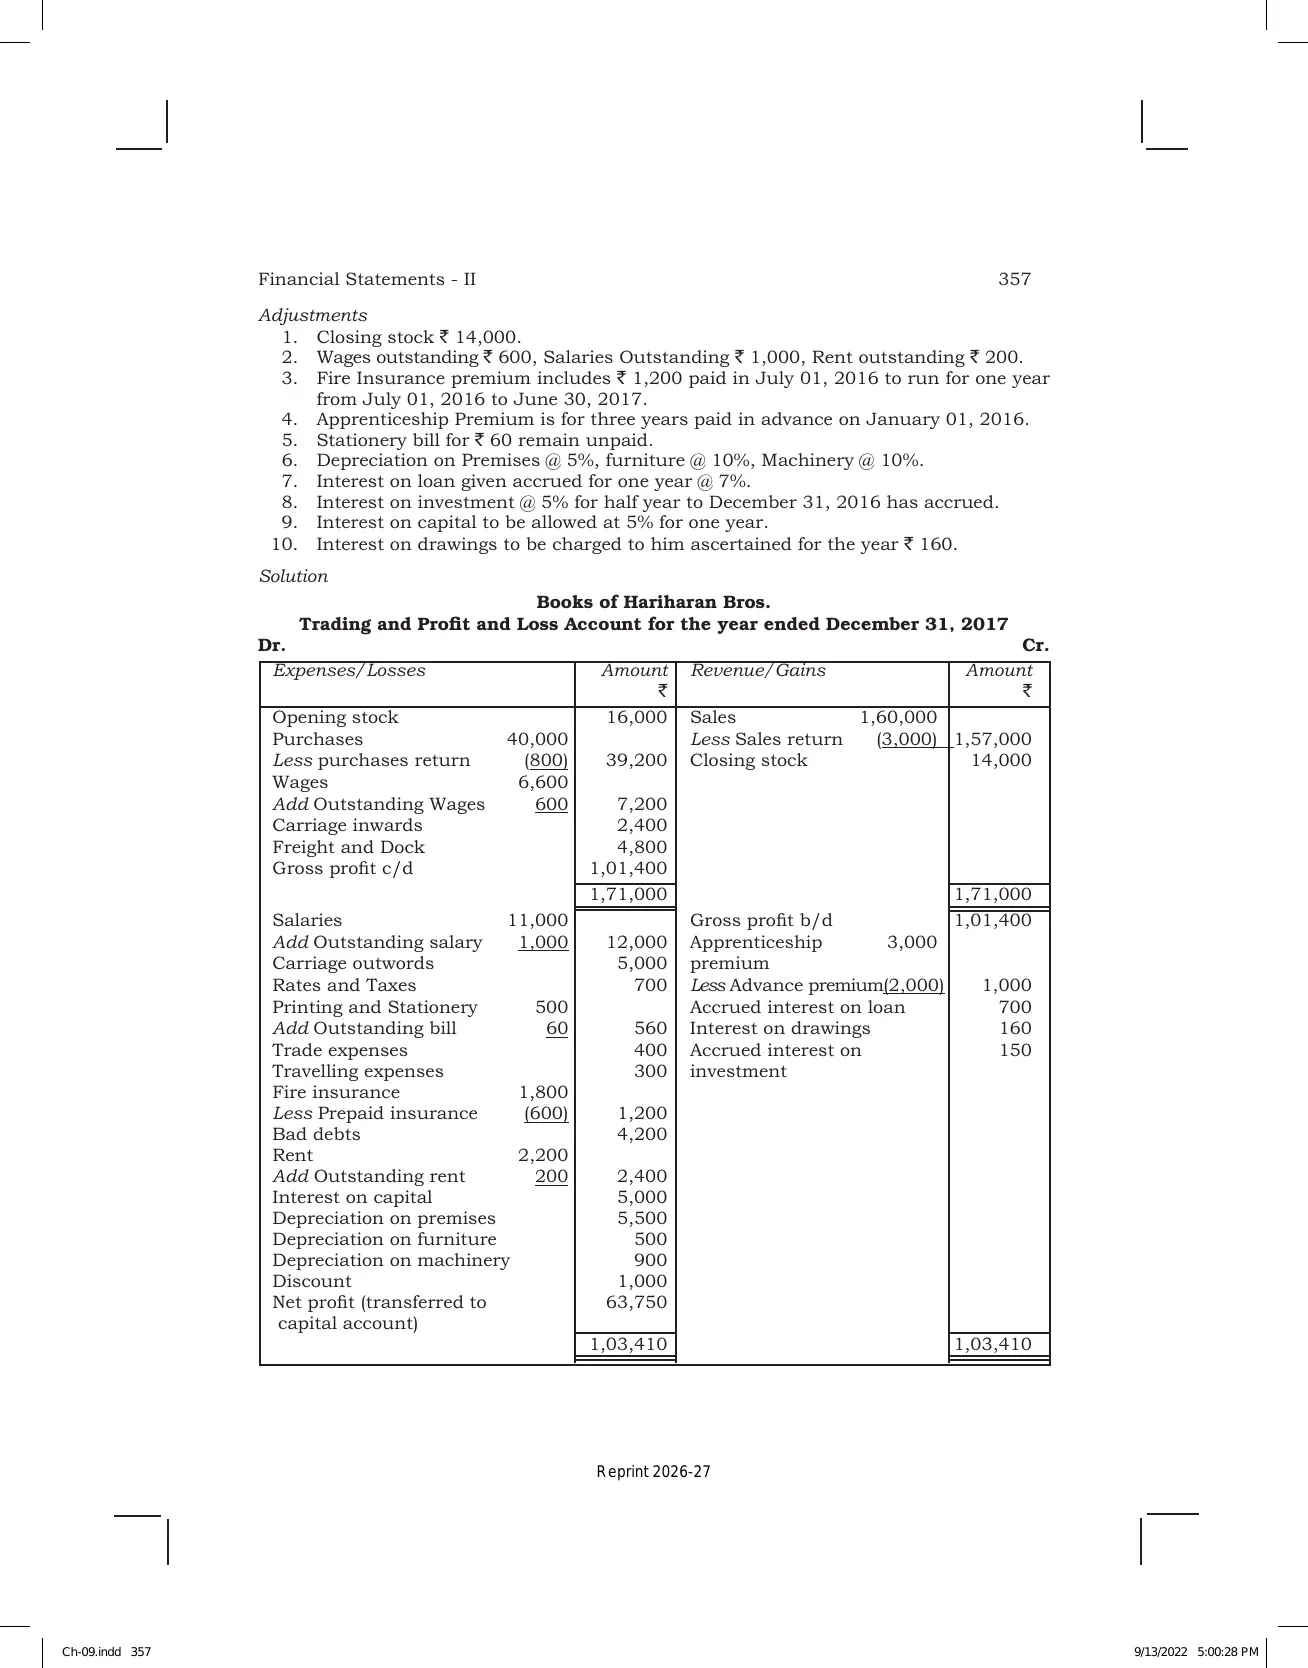
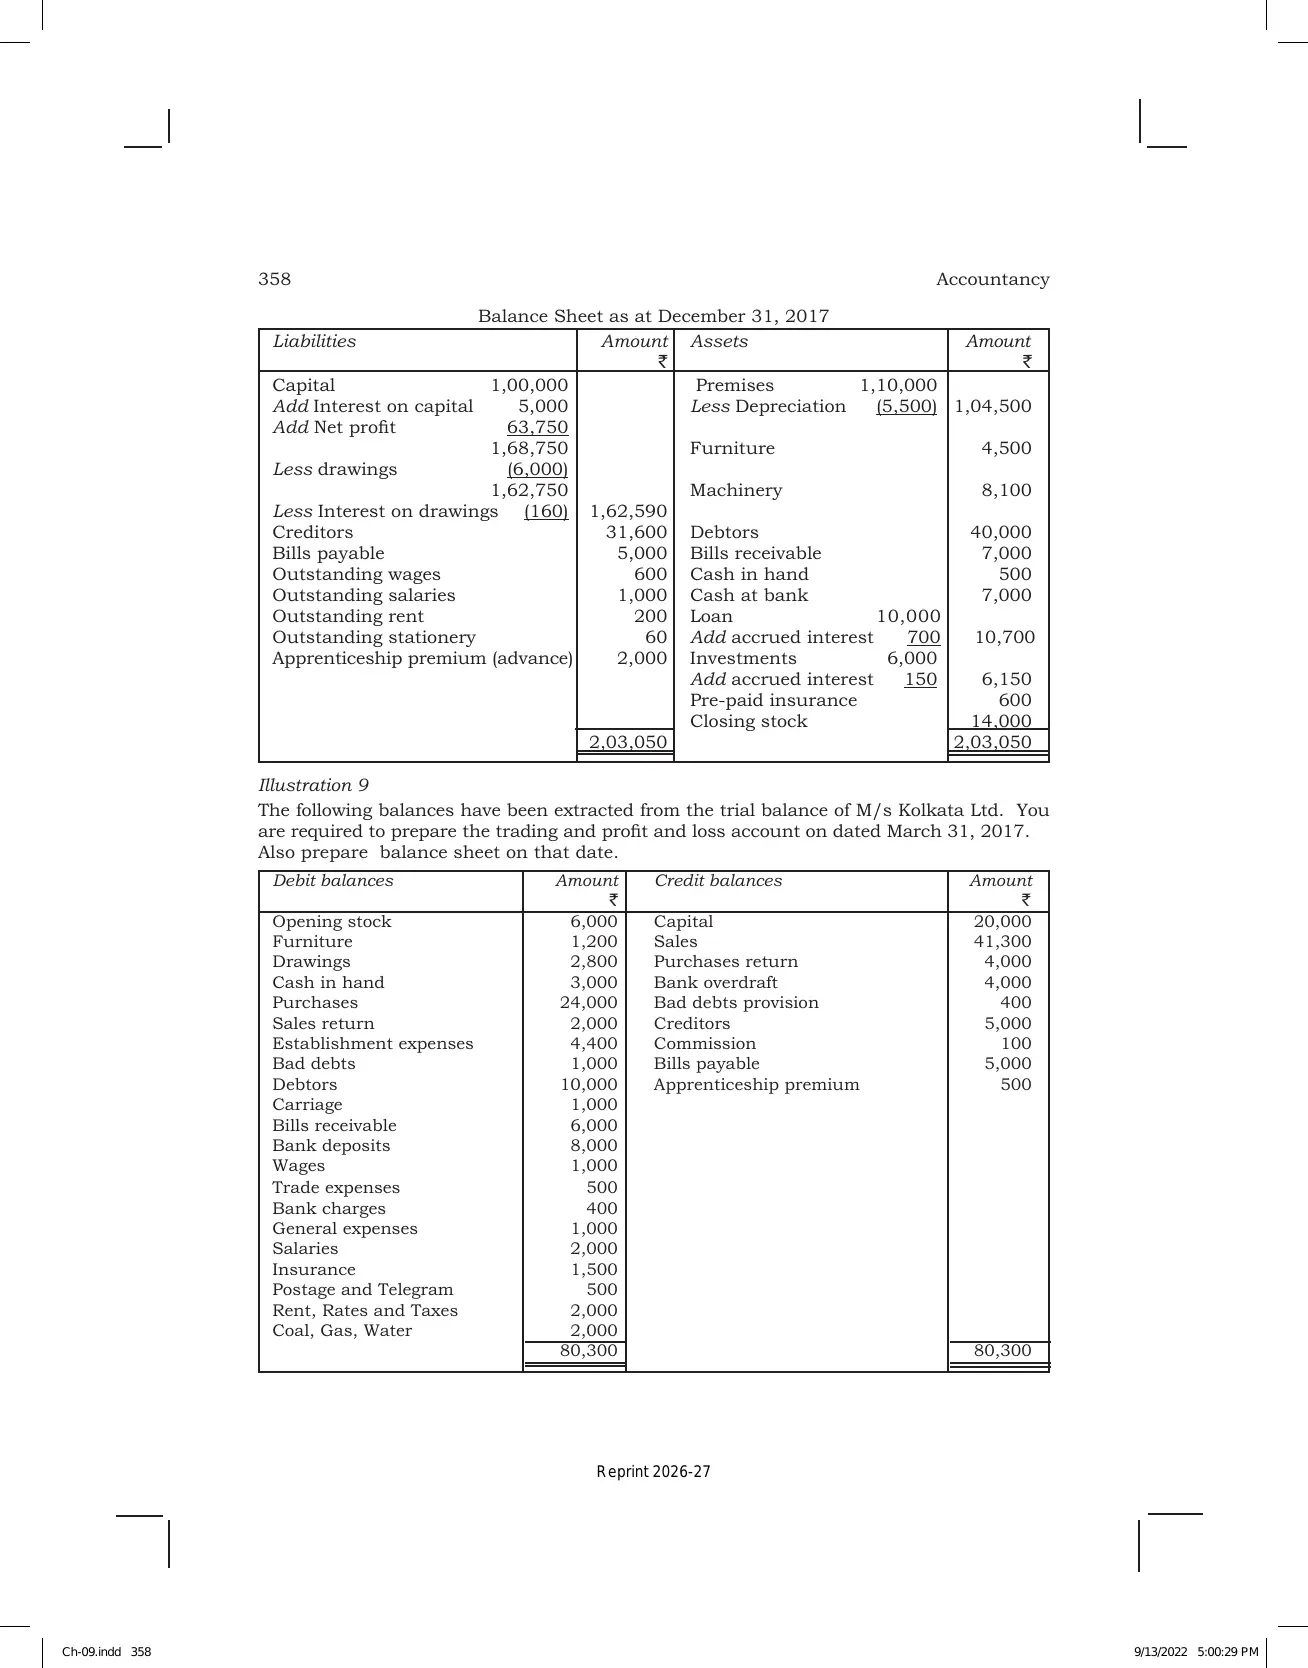
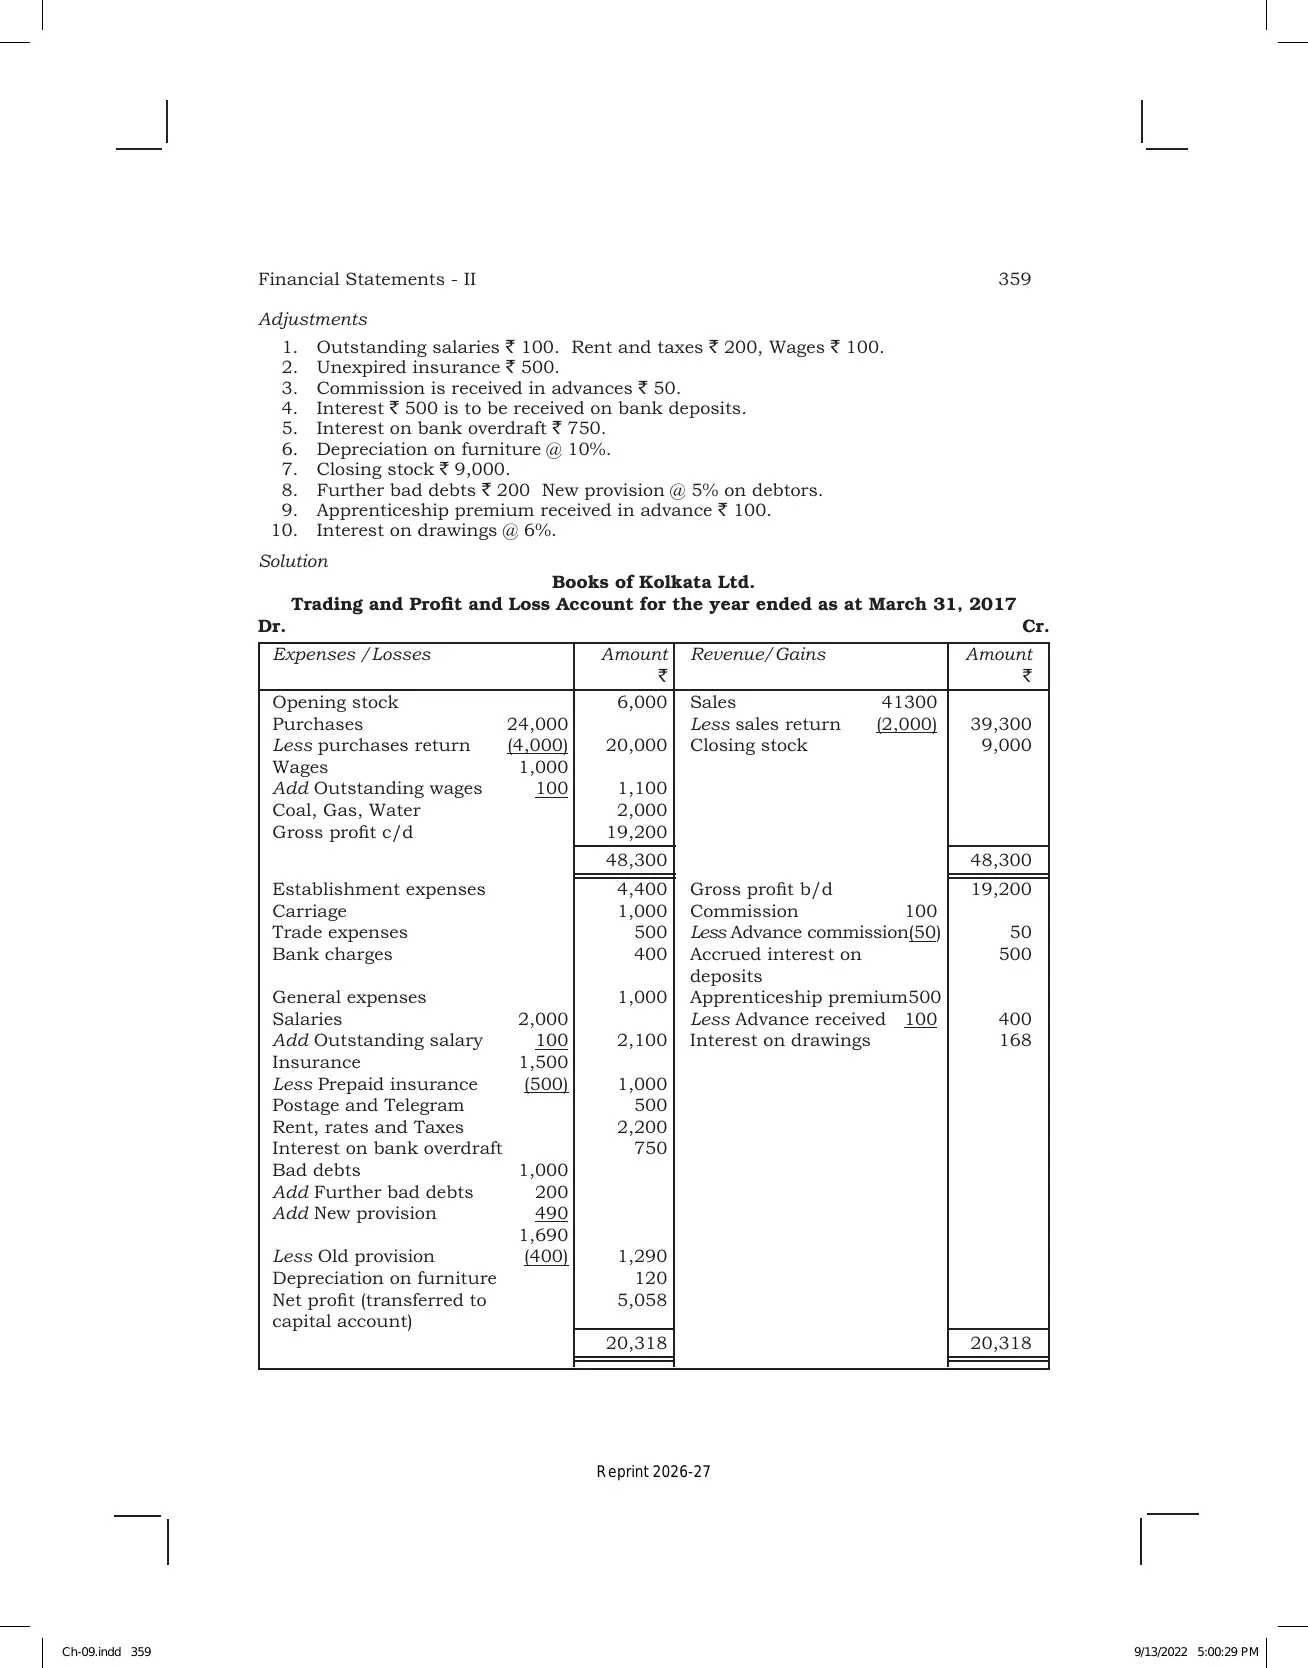
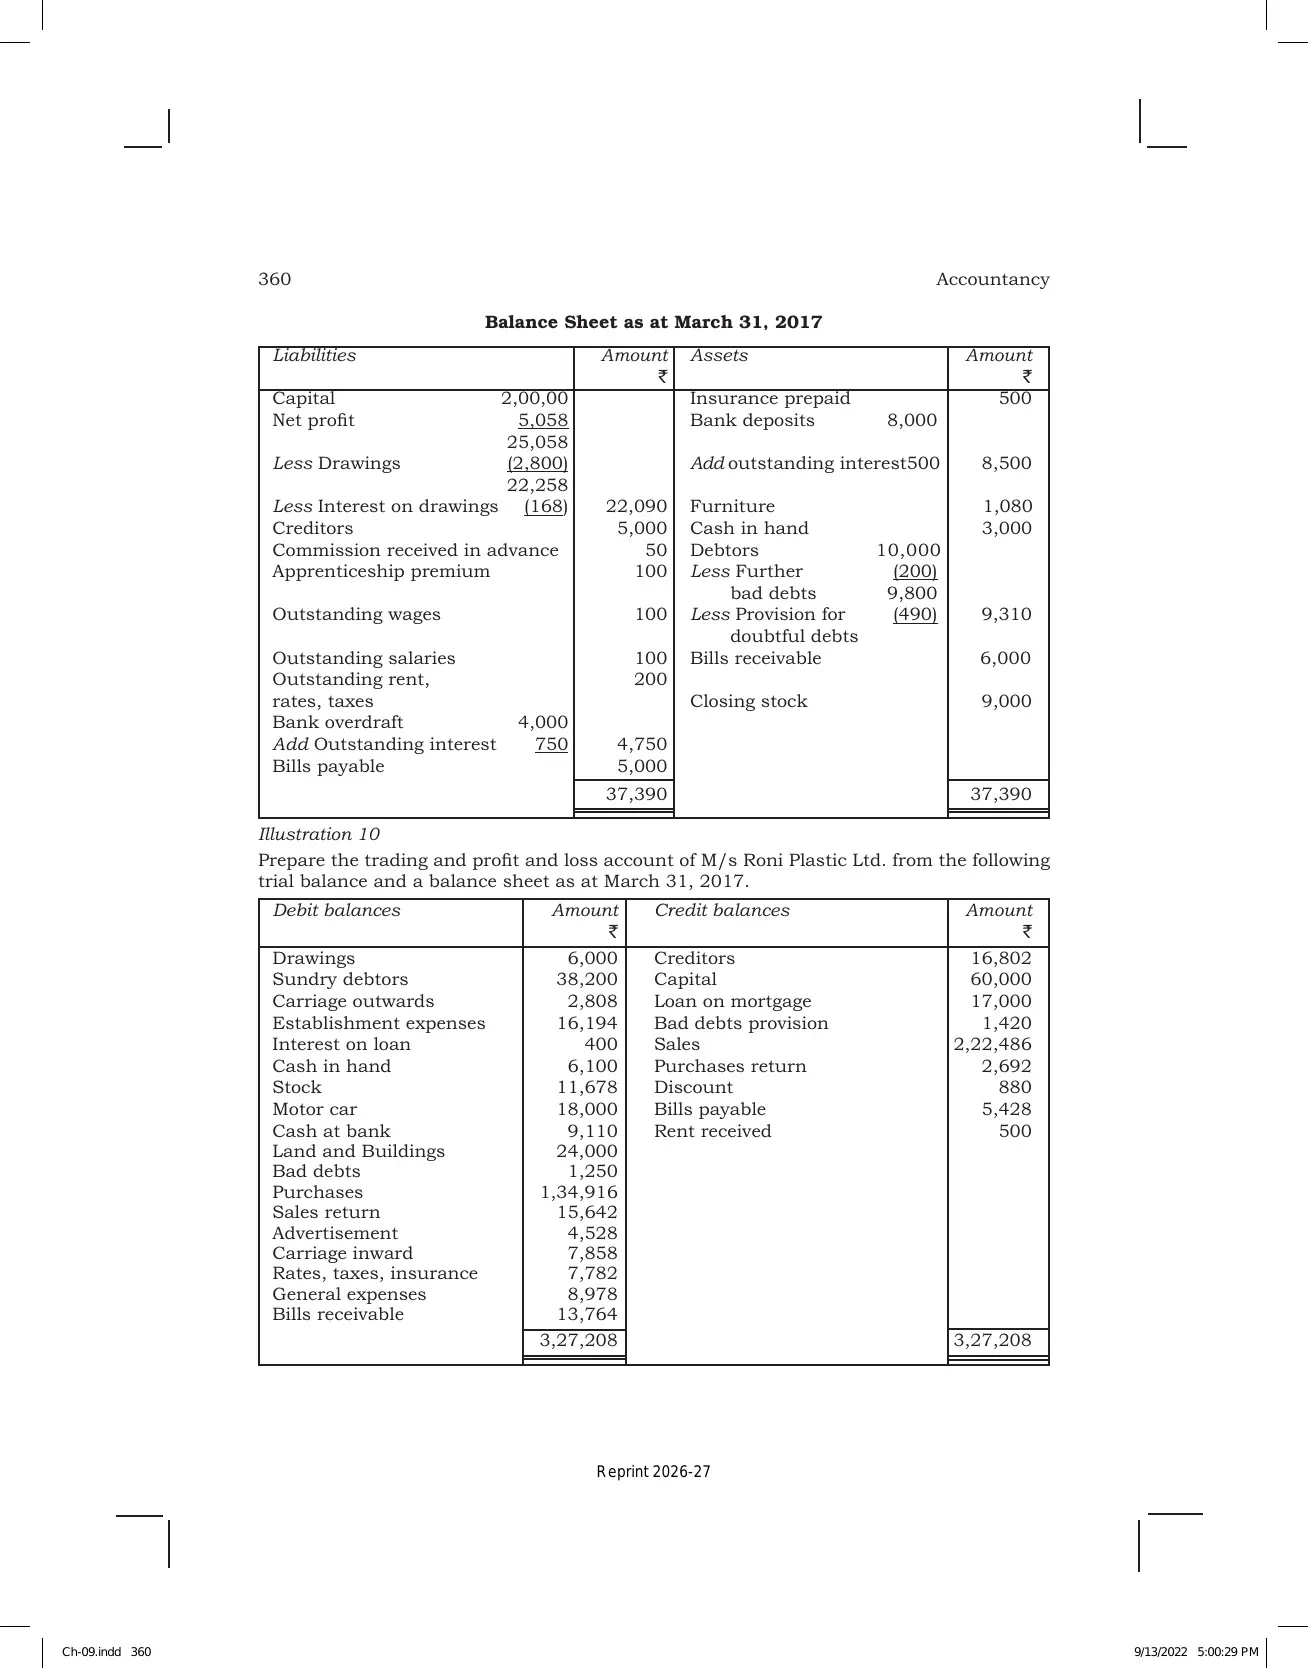
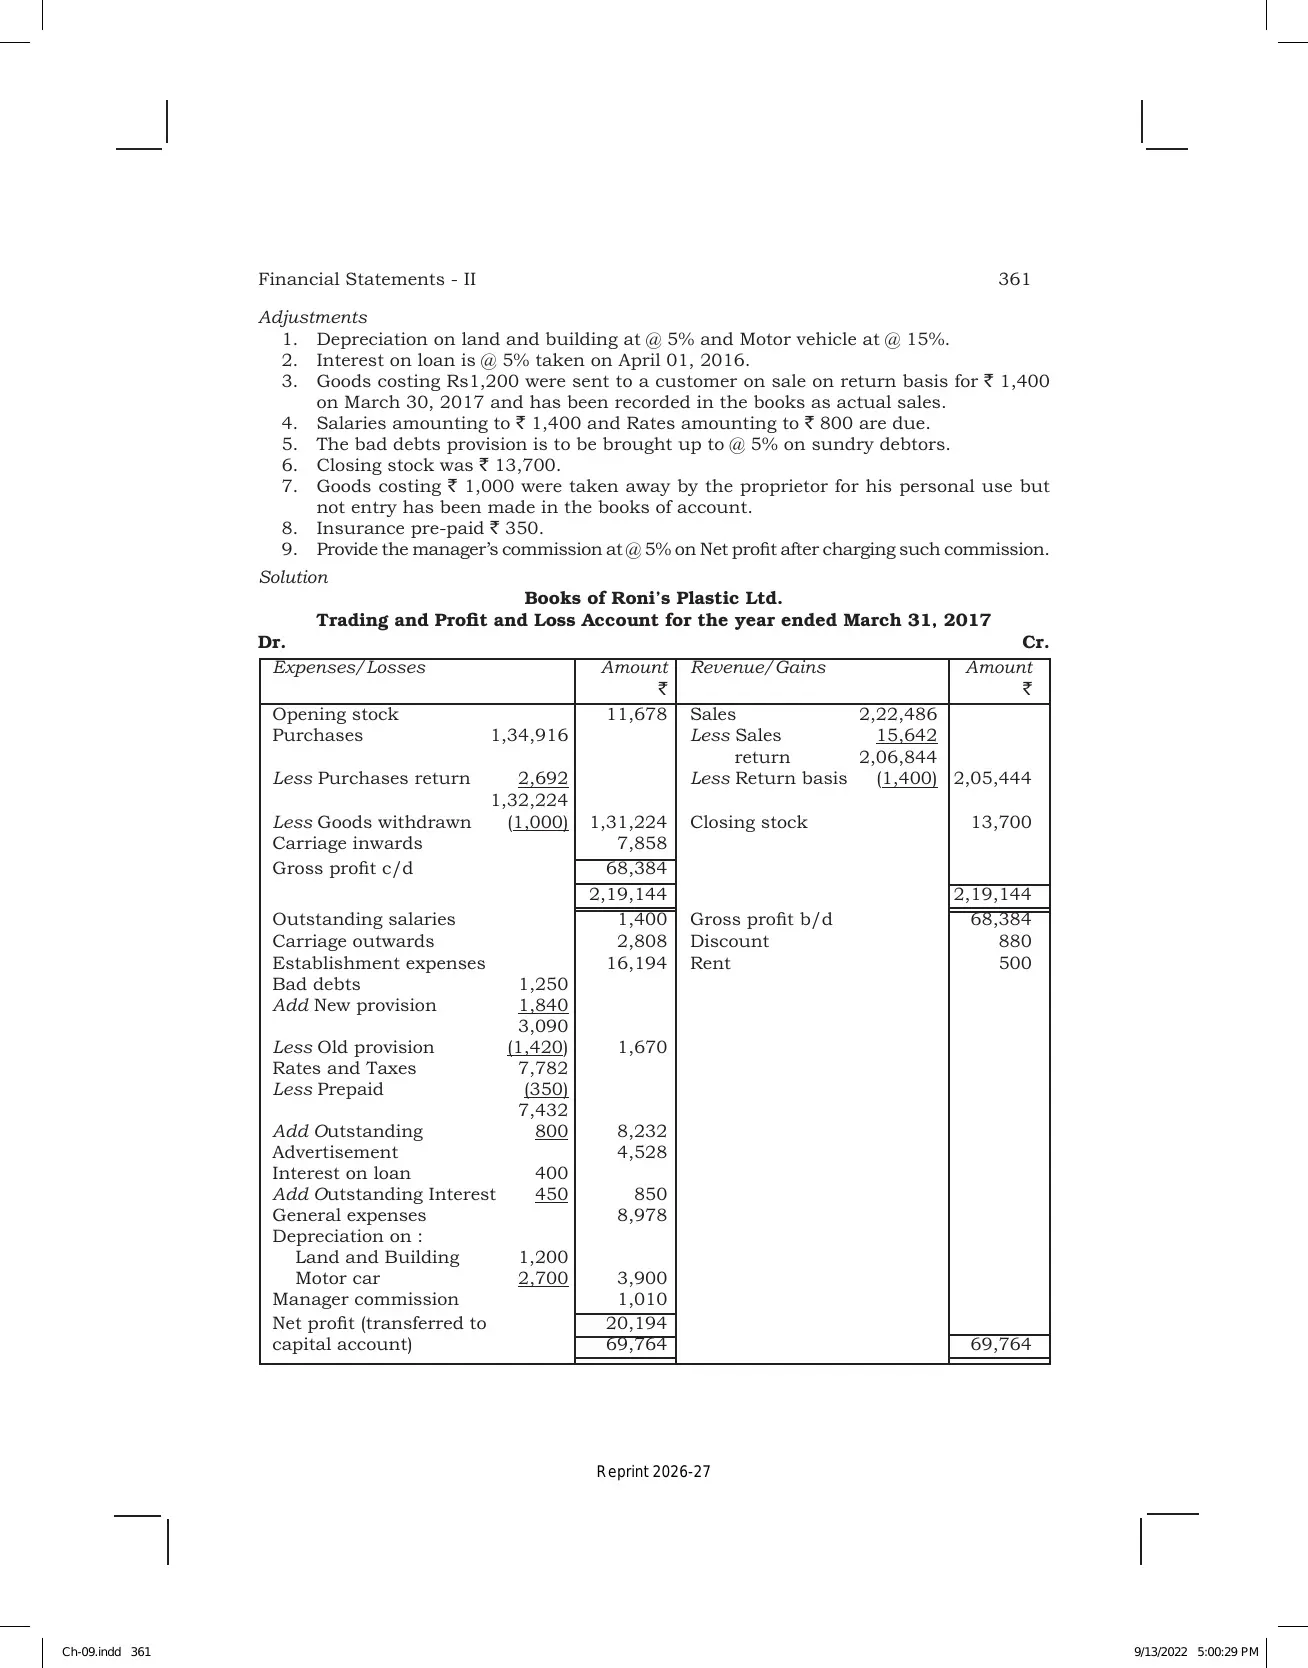
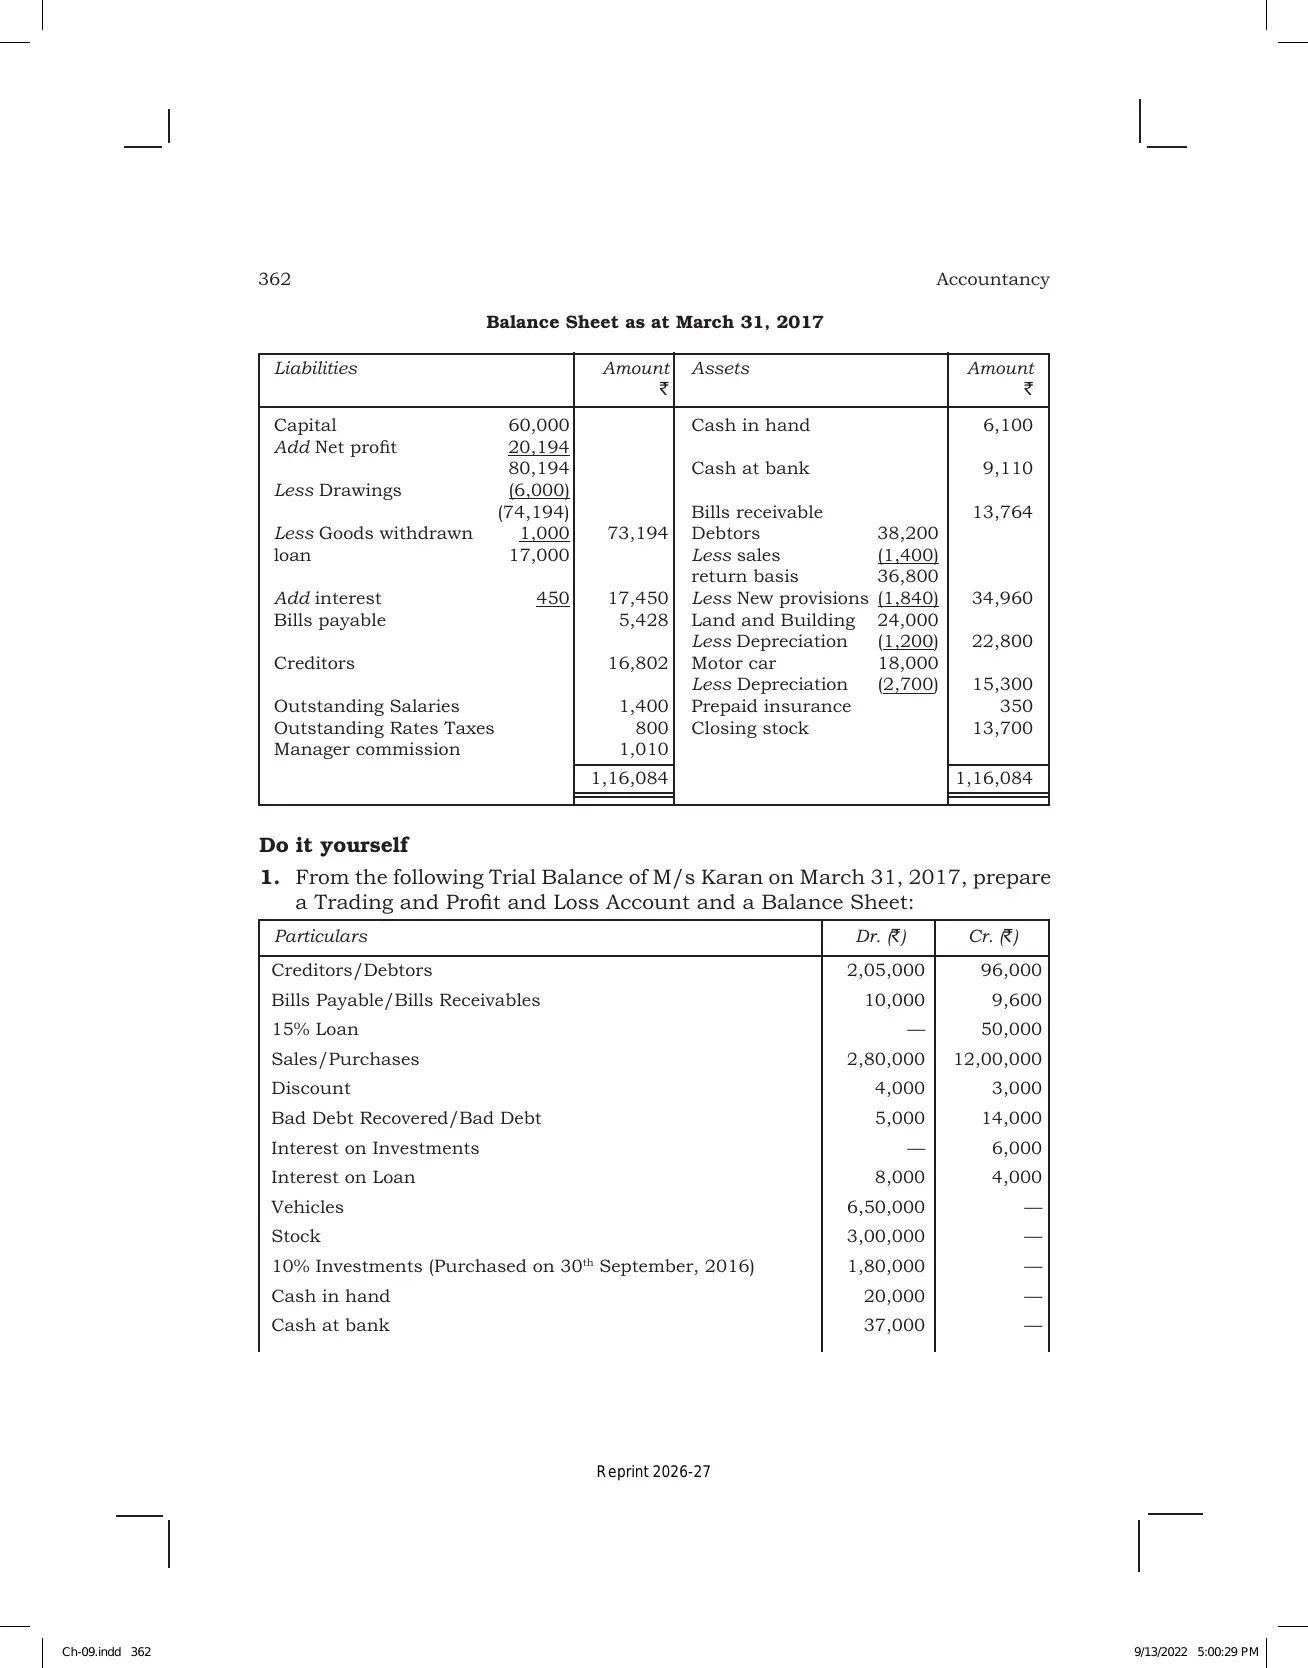
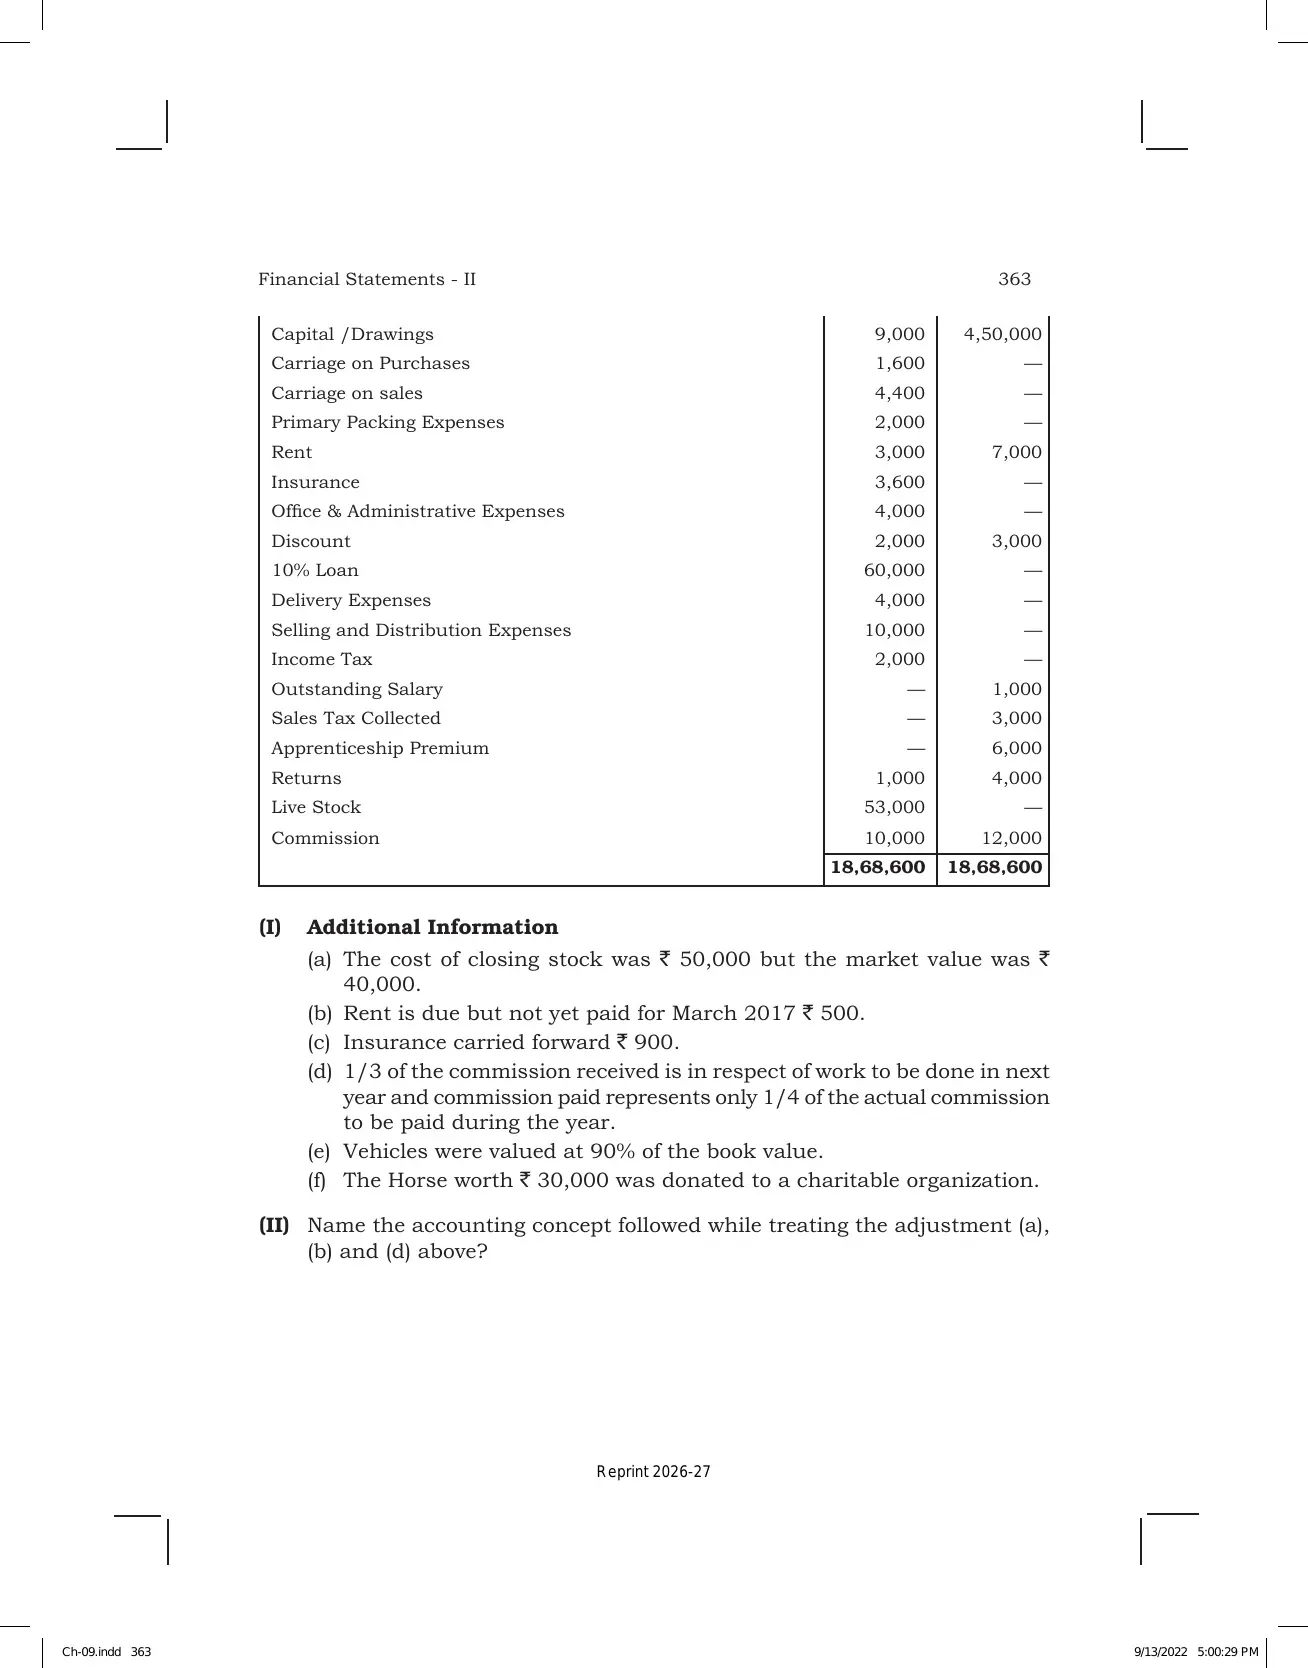
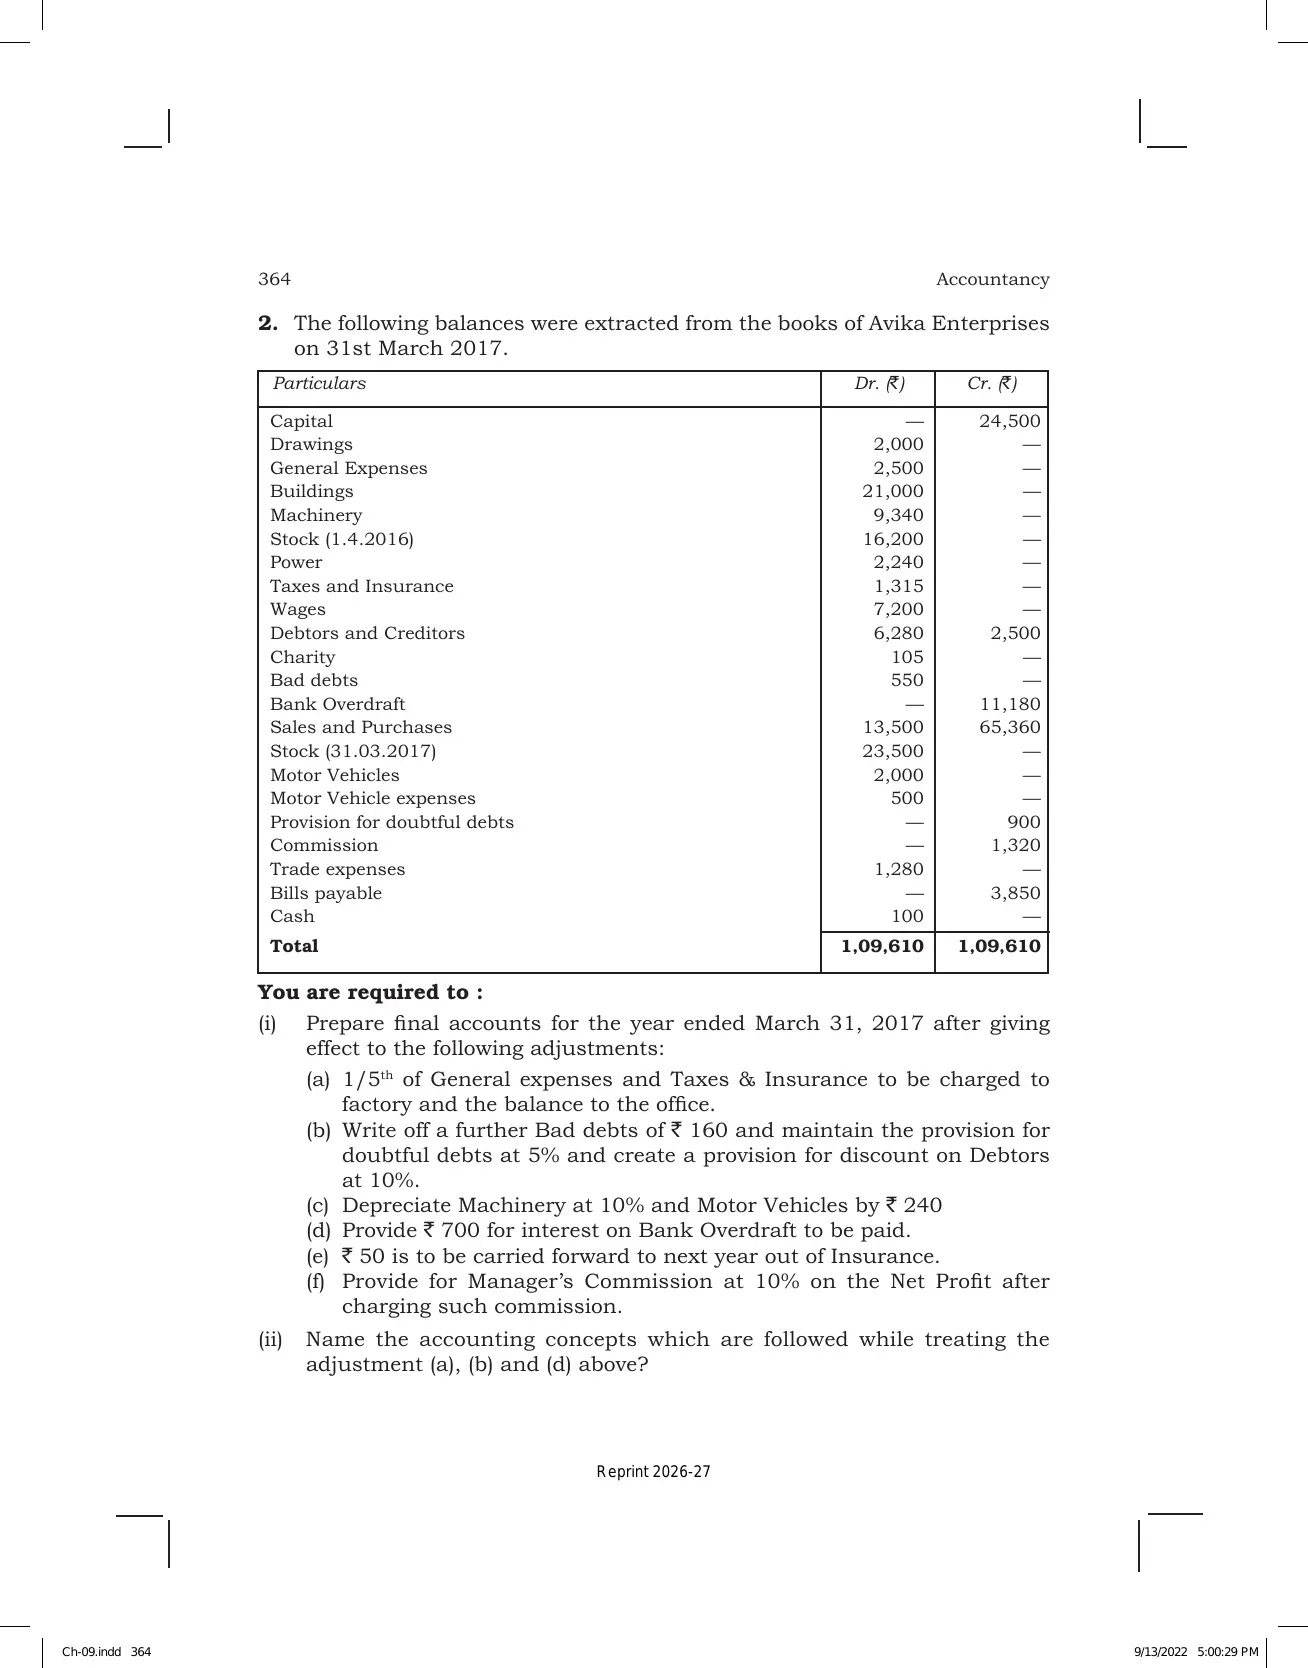
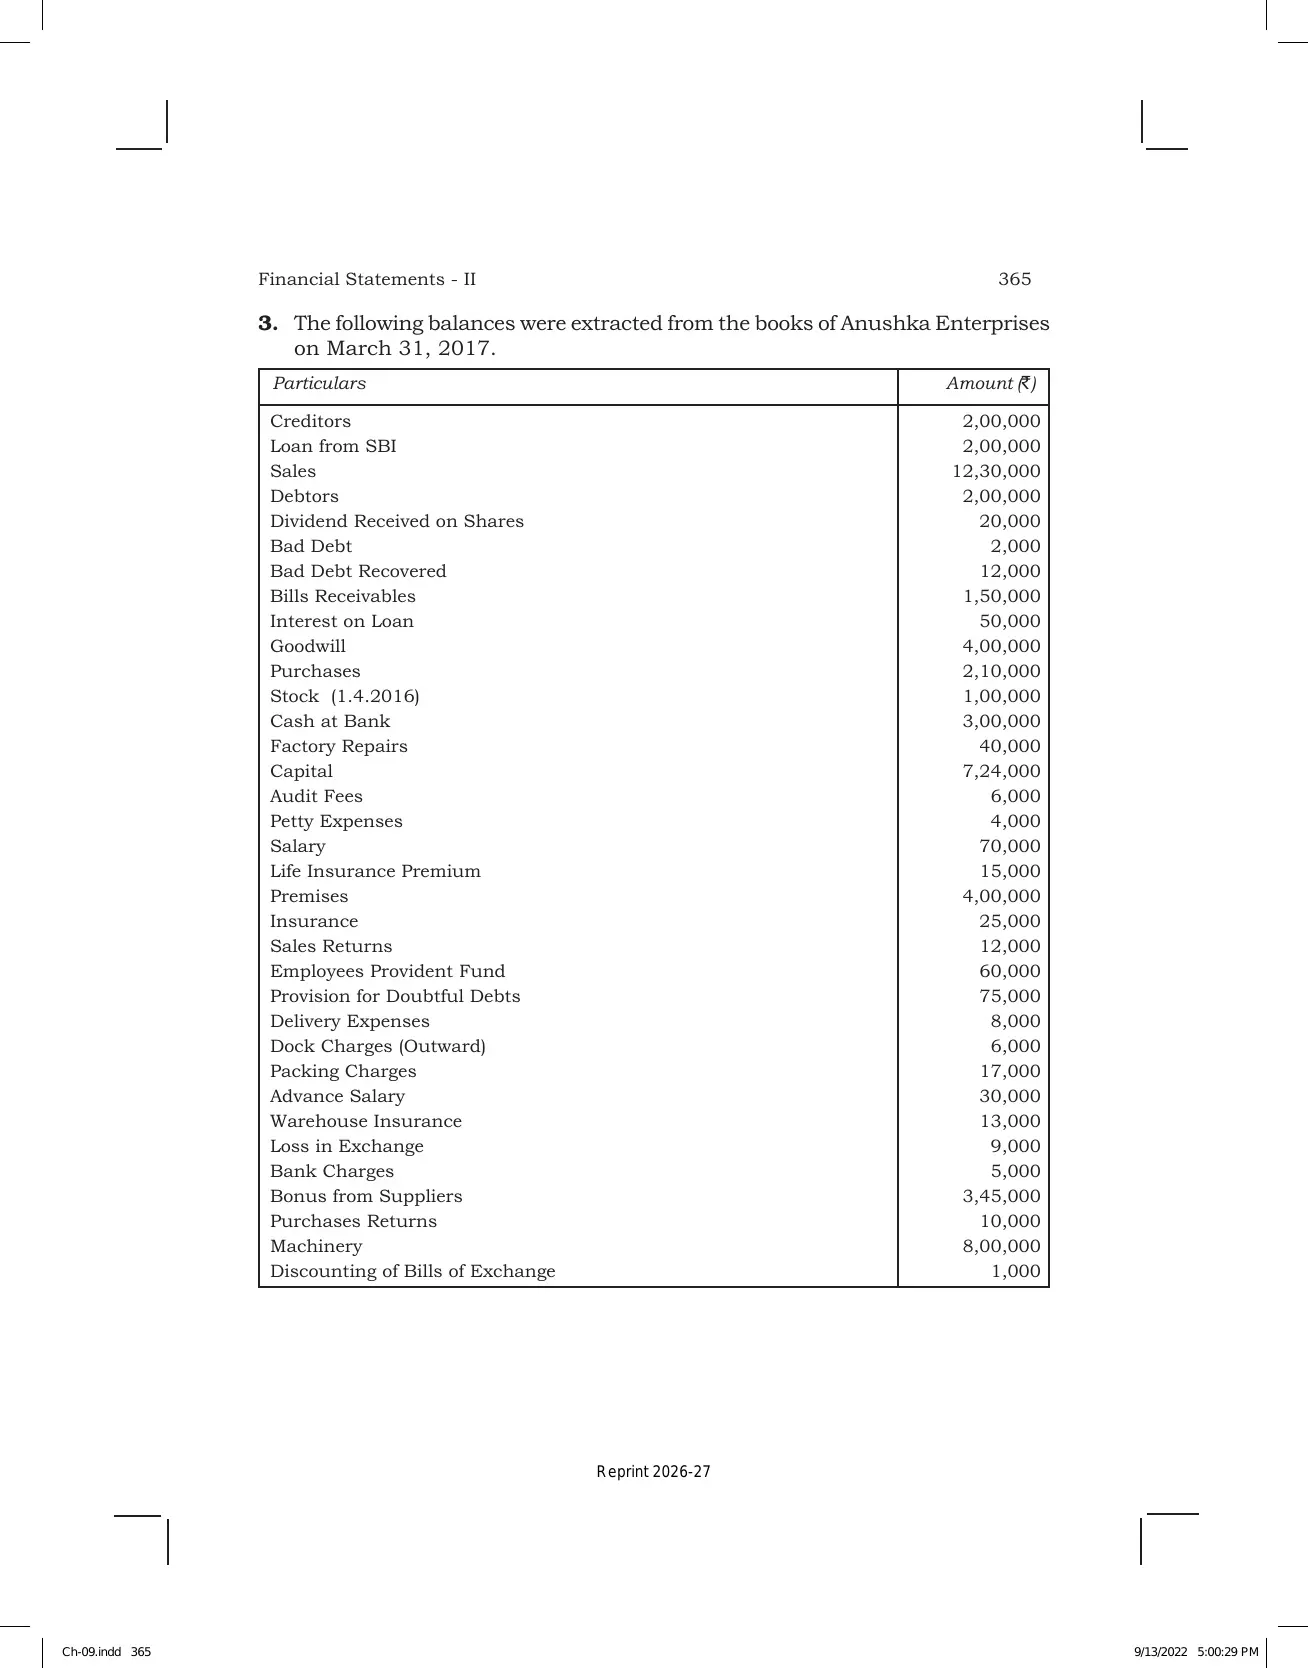
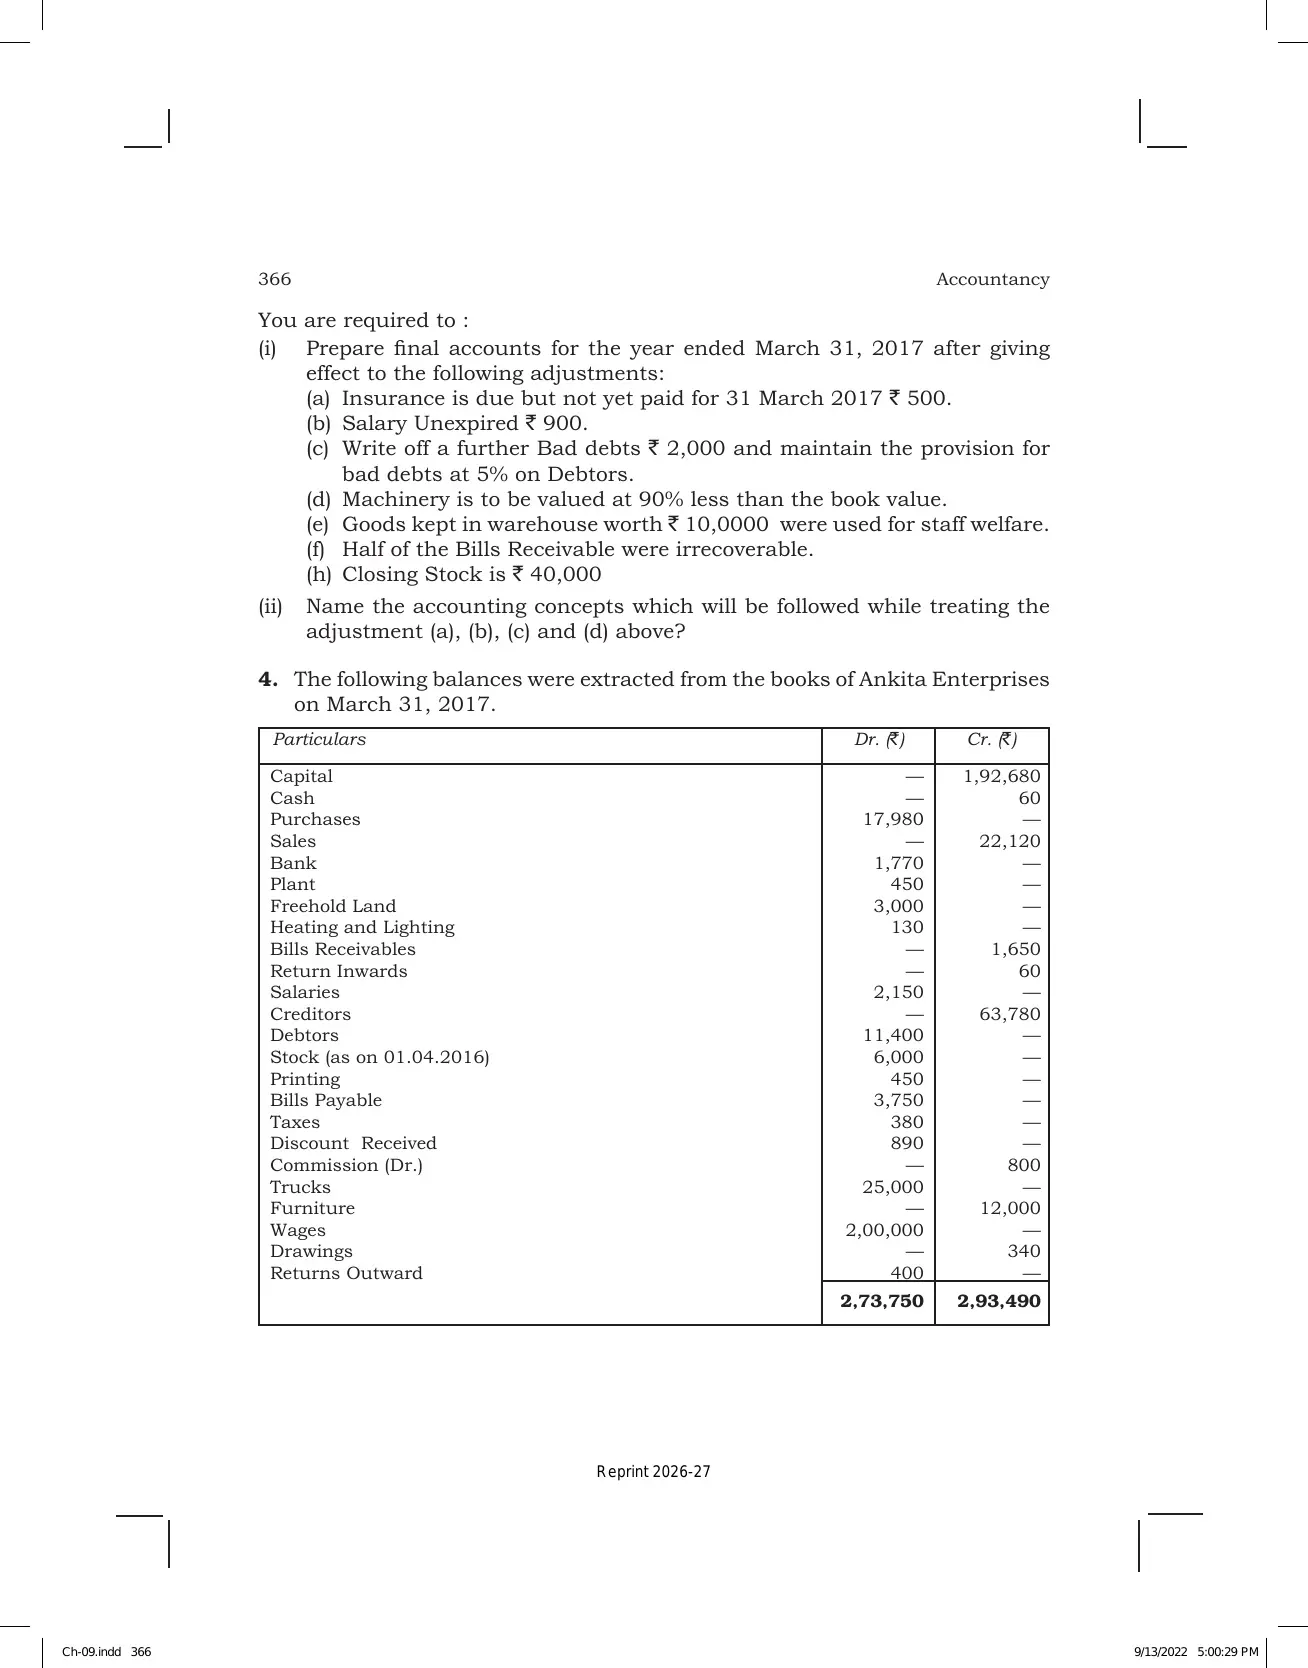
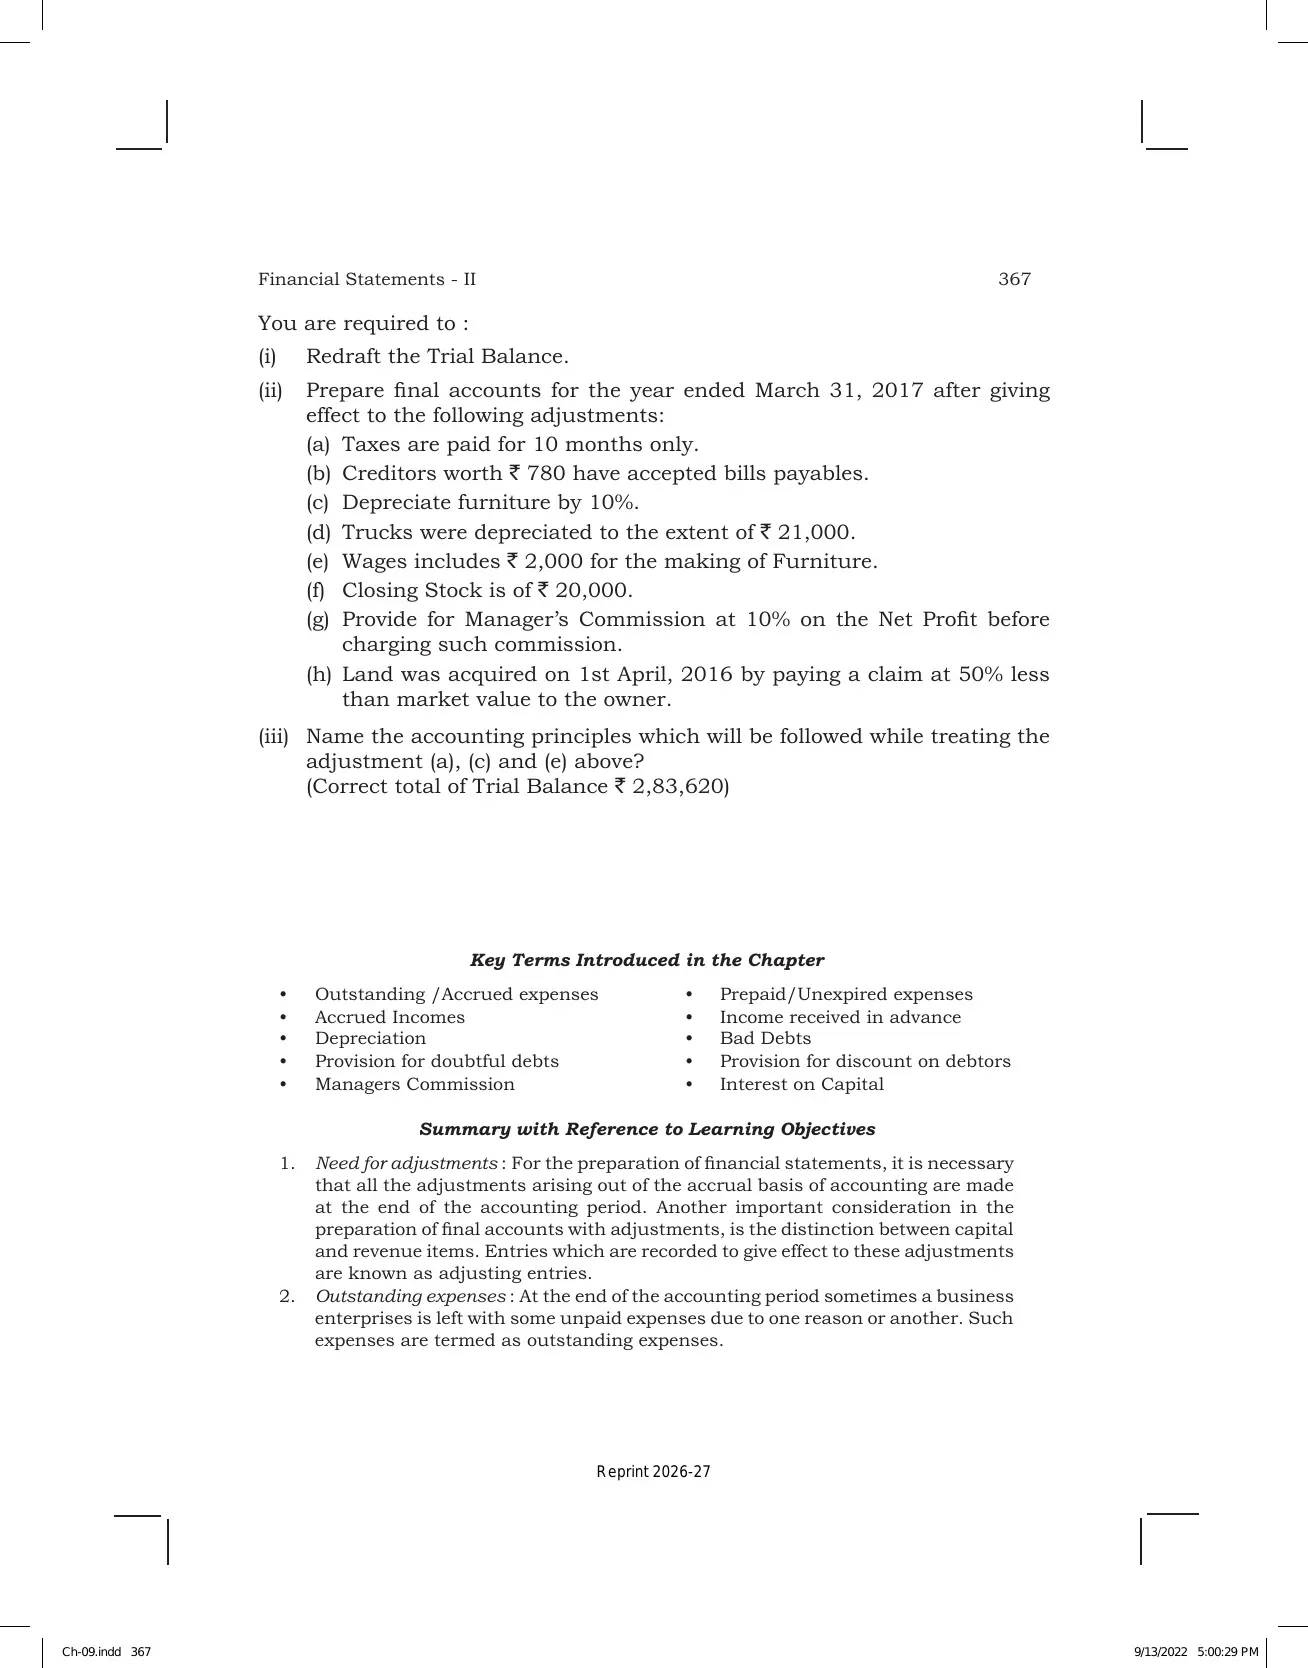
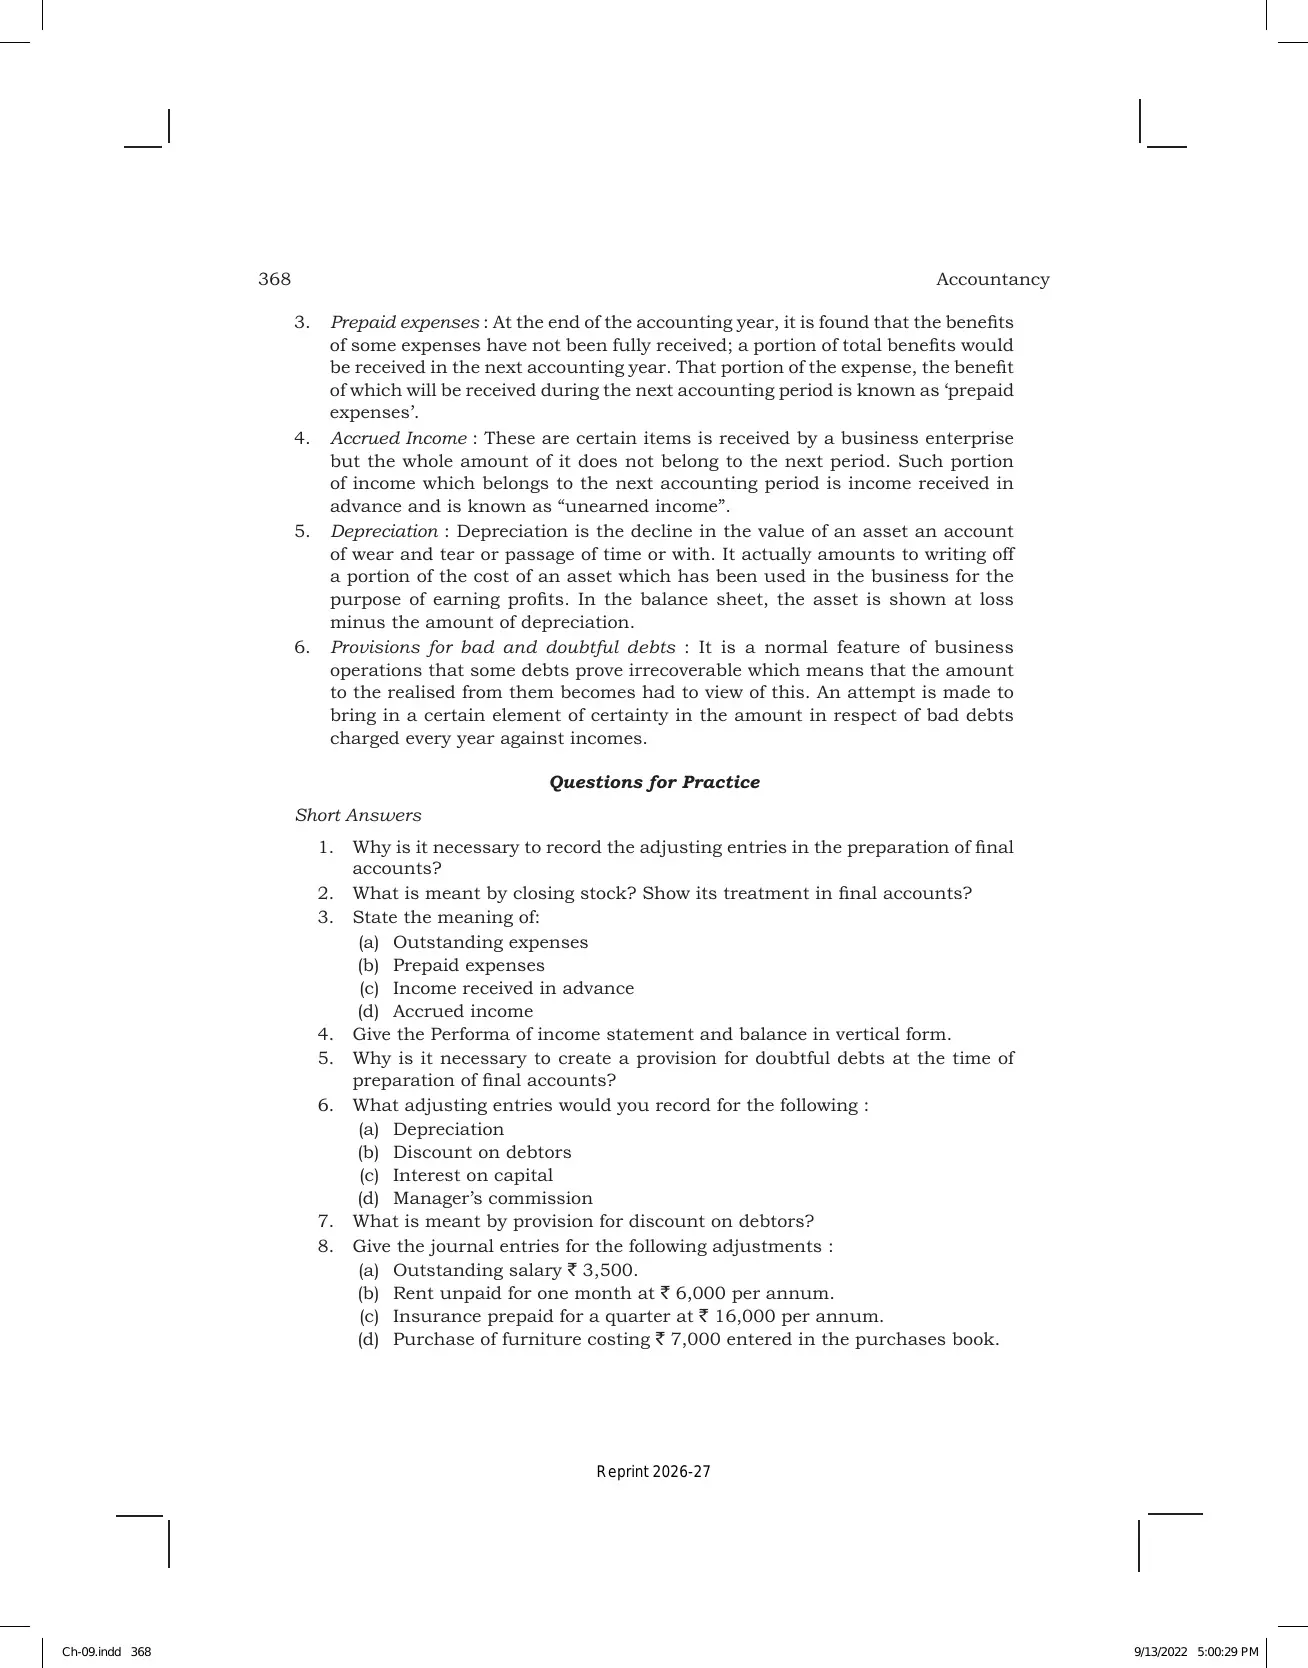
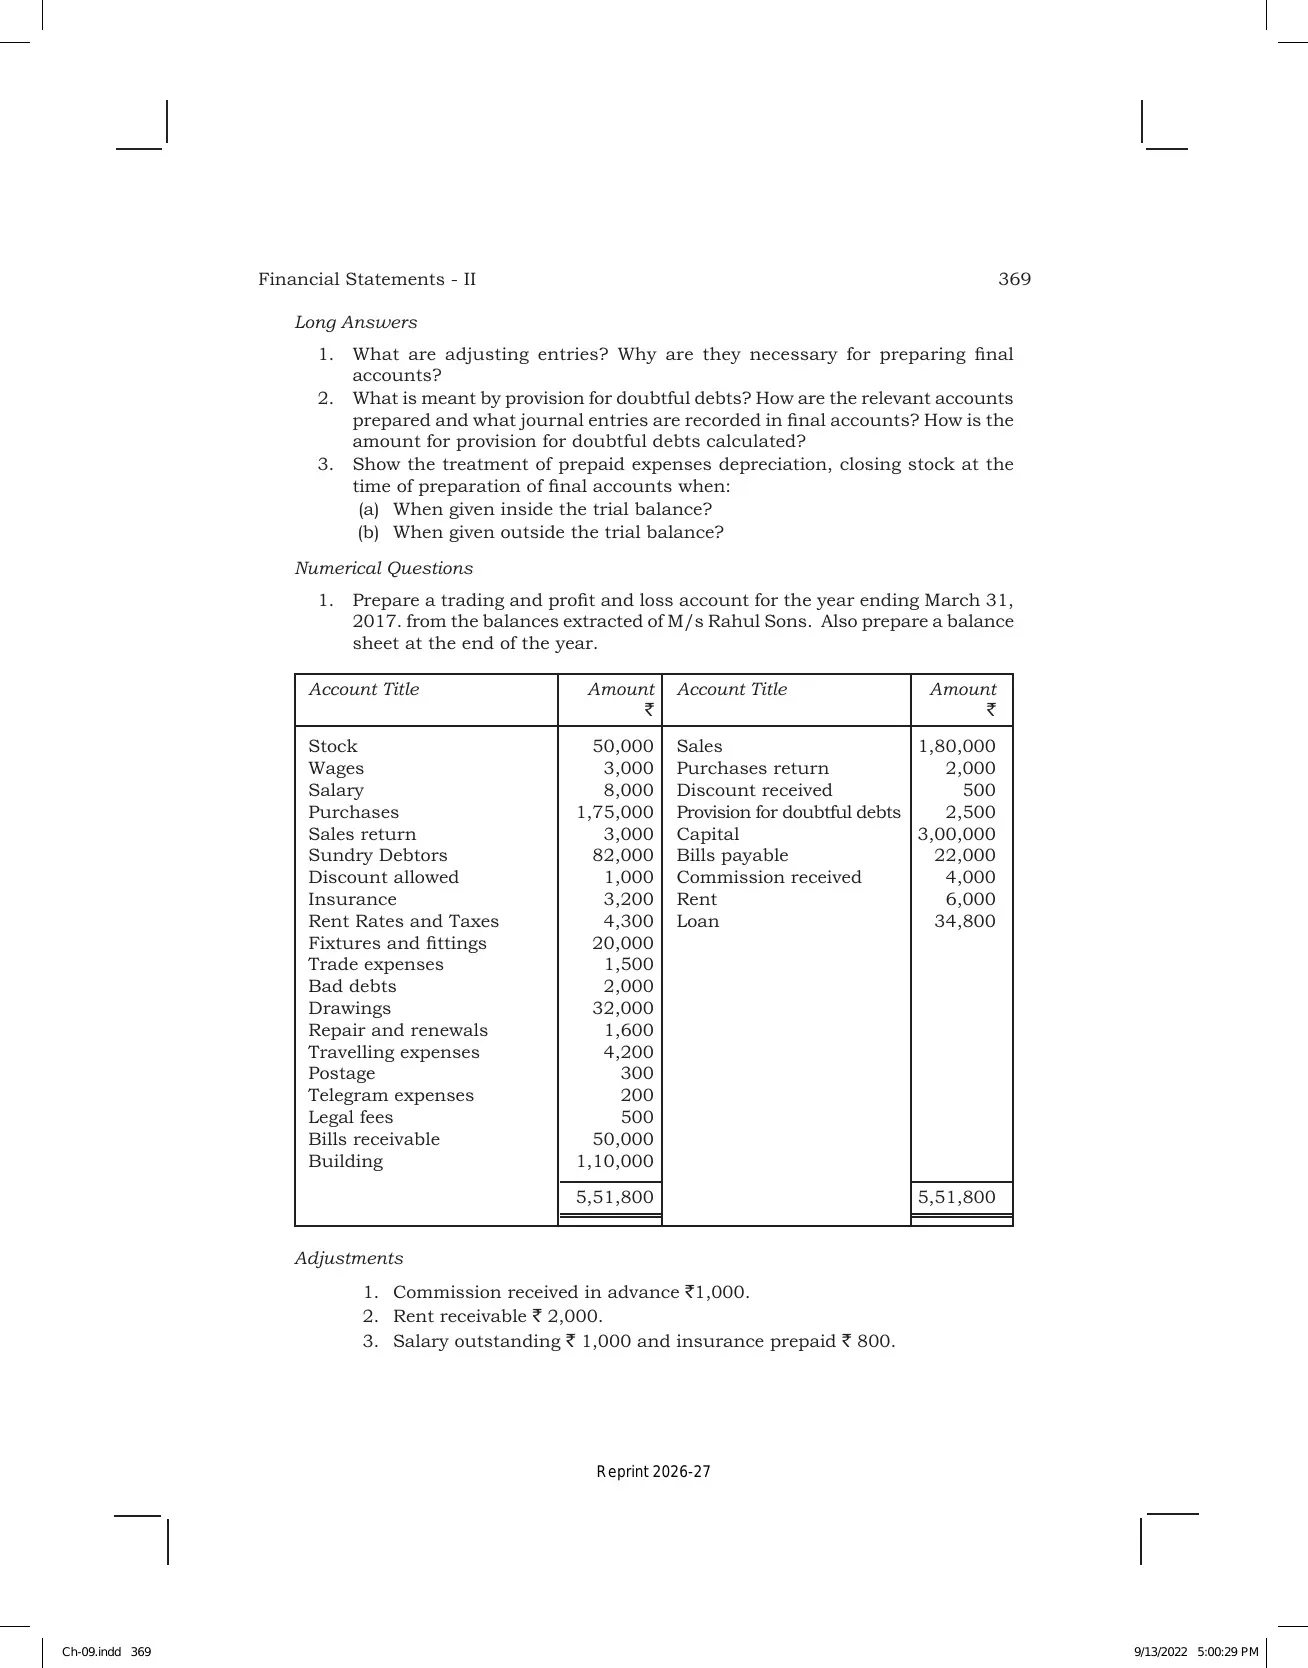
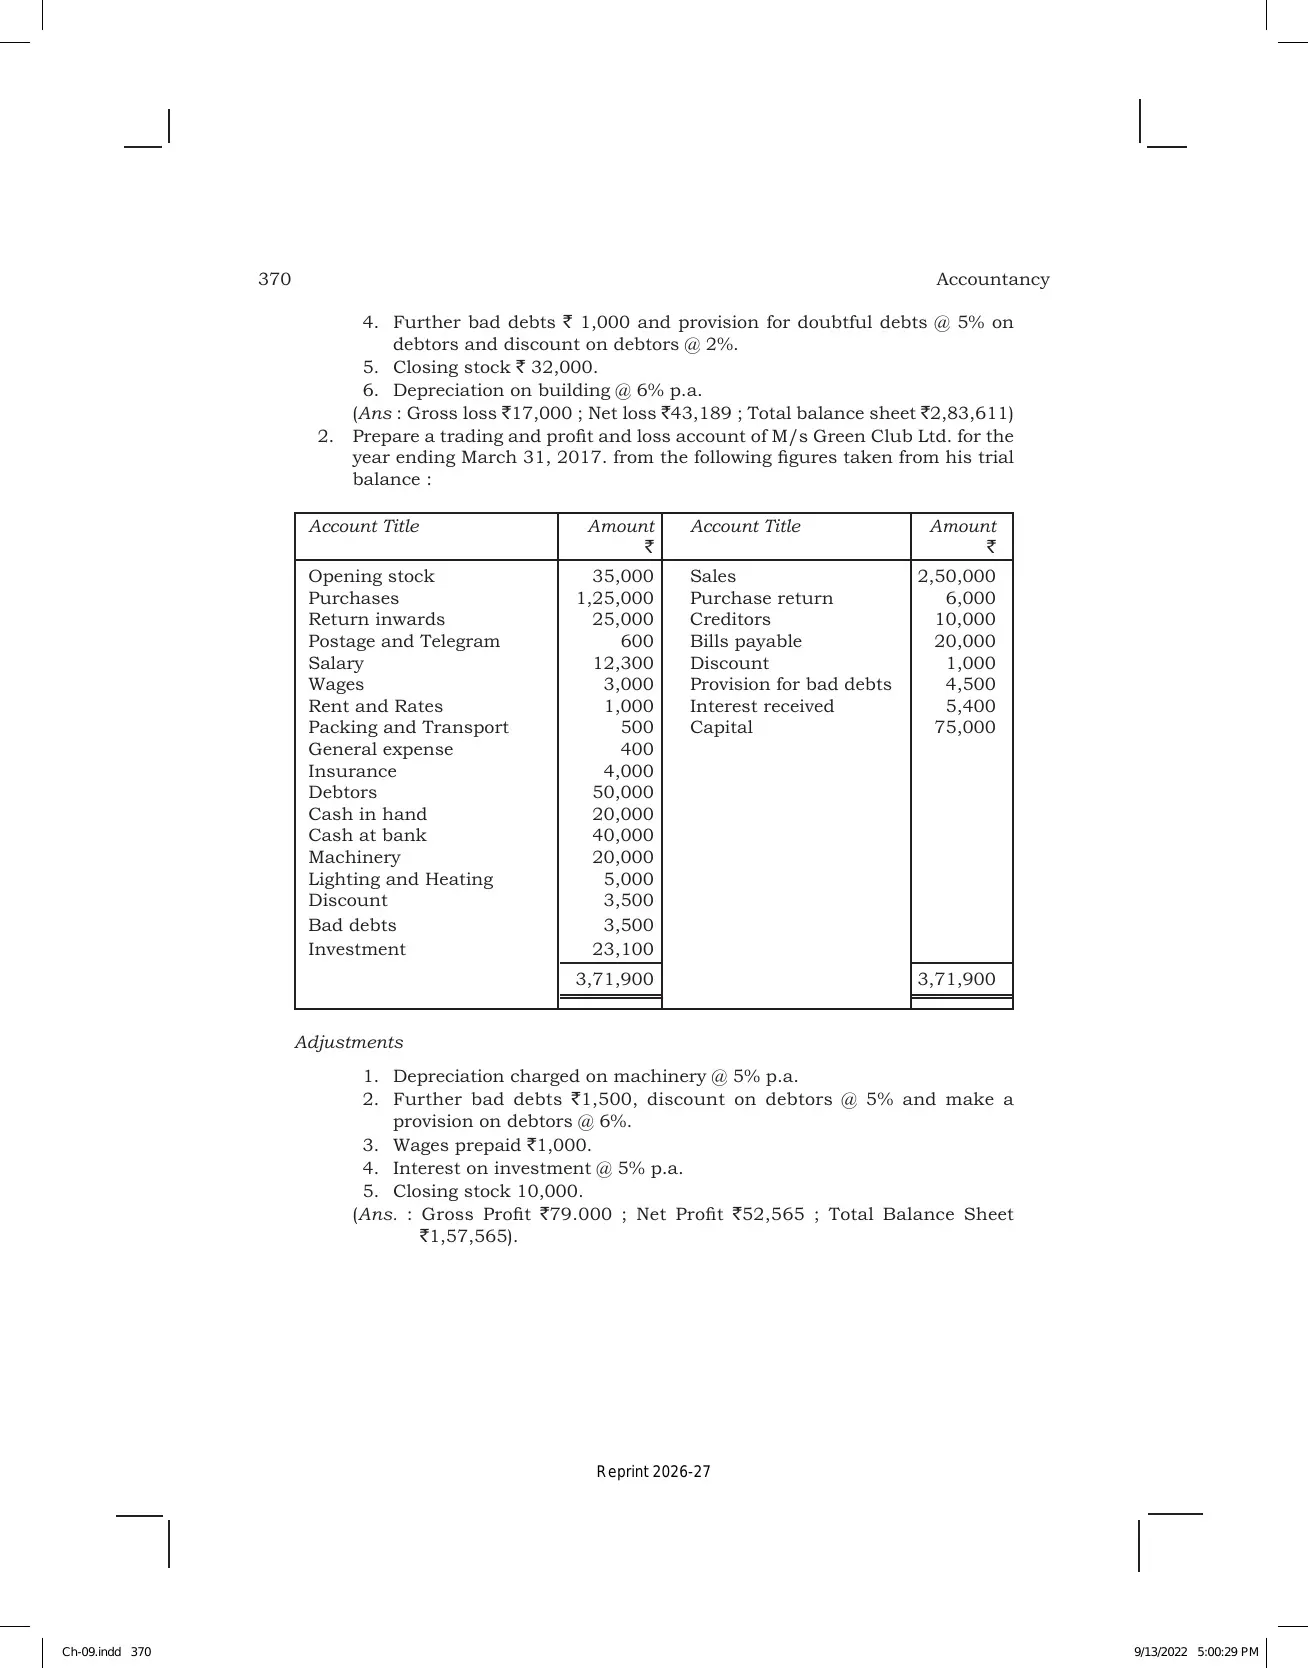
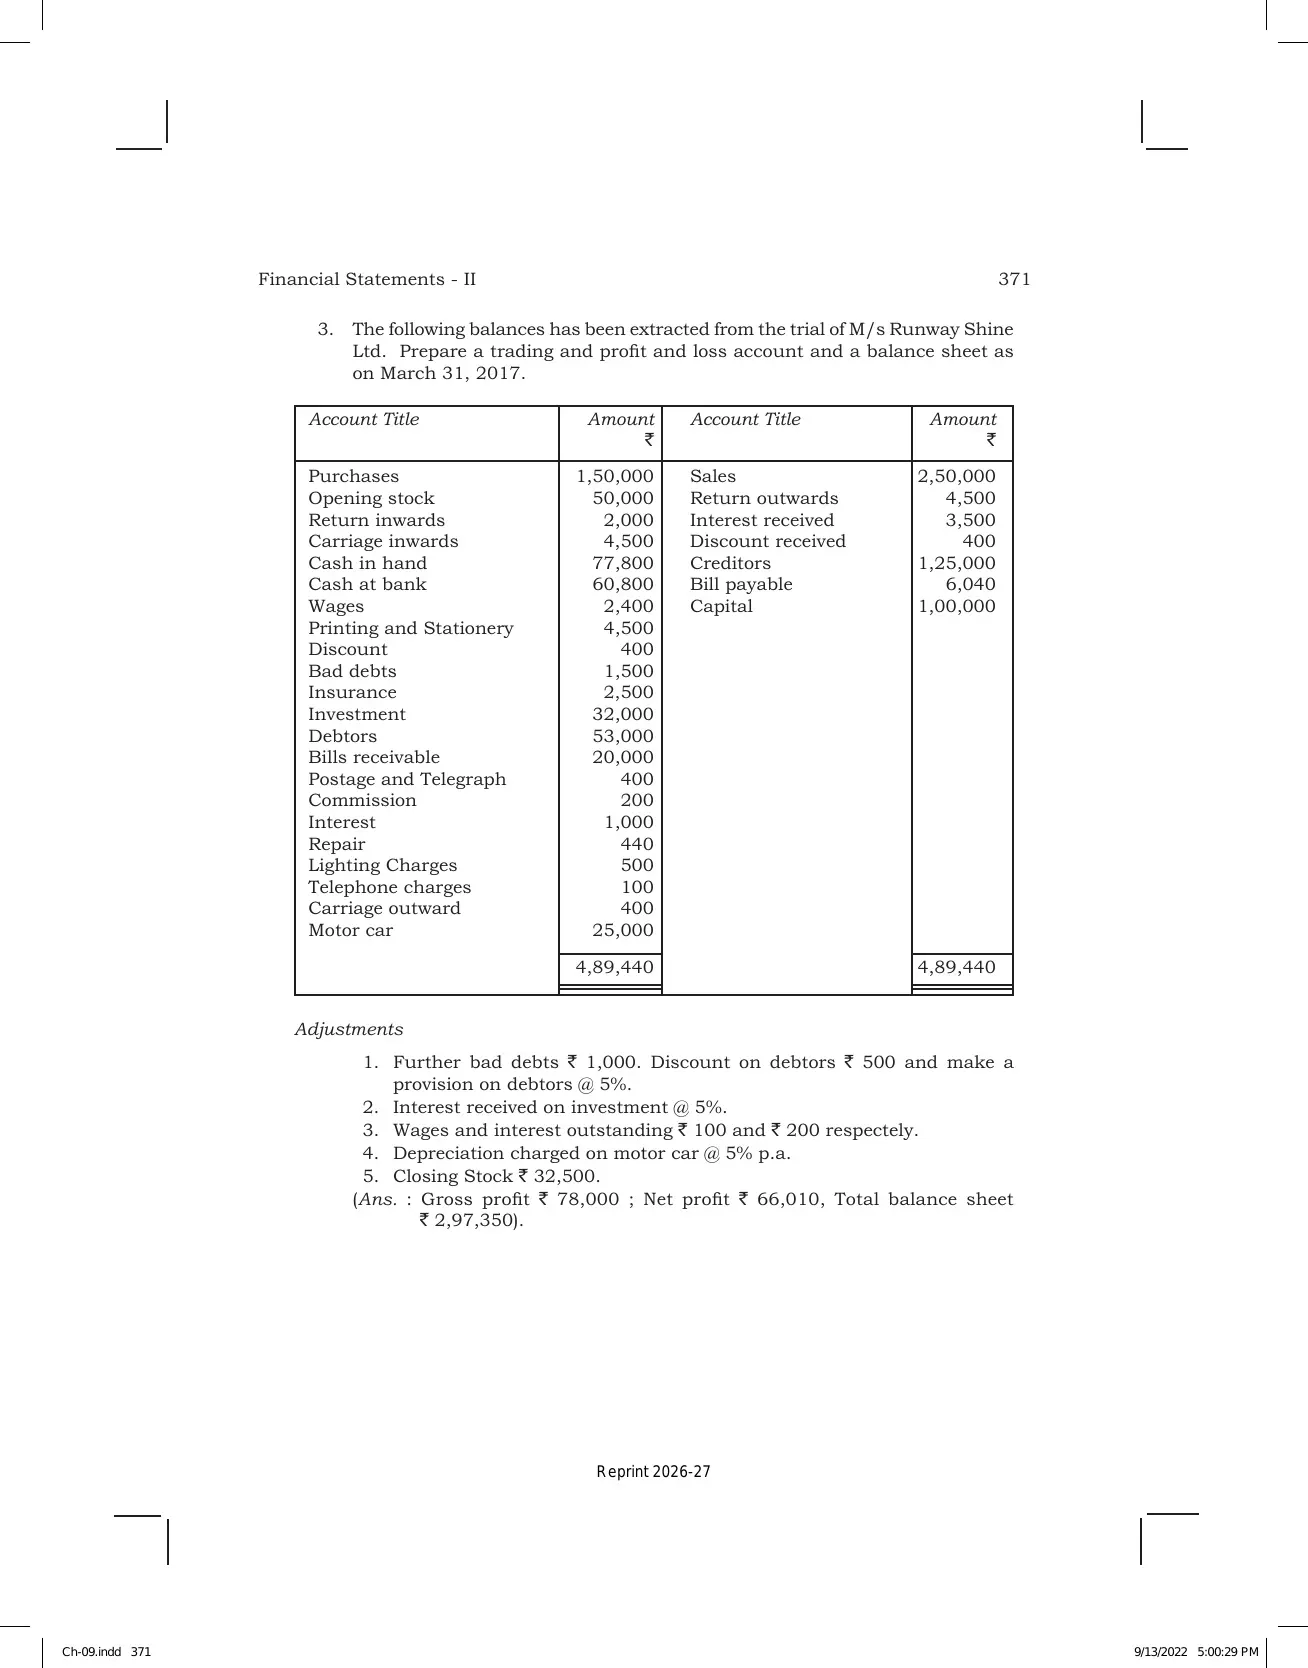
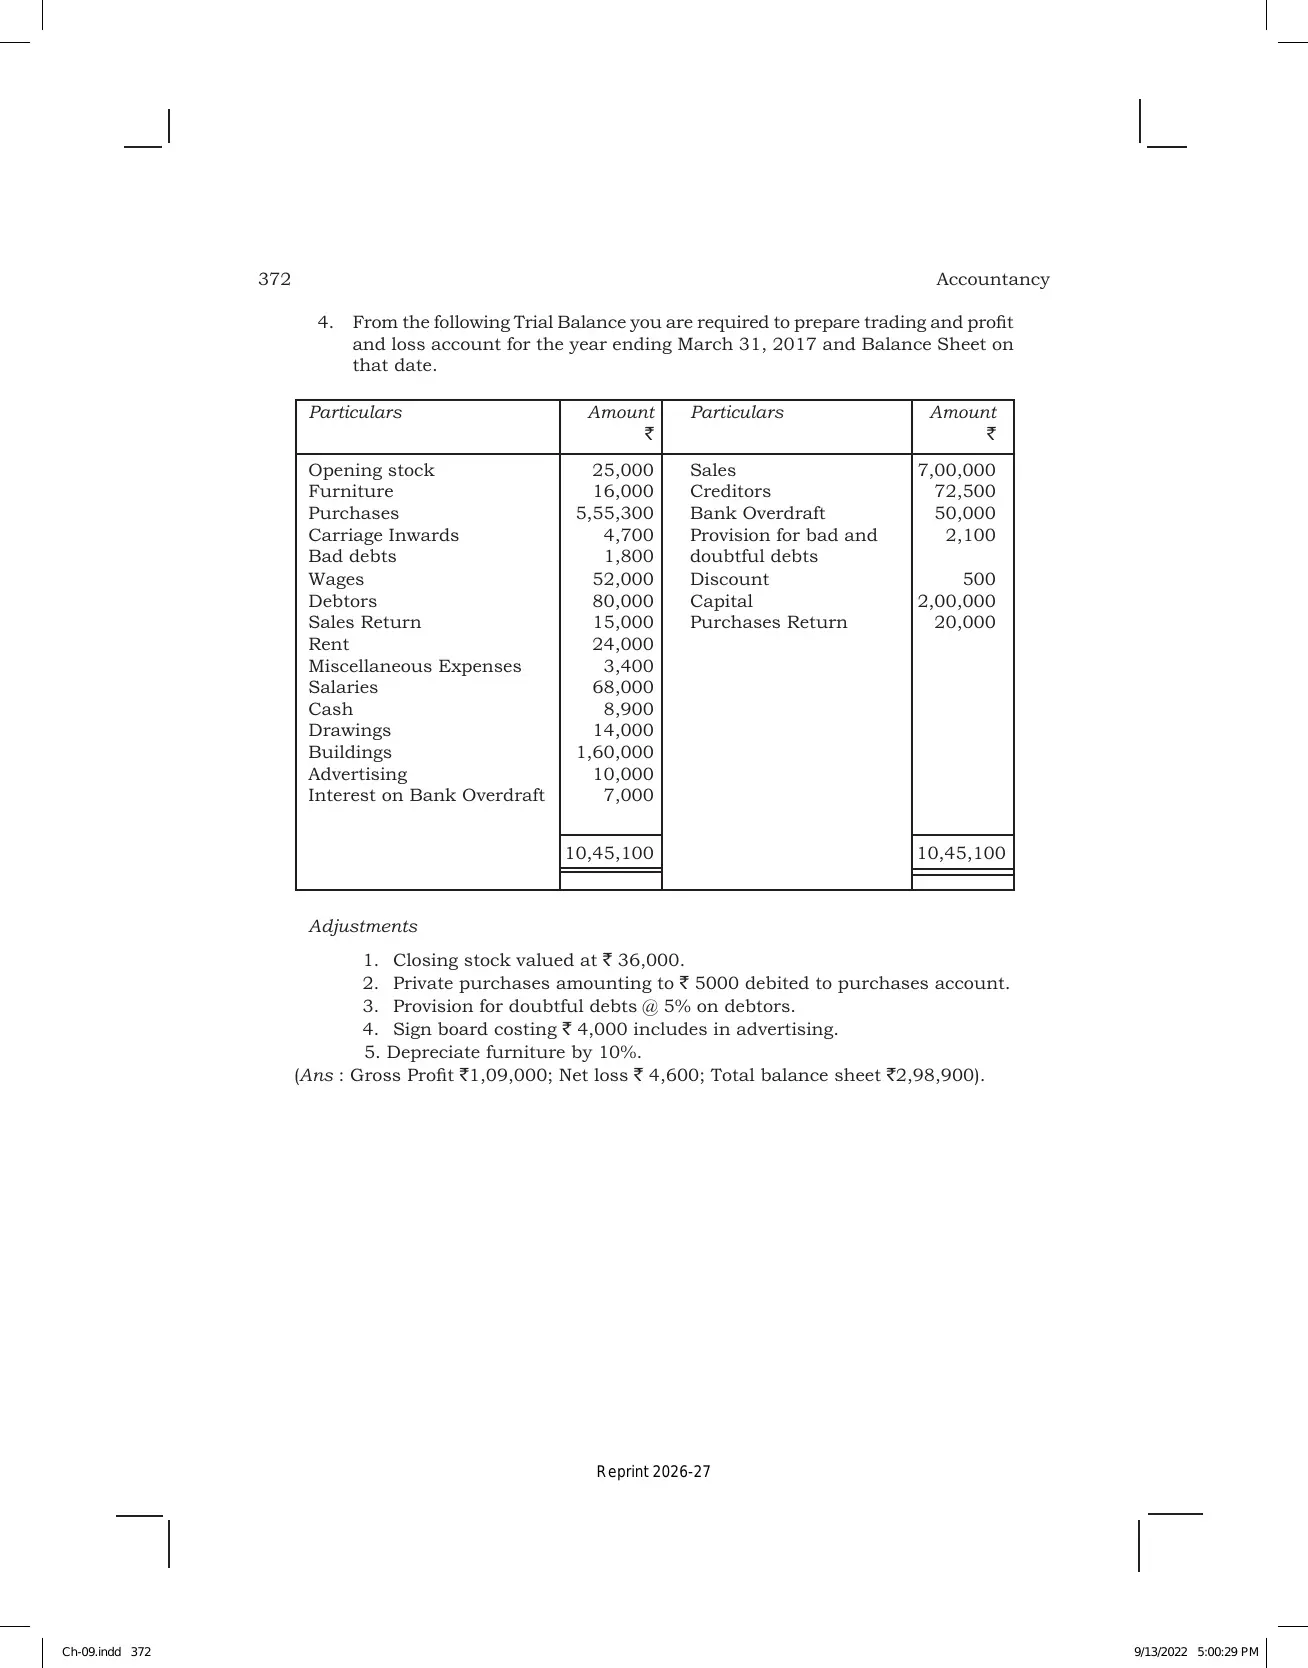
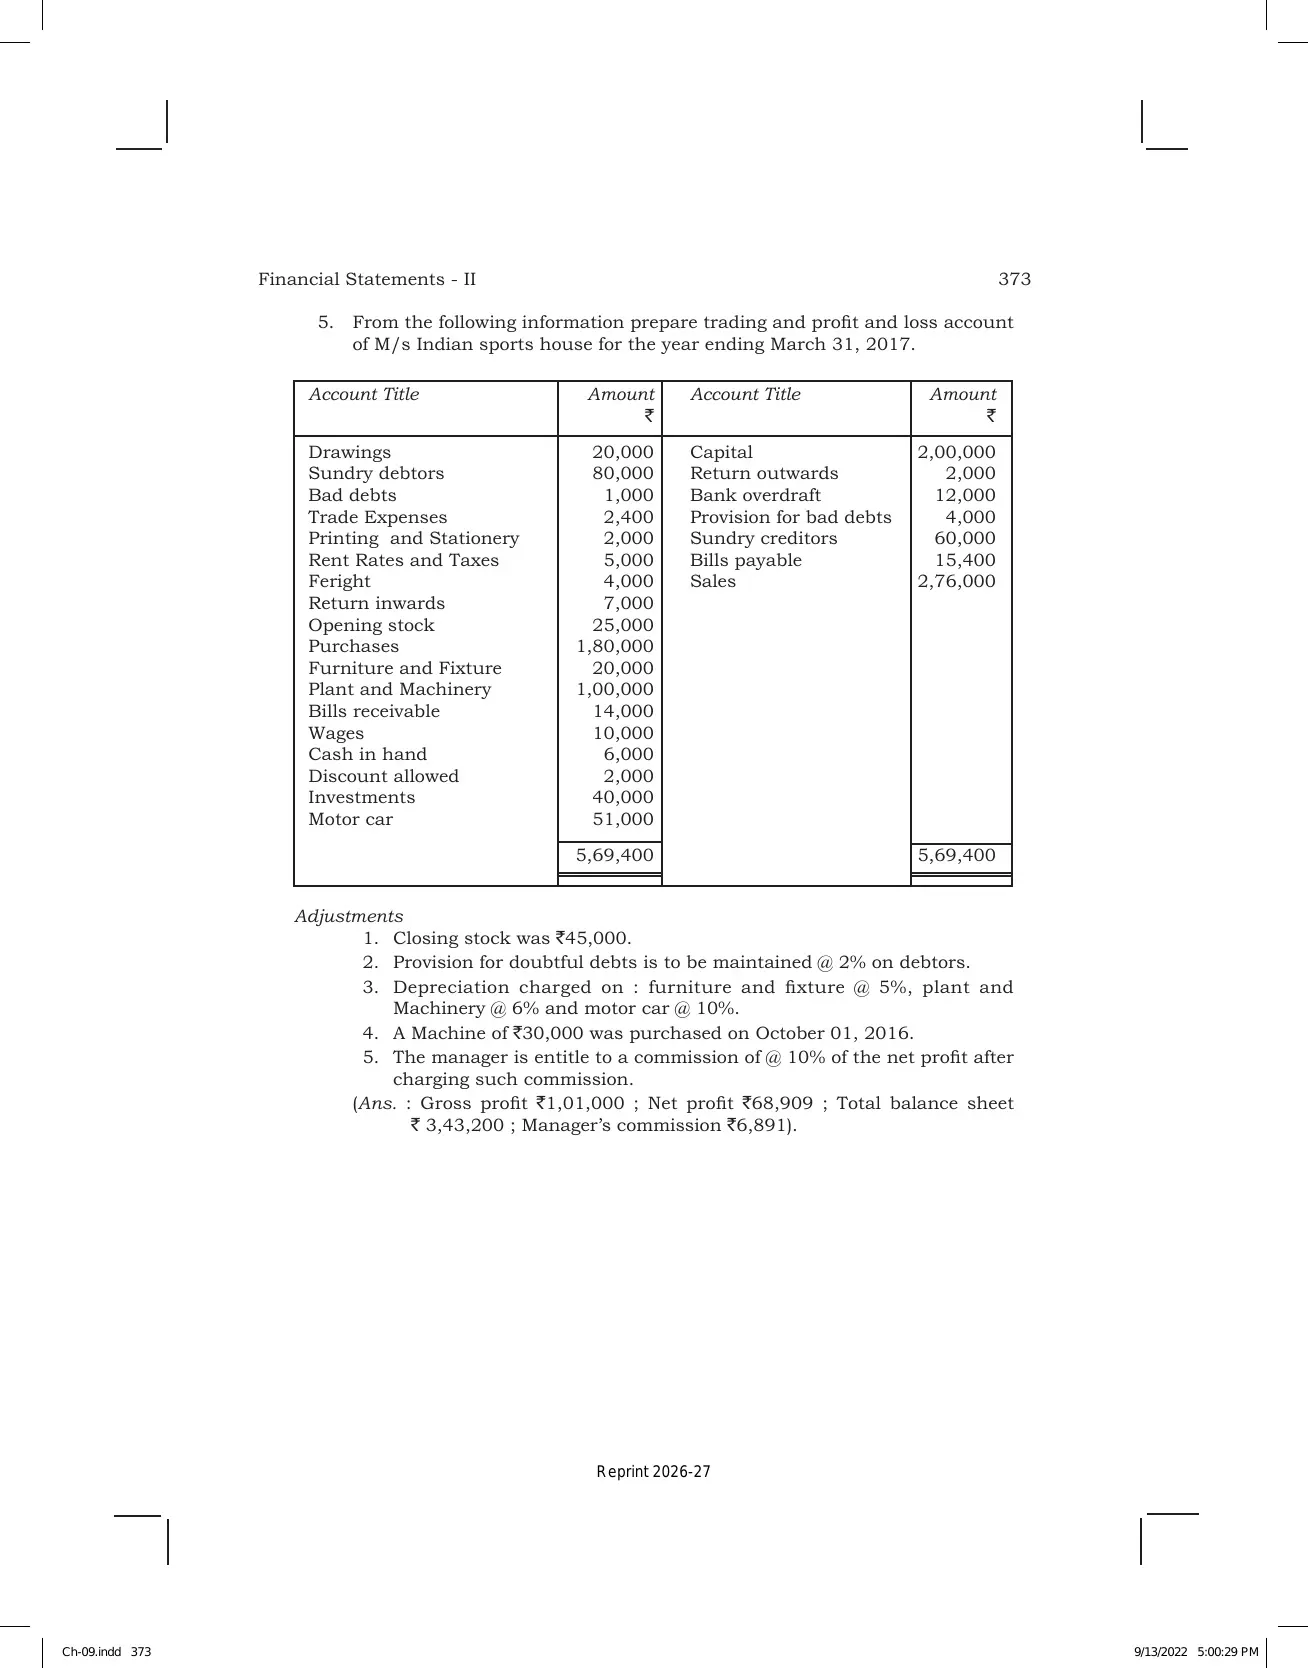
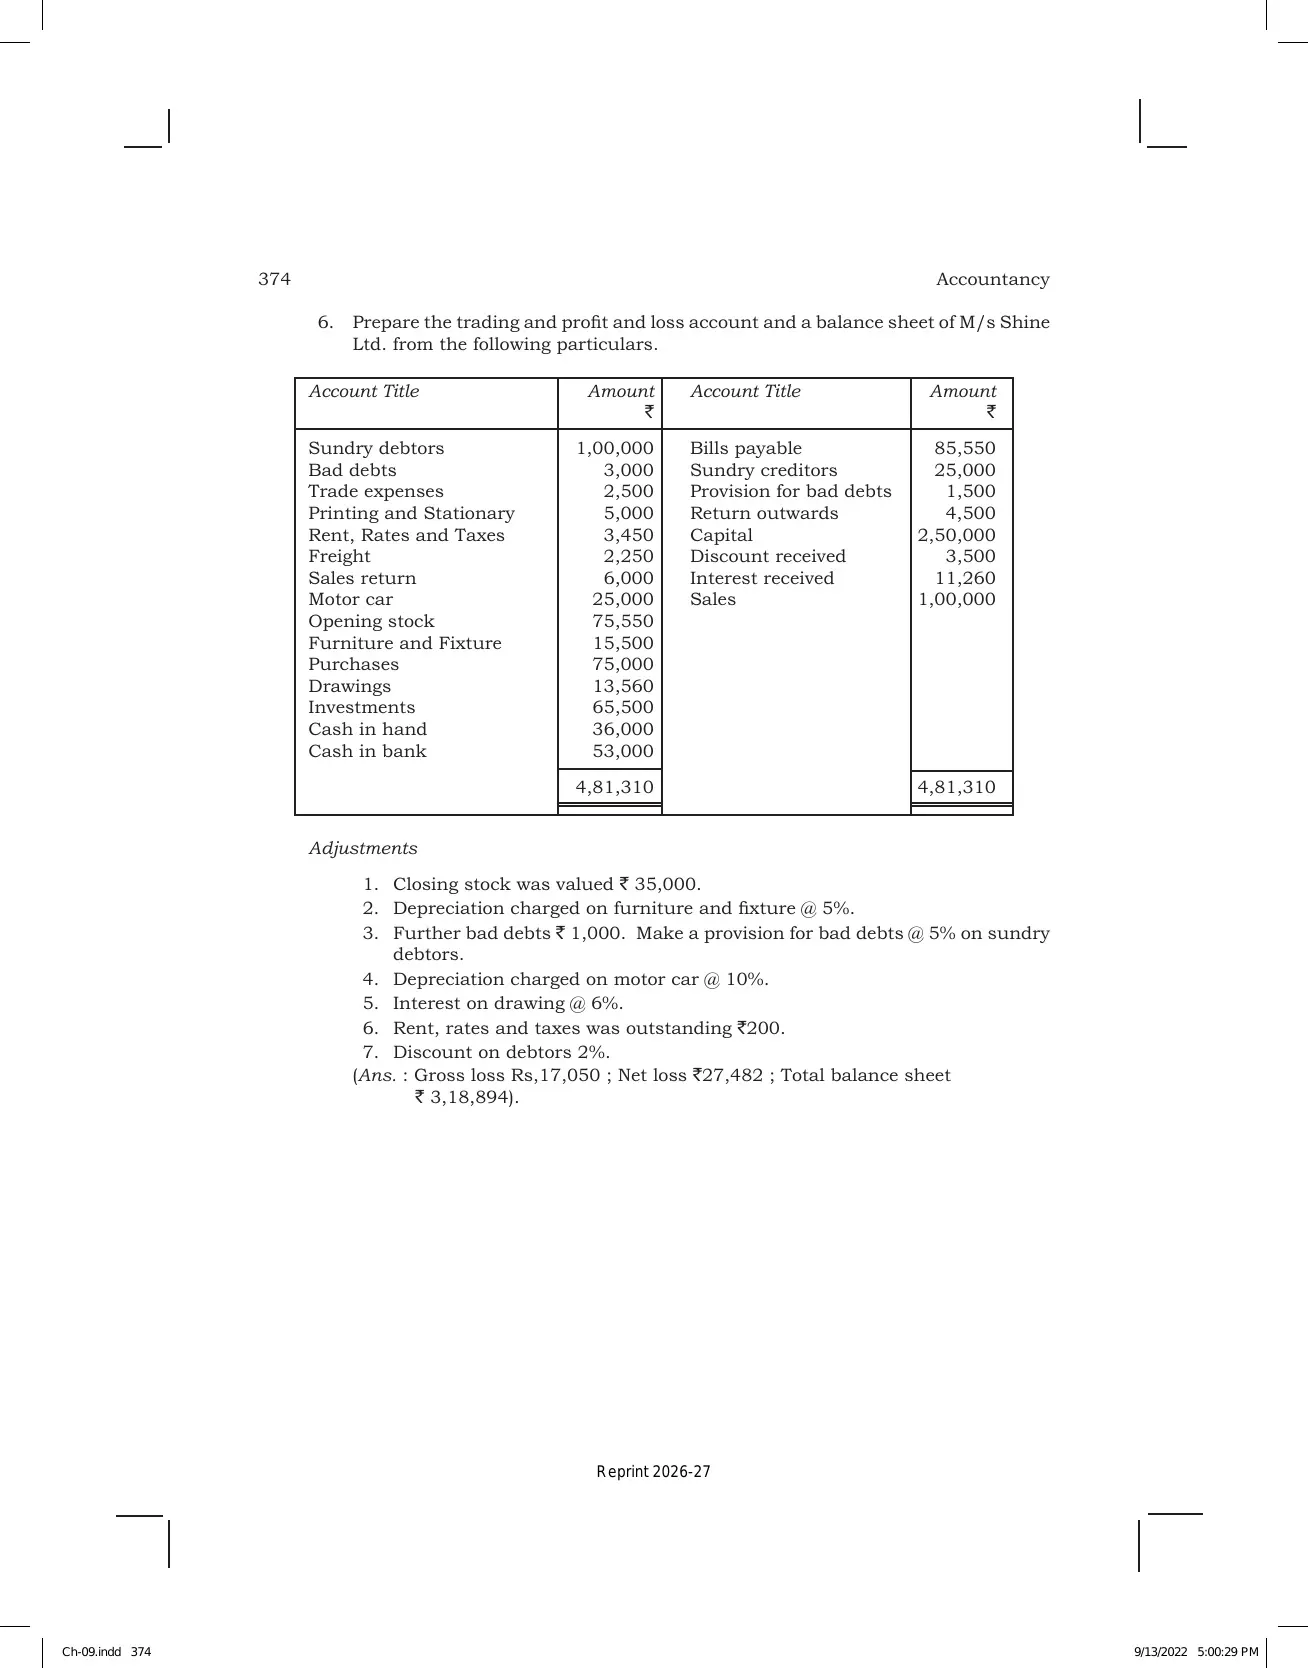
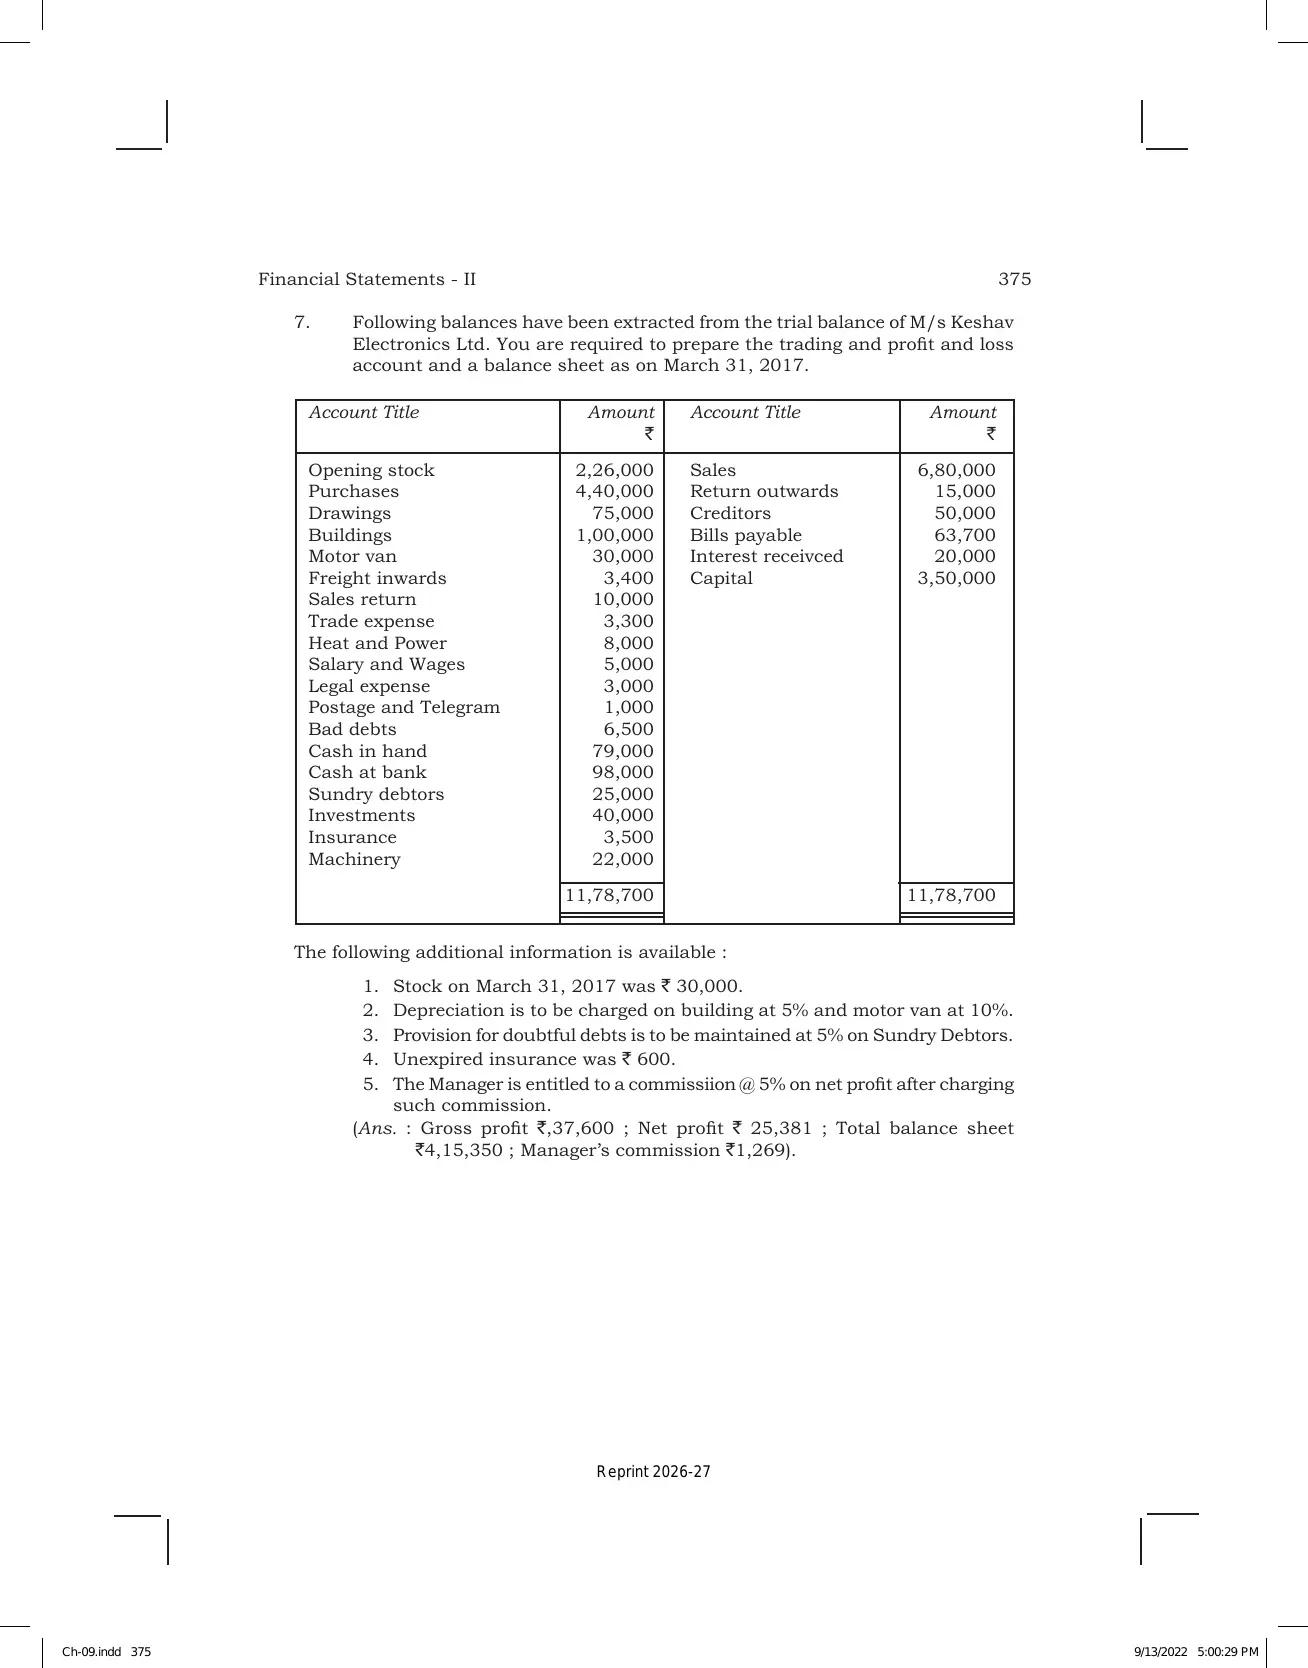
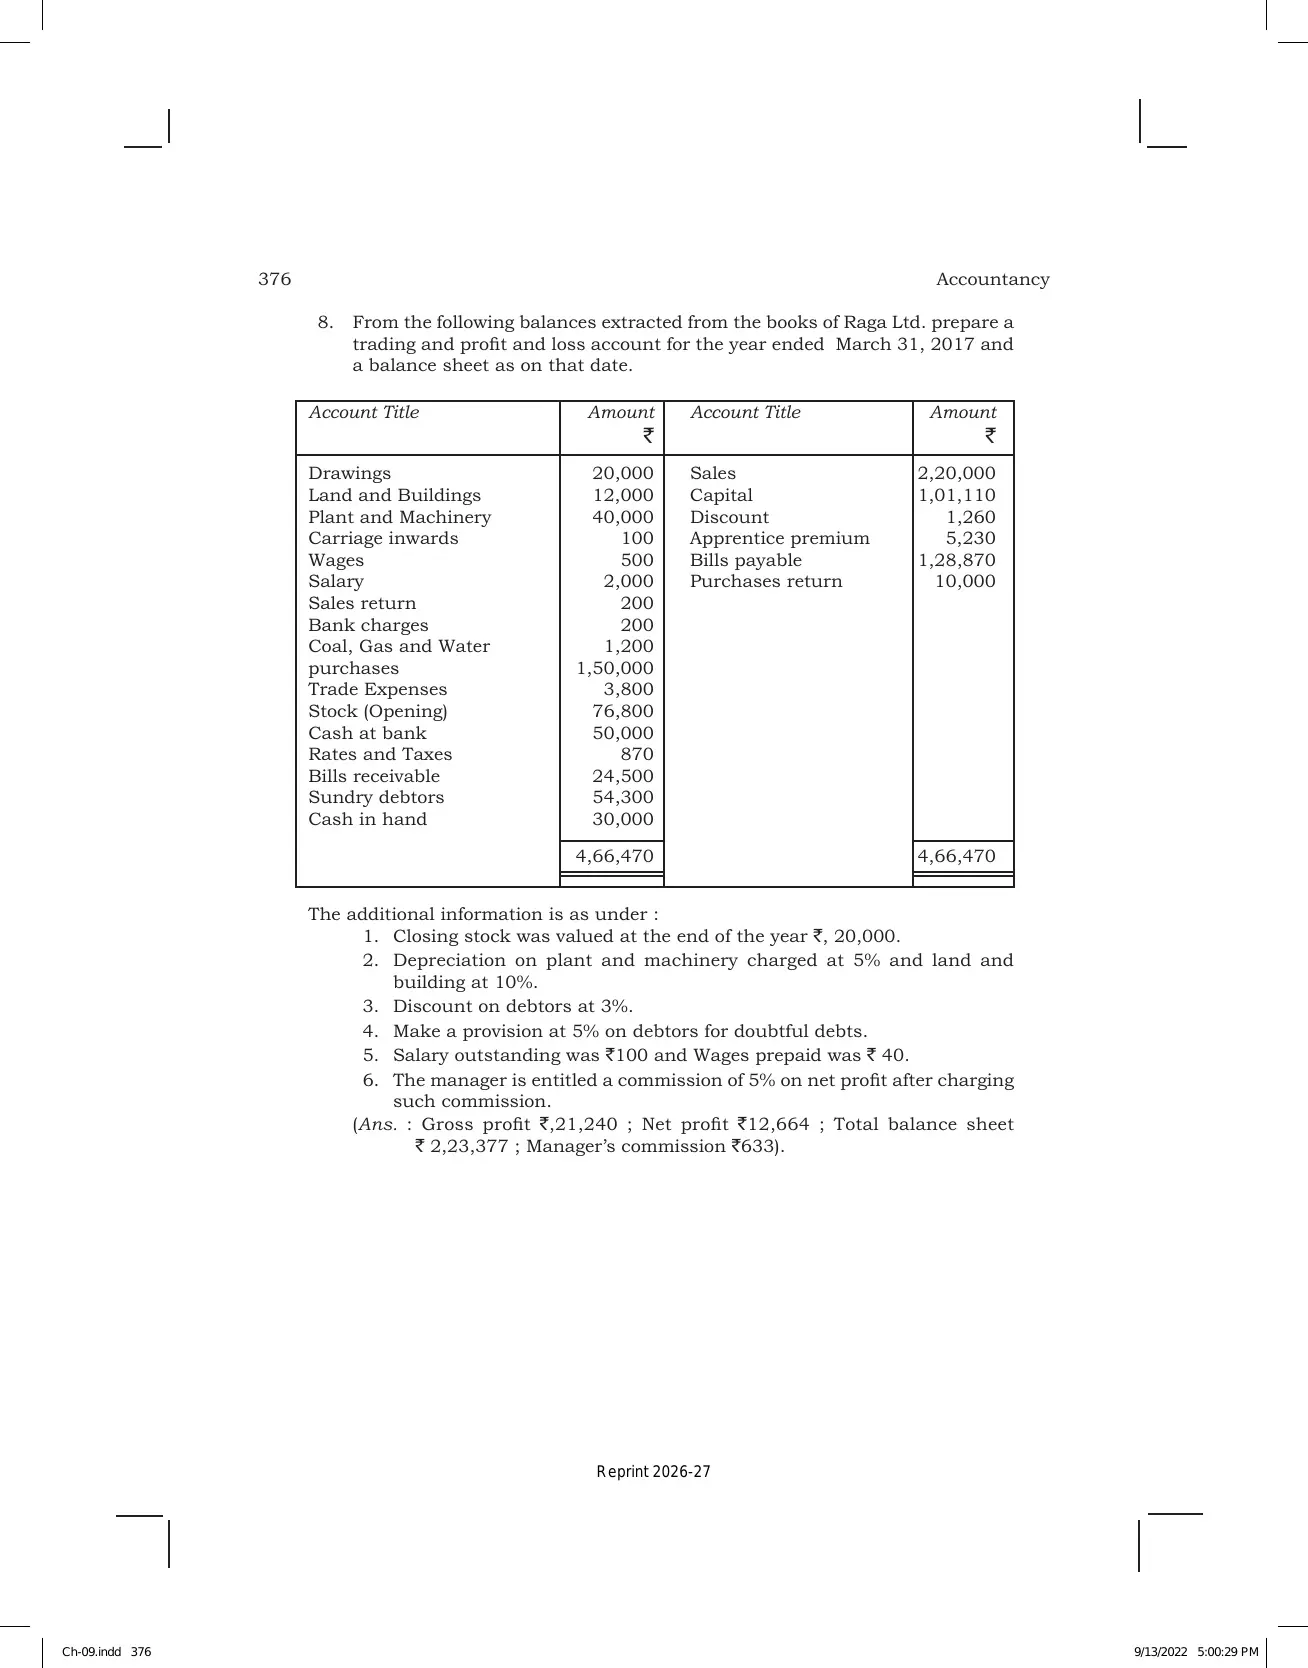
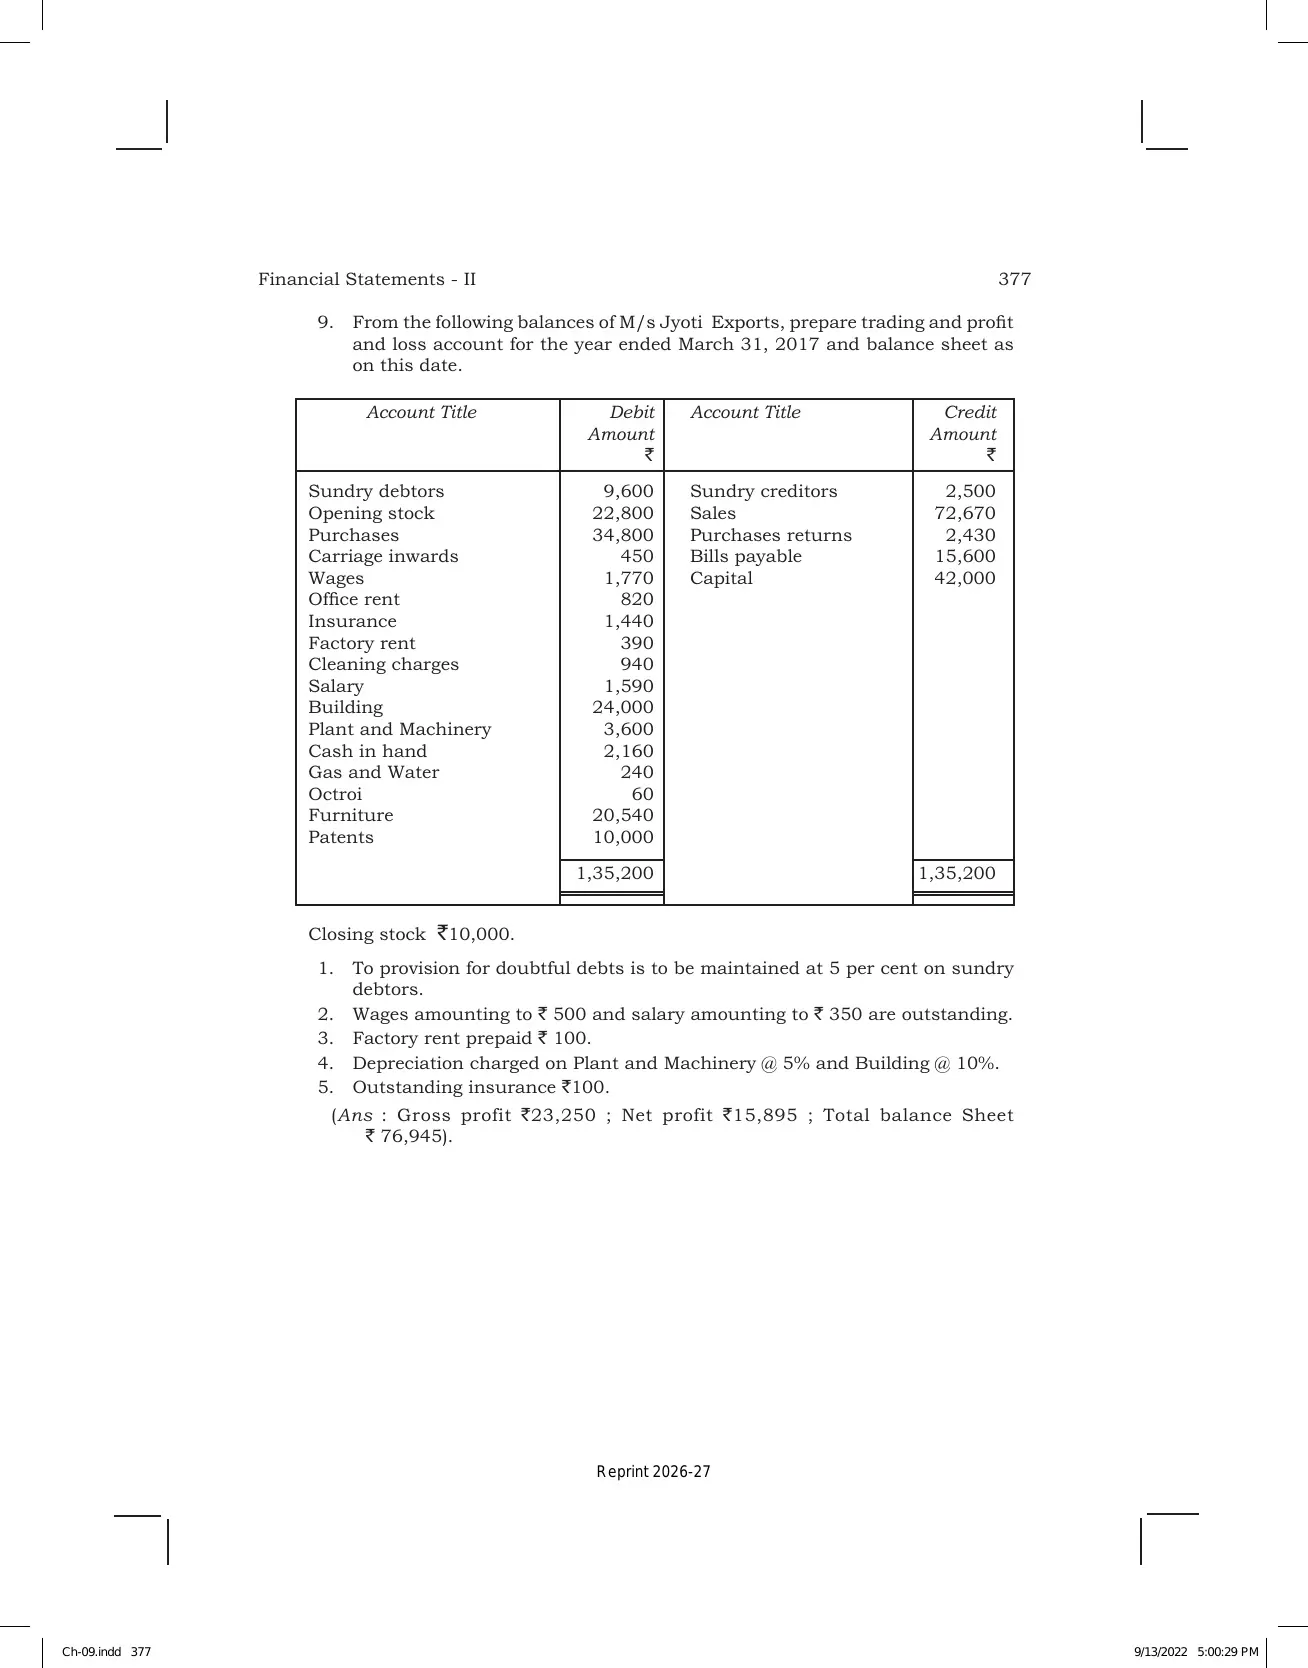
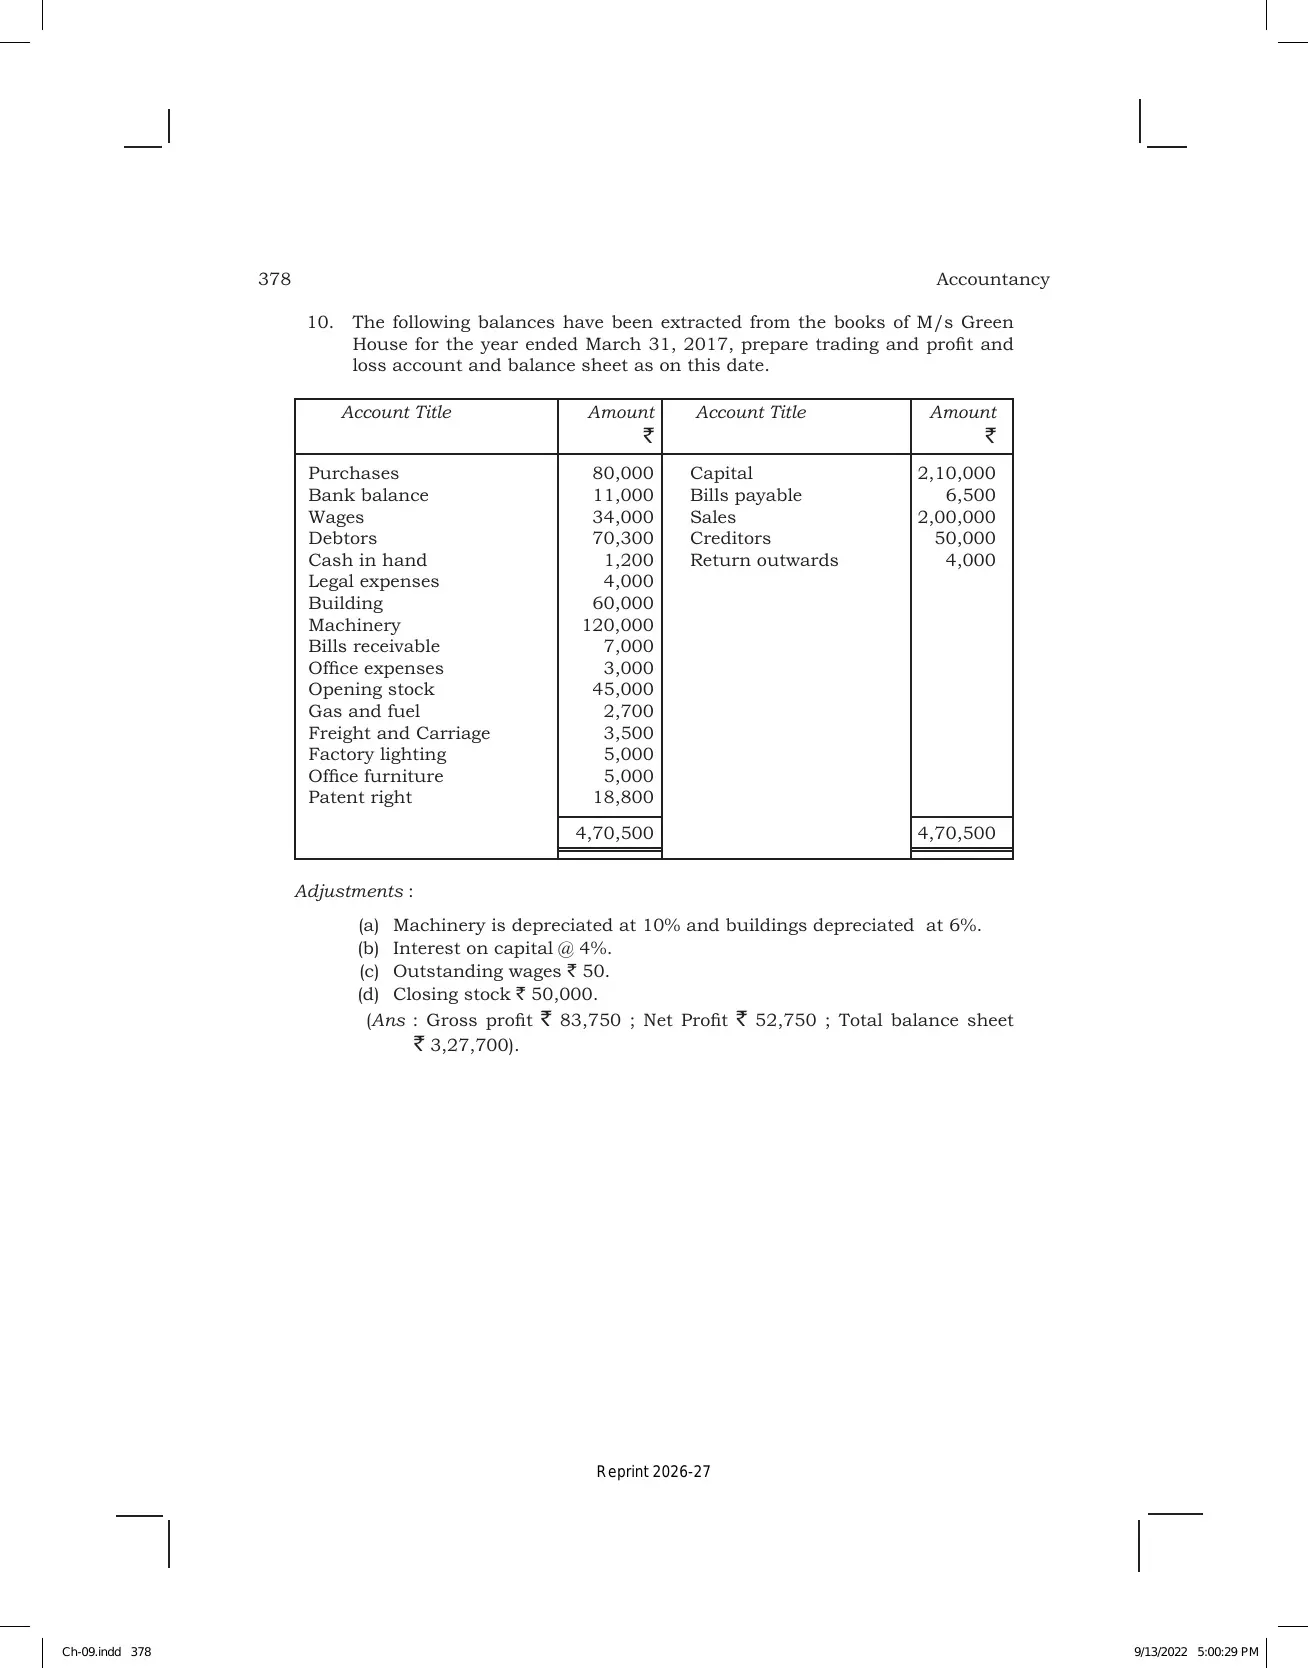
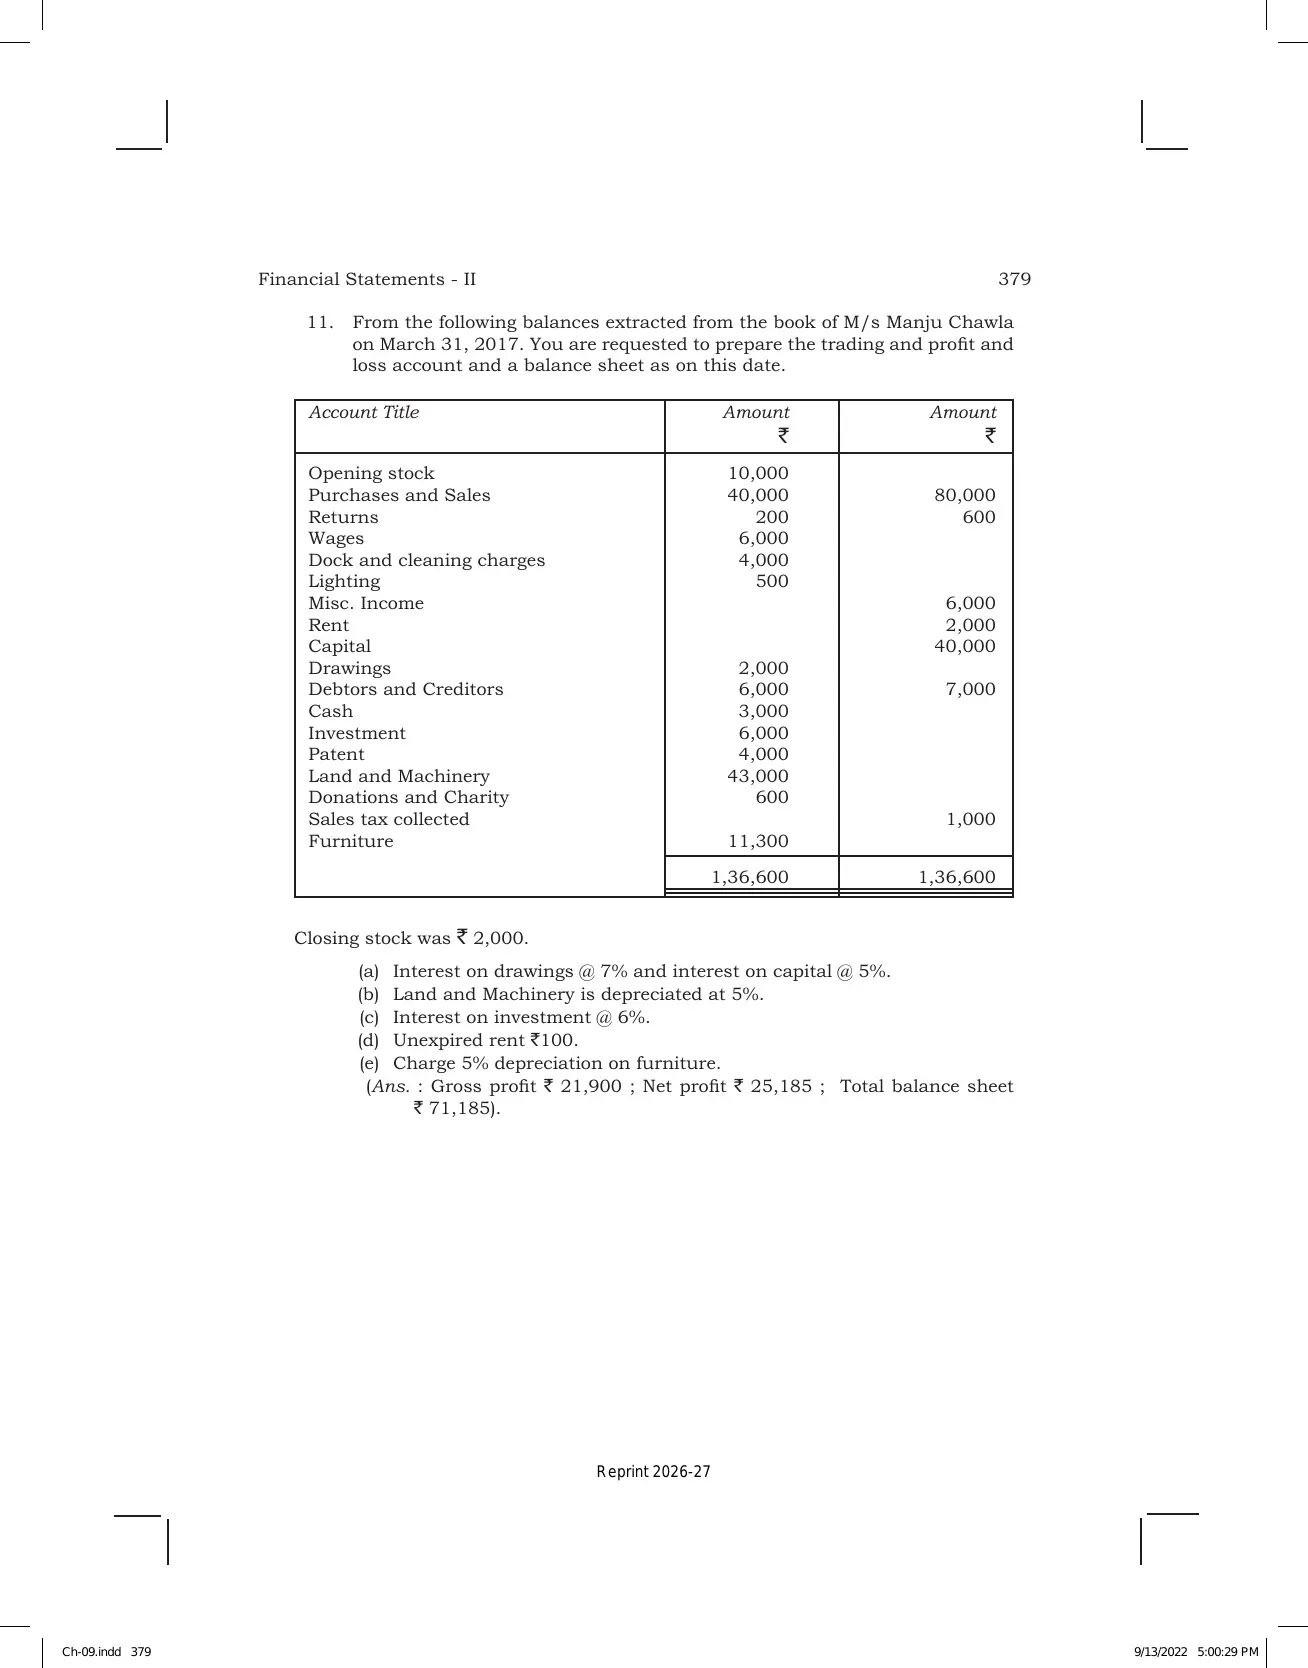
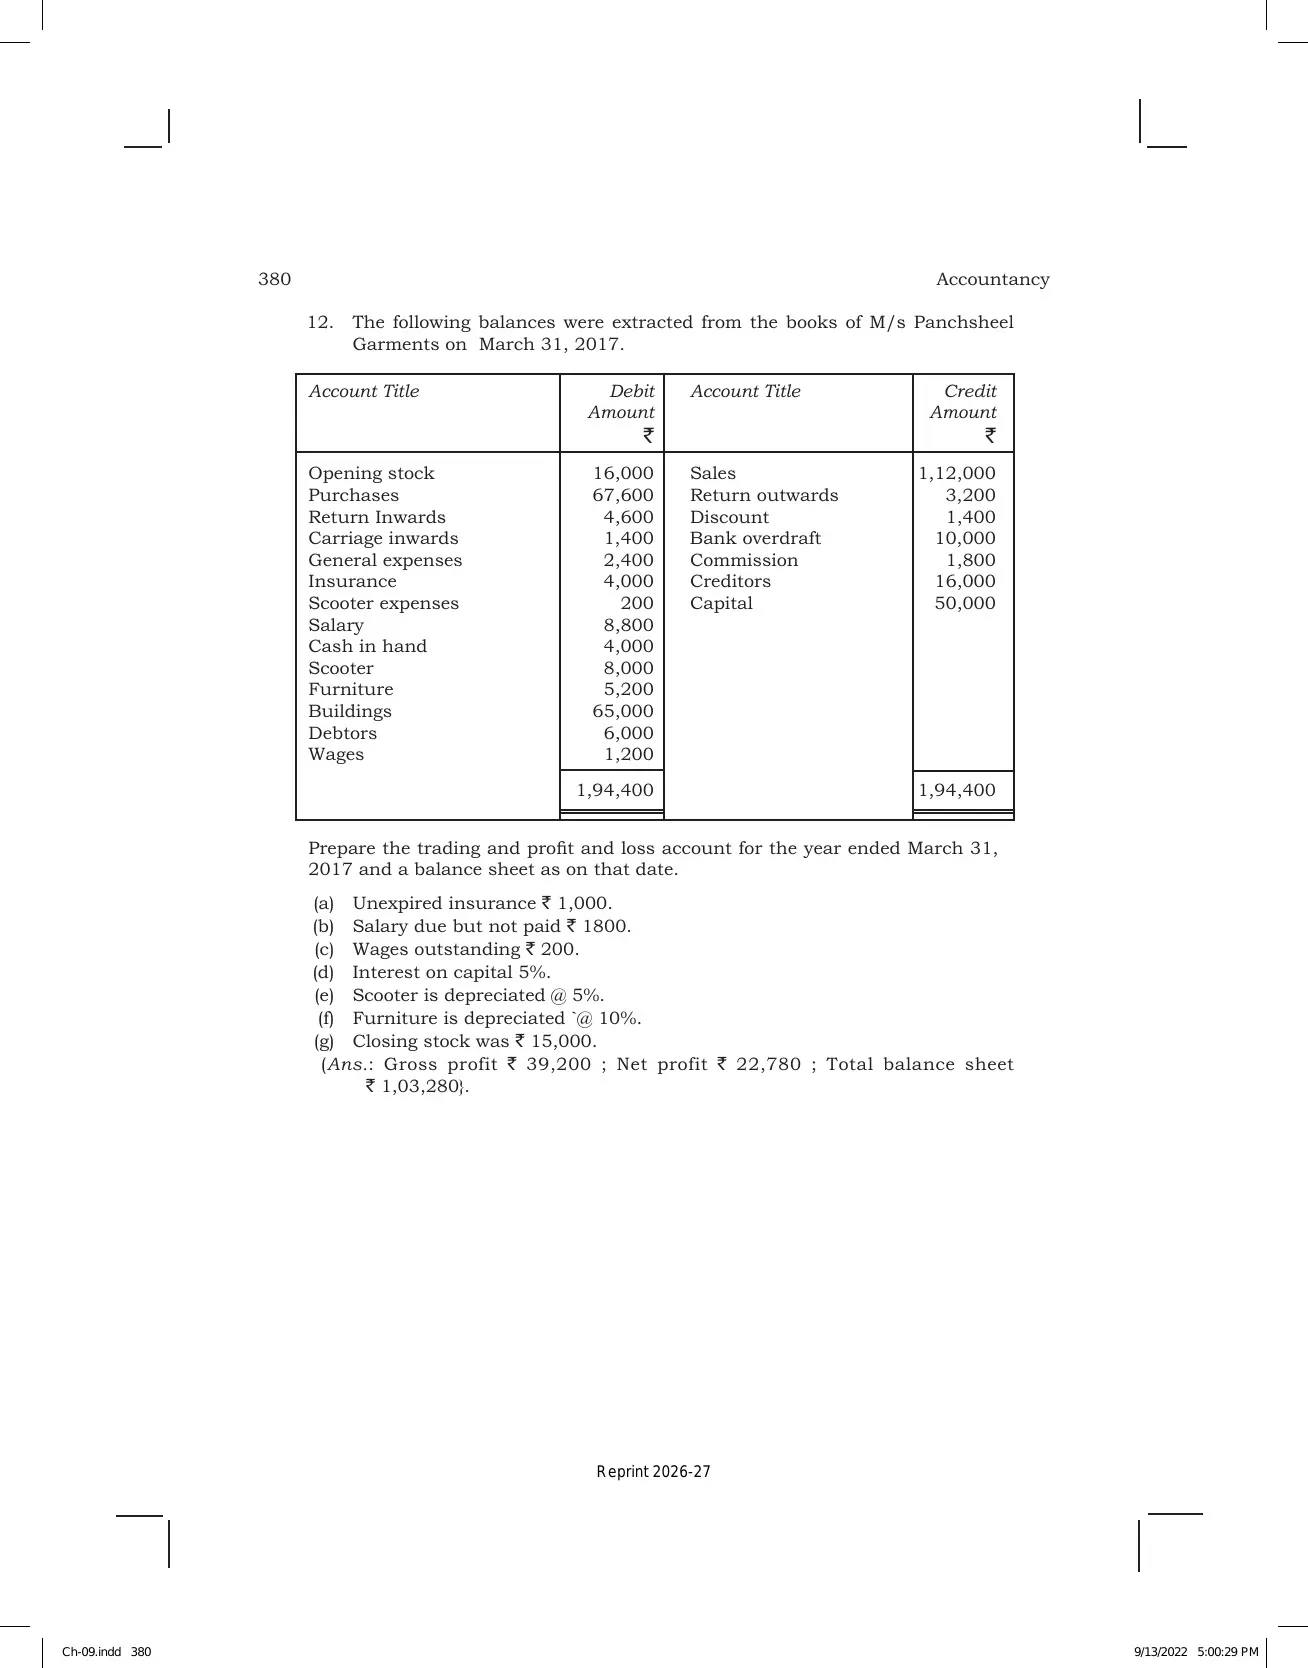
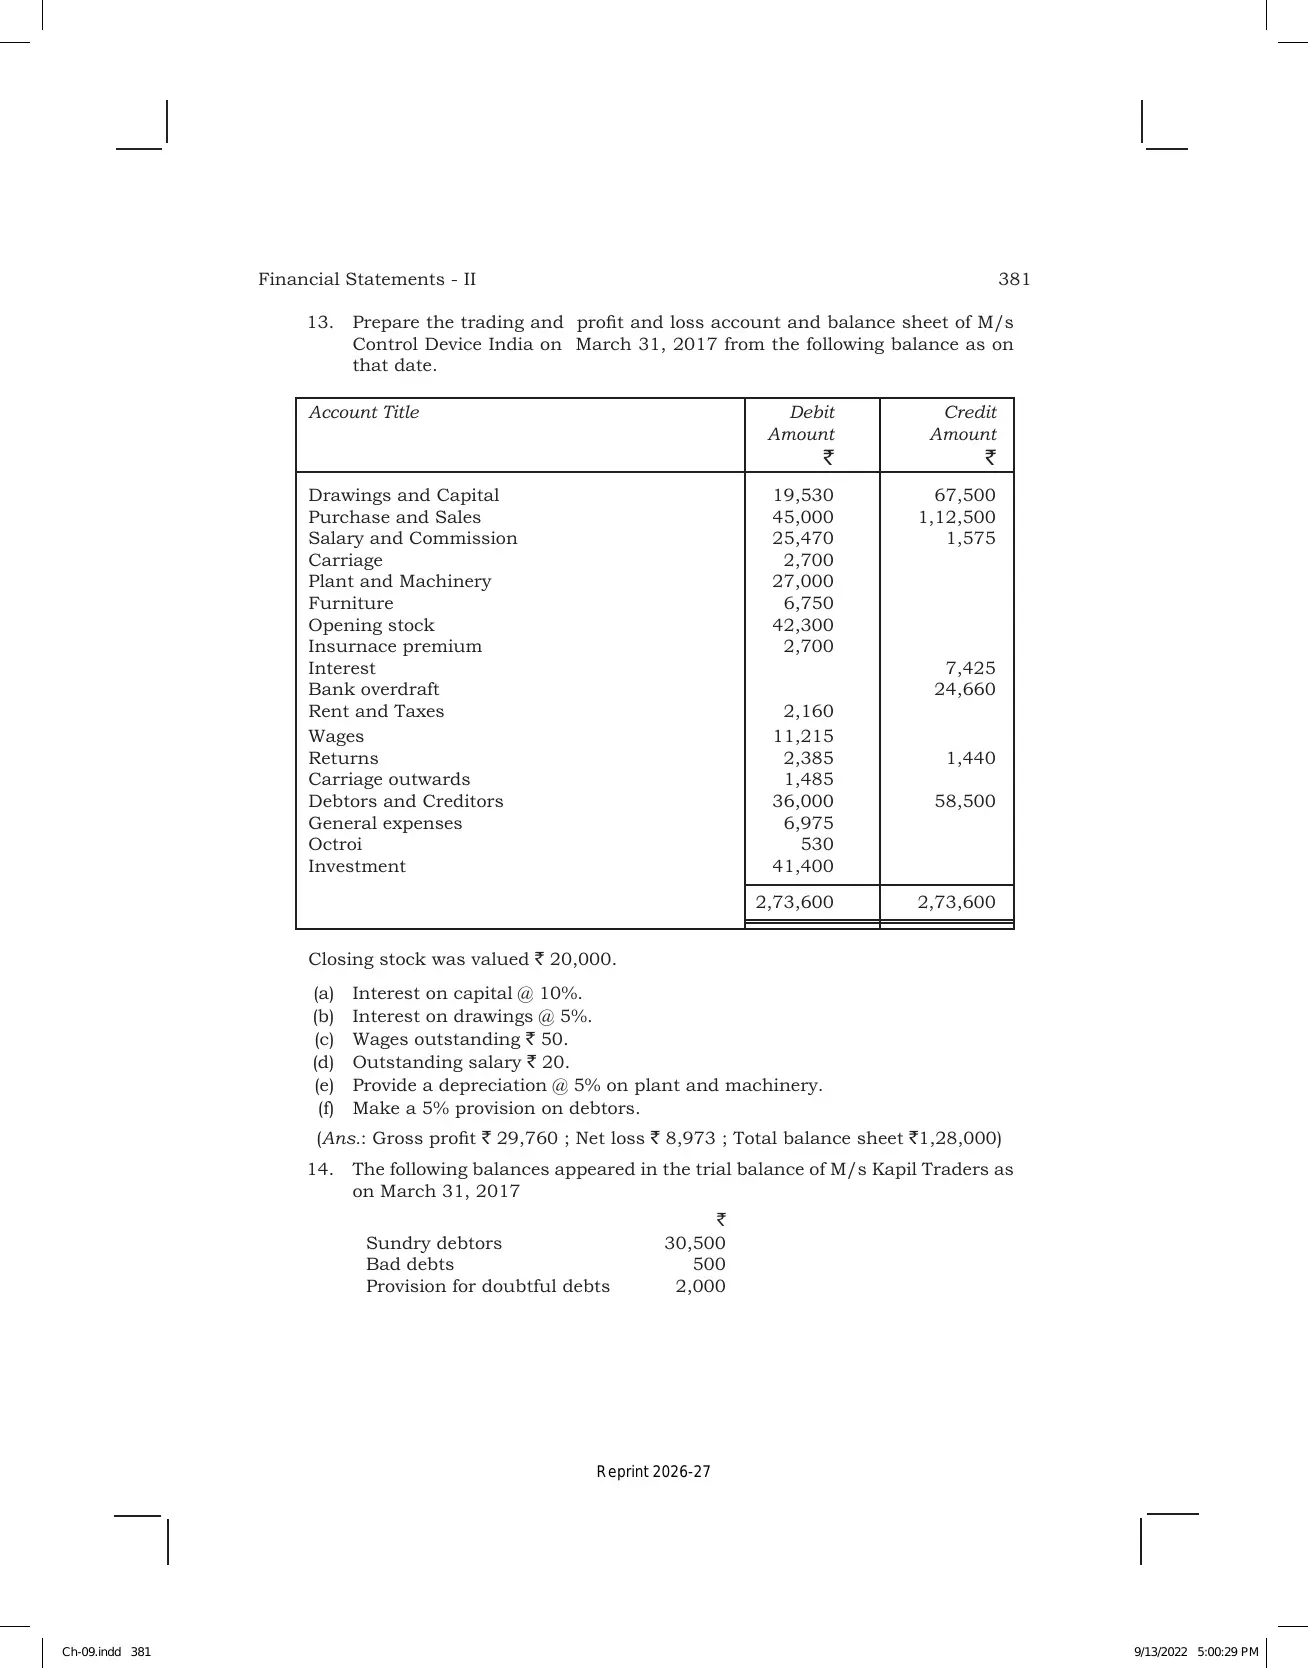
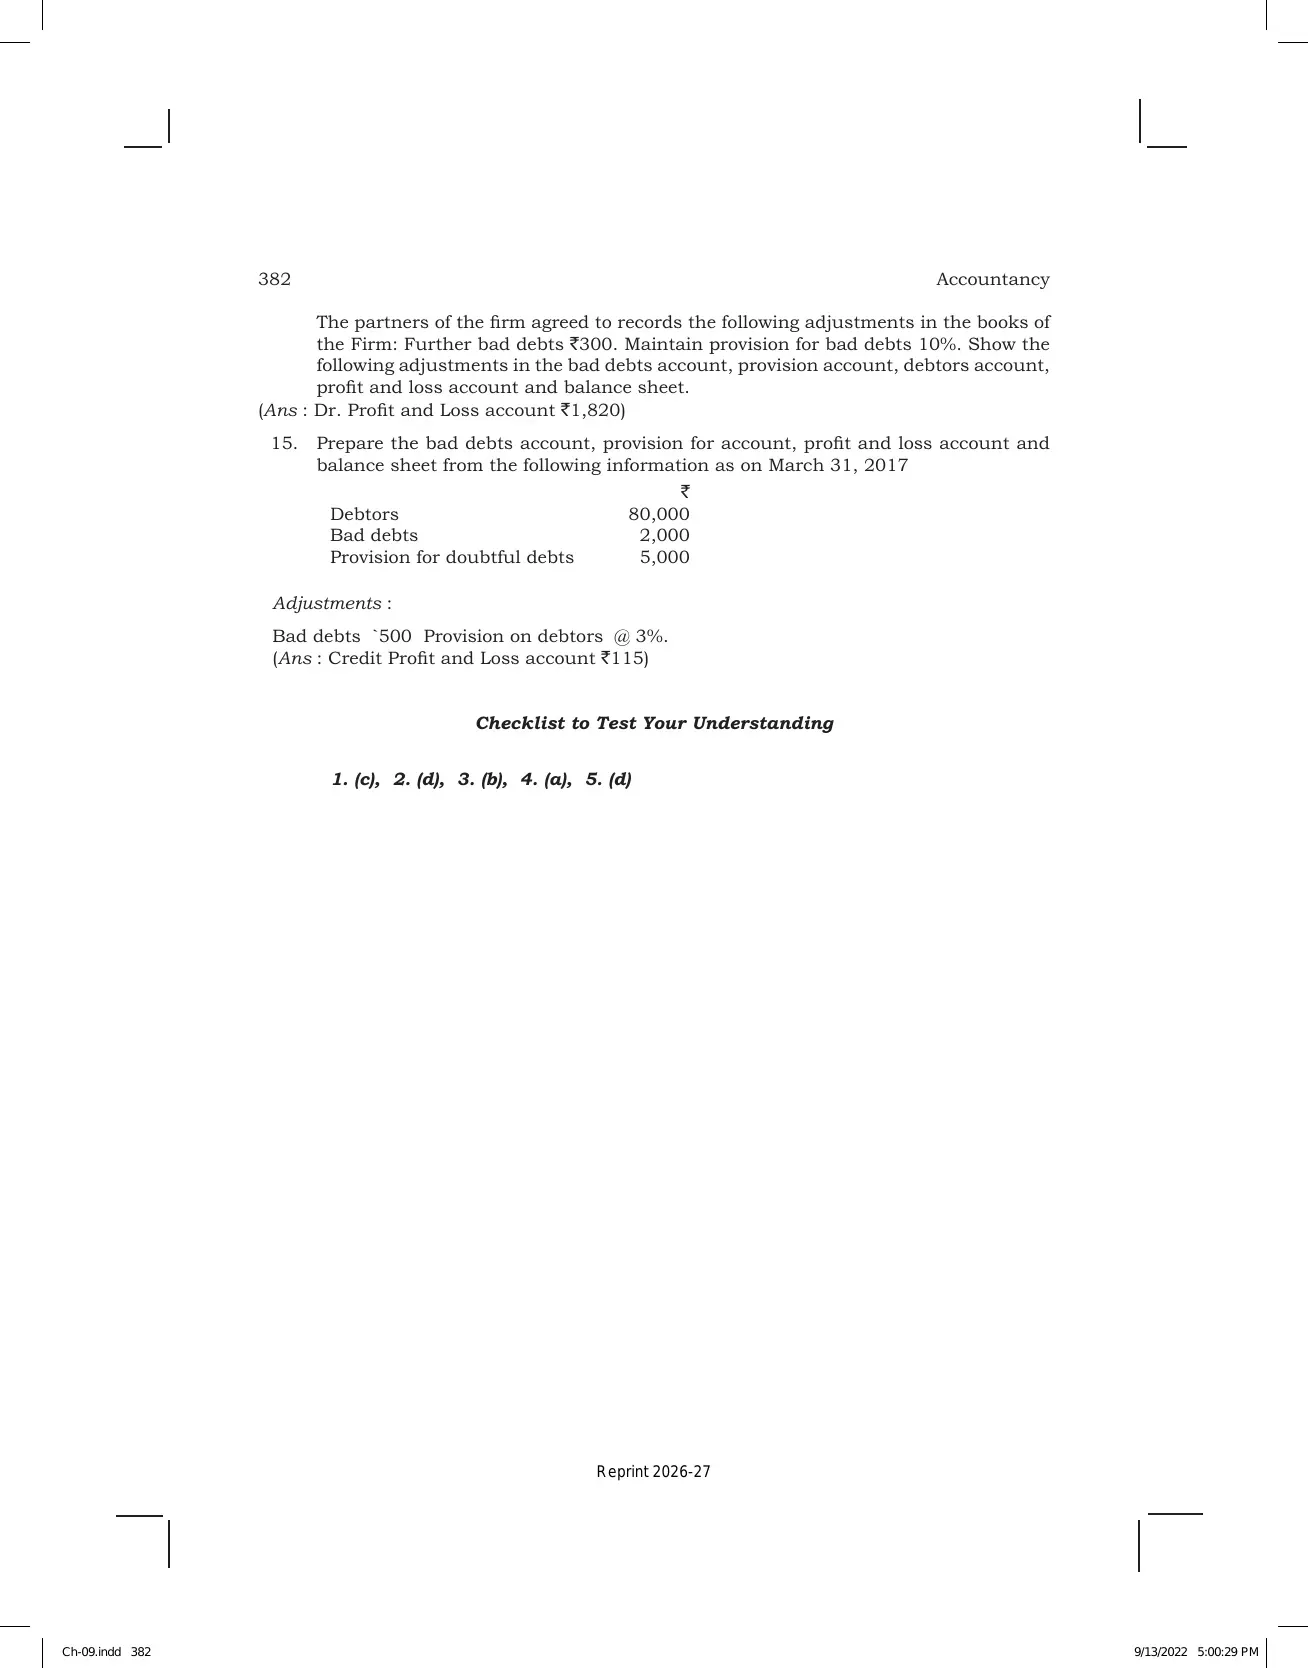
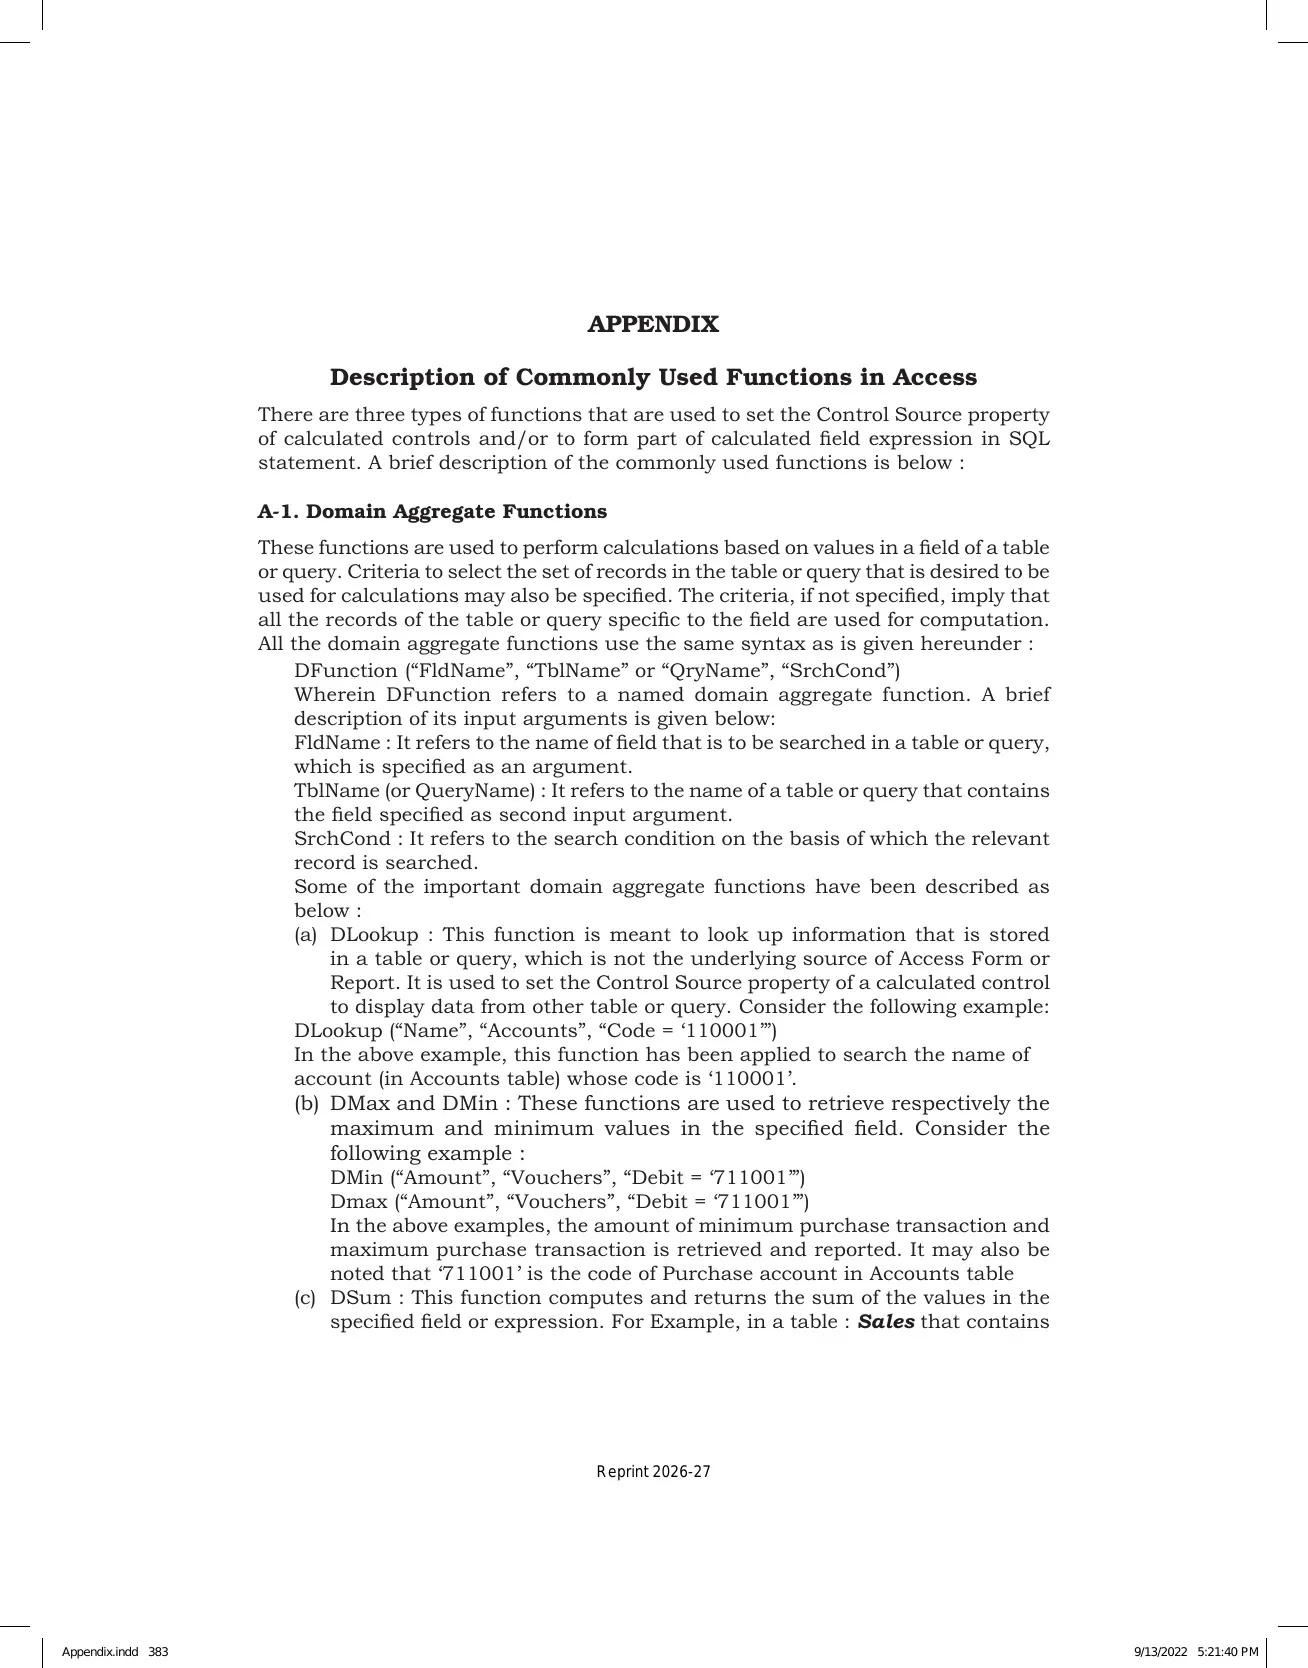
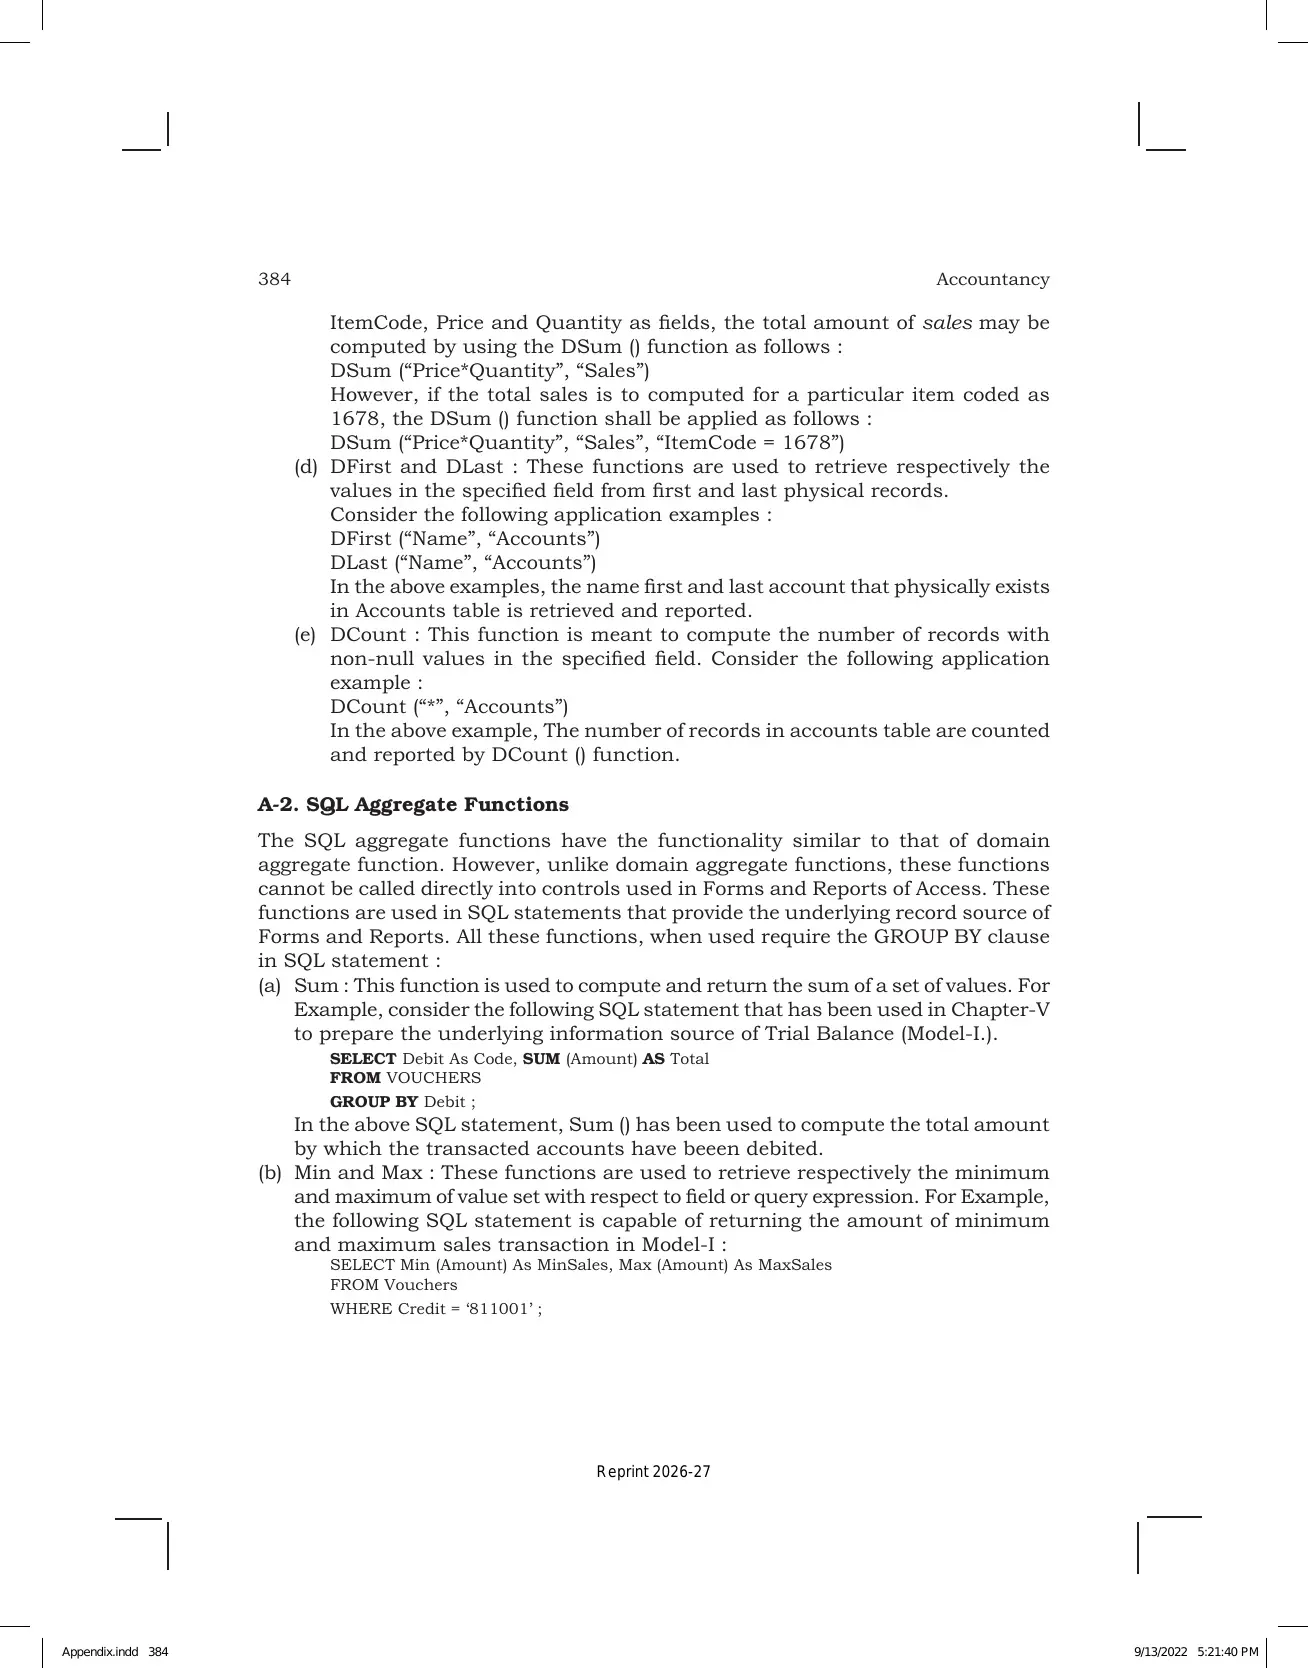
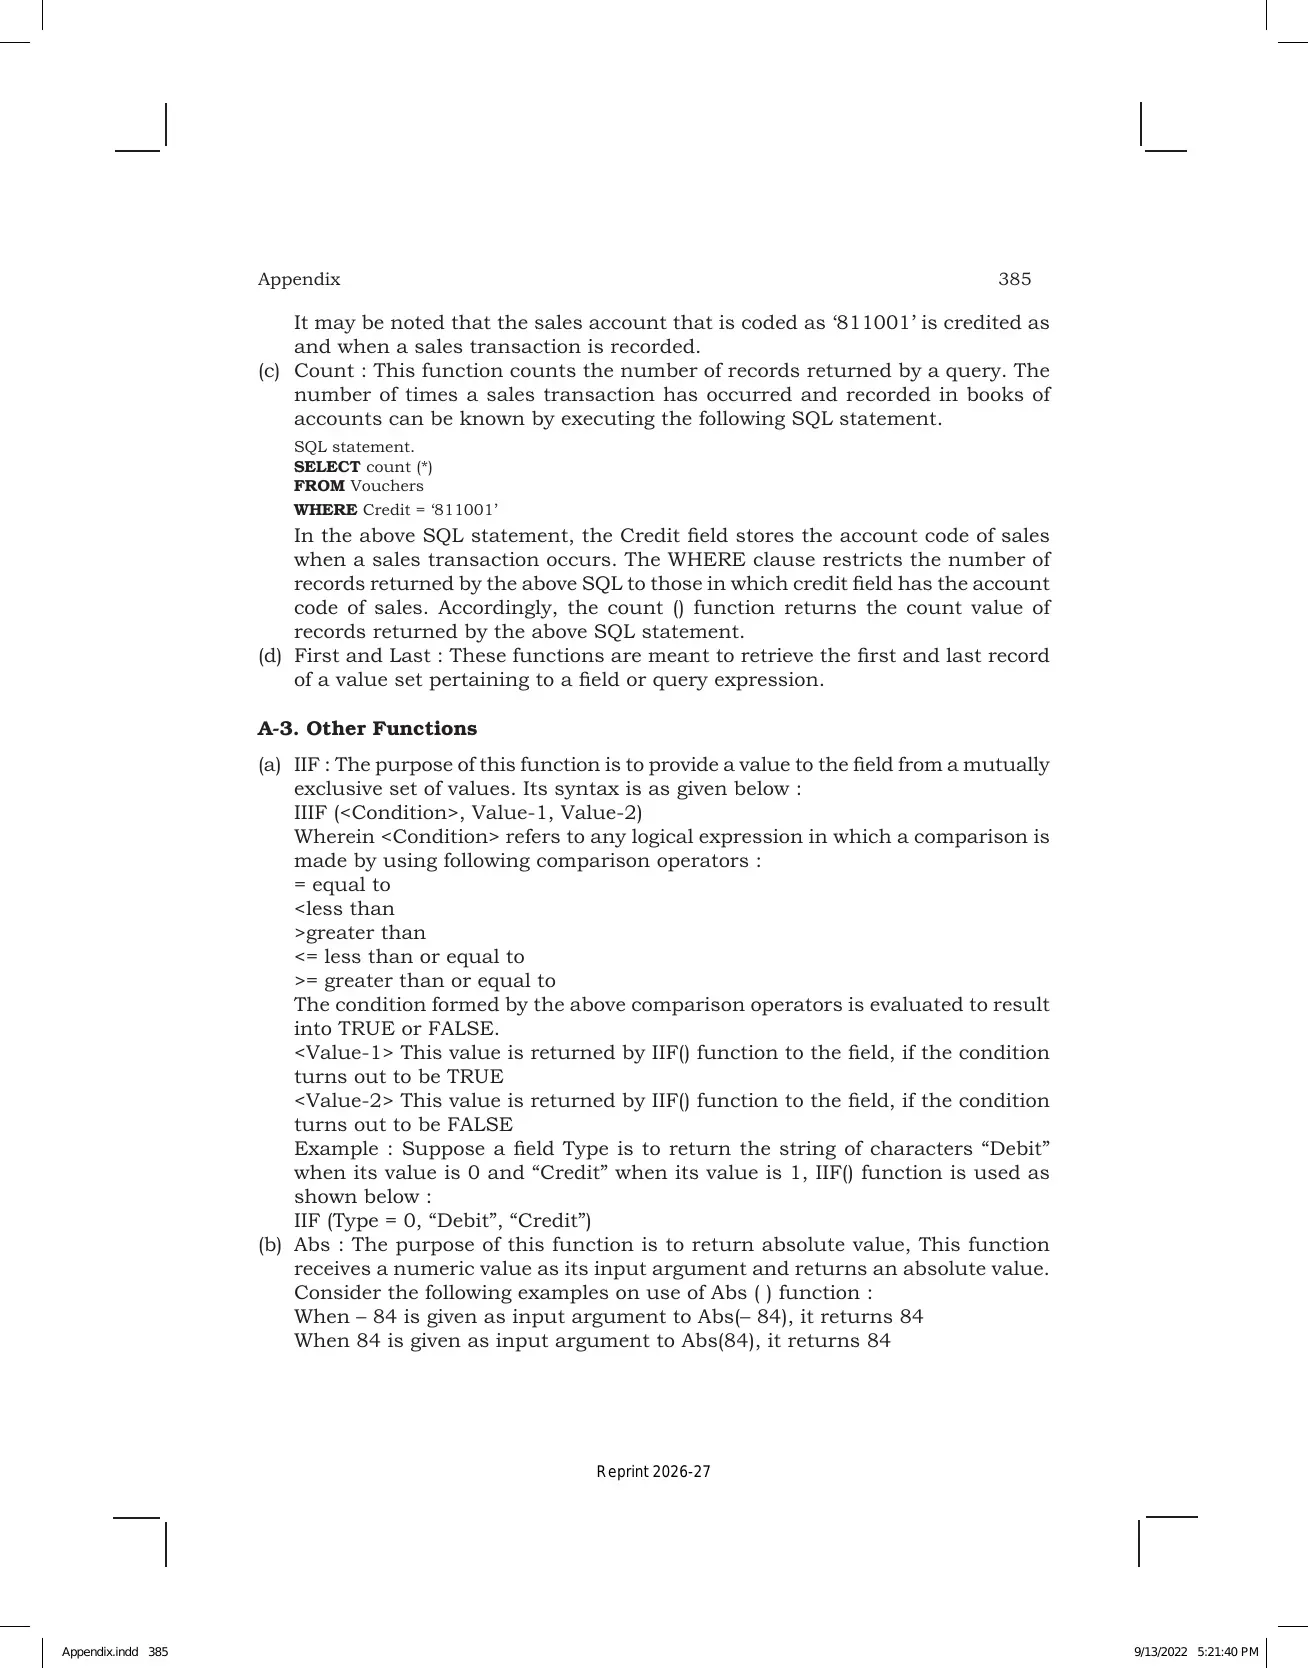
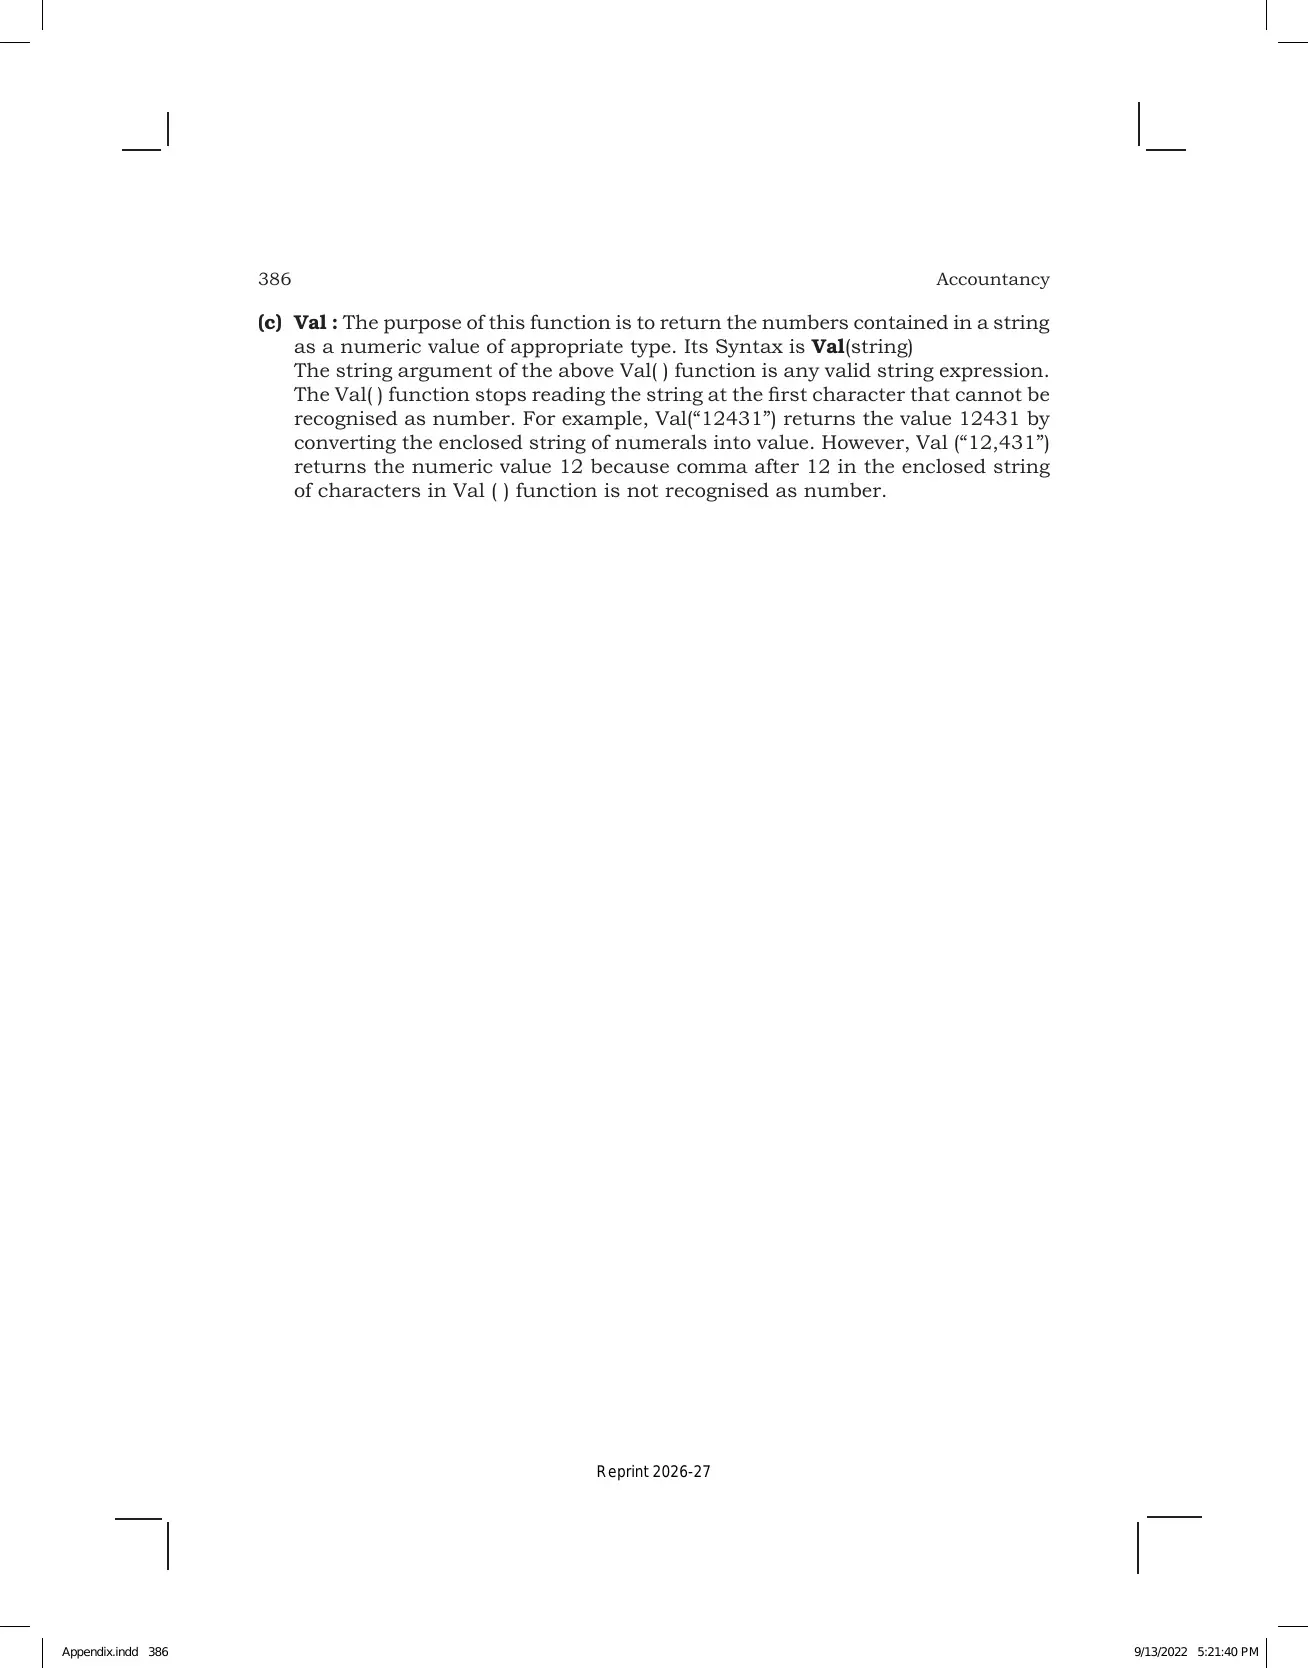
This Class 11 Accountancy NCERT Book PDF follows the 2026-27 NCERT reprint and helps students revise Financial Statements - II in one place.
Financial Statements - II Concepts Covered in the NCERT PDF
Financial Statements - II explains why final accounts need adjustments. NCERT uses accrual accounting to show that some expenses and incomes belong to the current year even when cash has not moved yet.
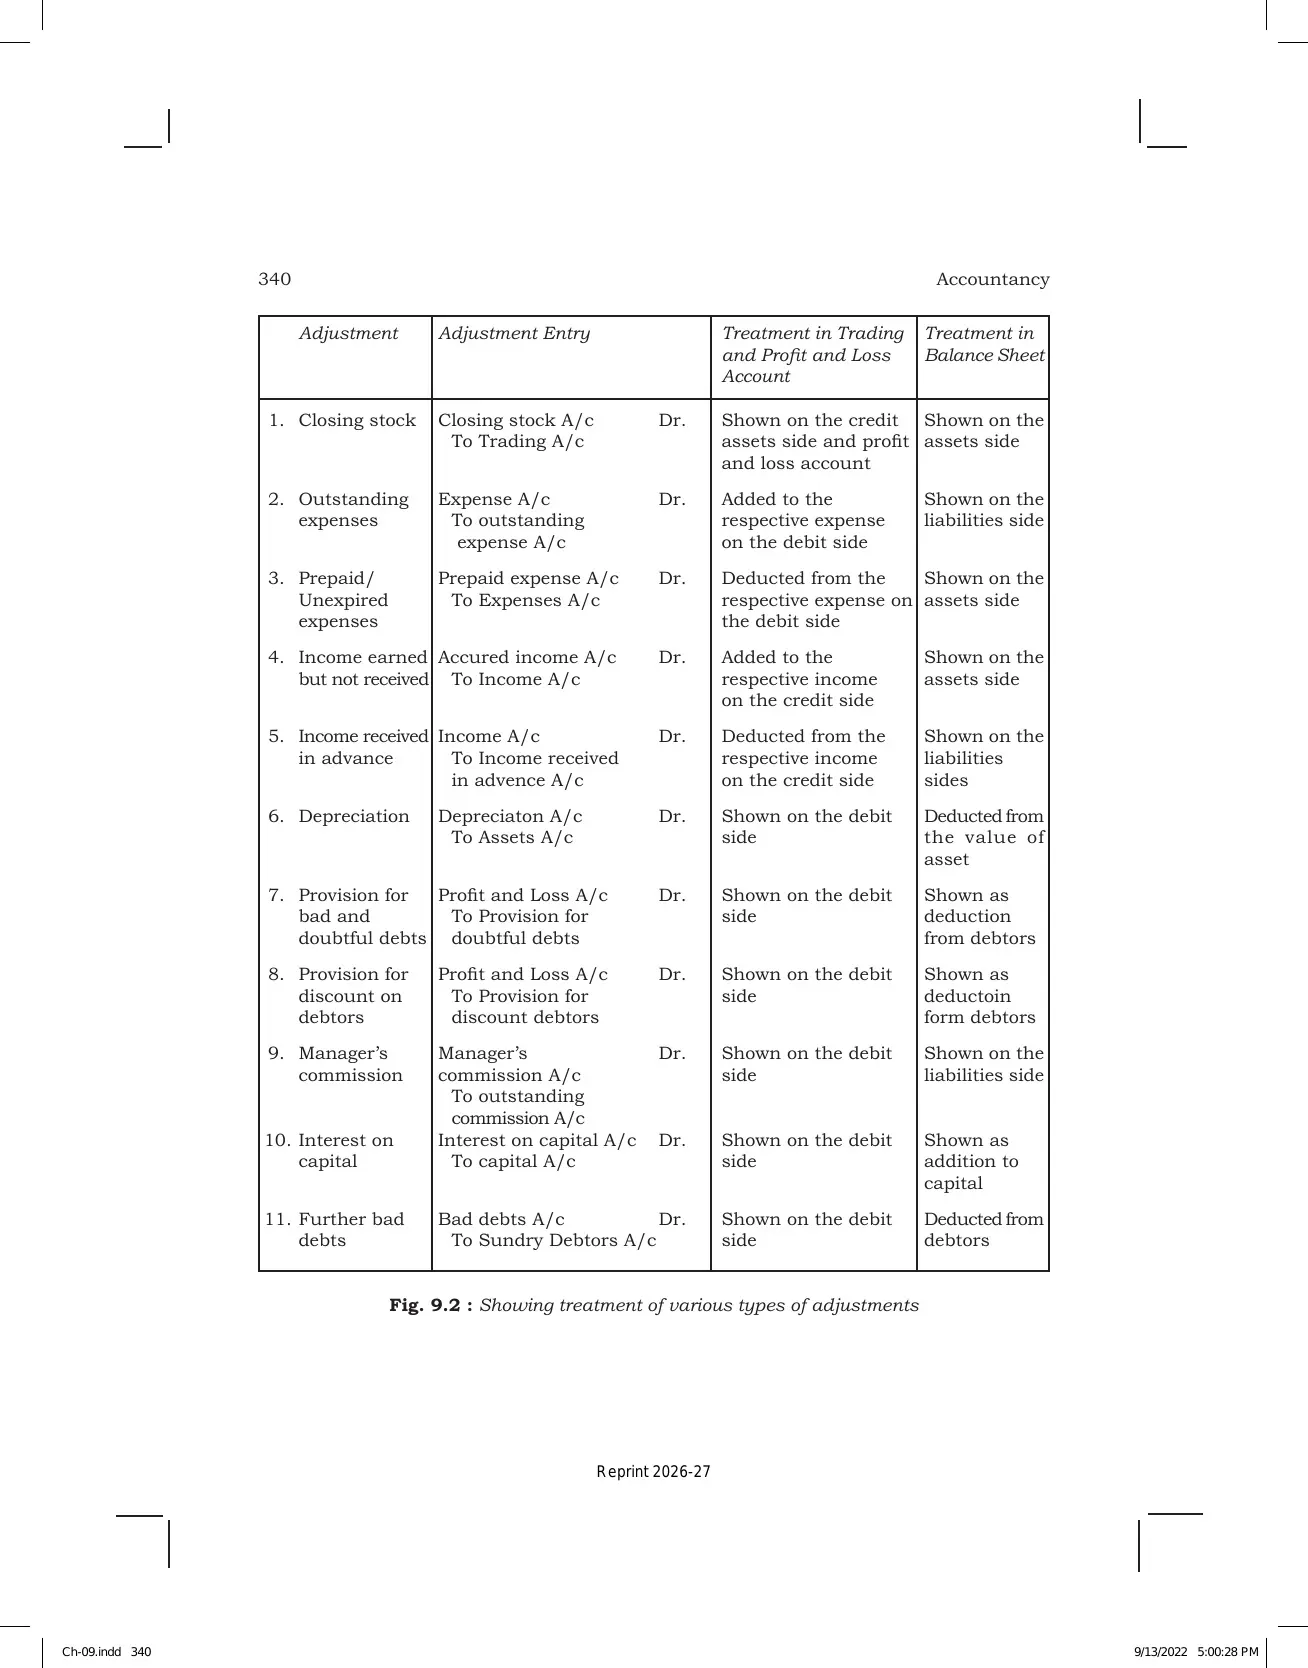
The main rule is simple: every adjustment has two effects. One effect goes to Trading Account or Profit and Loss Account. The other effect goes to the Balance Sheet.
| Adjustment | Profit and Loss Effect | Balance Sheet Effect |
|---|---|---|
| Outstanding expense | Add to related expense | Show as liability |
| Prepaid expense | Subtract from related expense | Show as asset |
| Accrued income | Add to related income | Show as asset |
| Income received in advance | Subtract from related income | Show as liability |
| Depreciation | Charge as expense | Reduce asset value |
Financial Statements - II Adjustment Order for Final Accounts
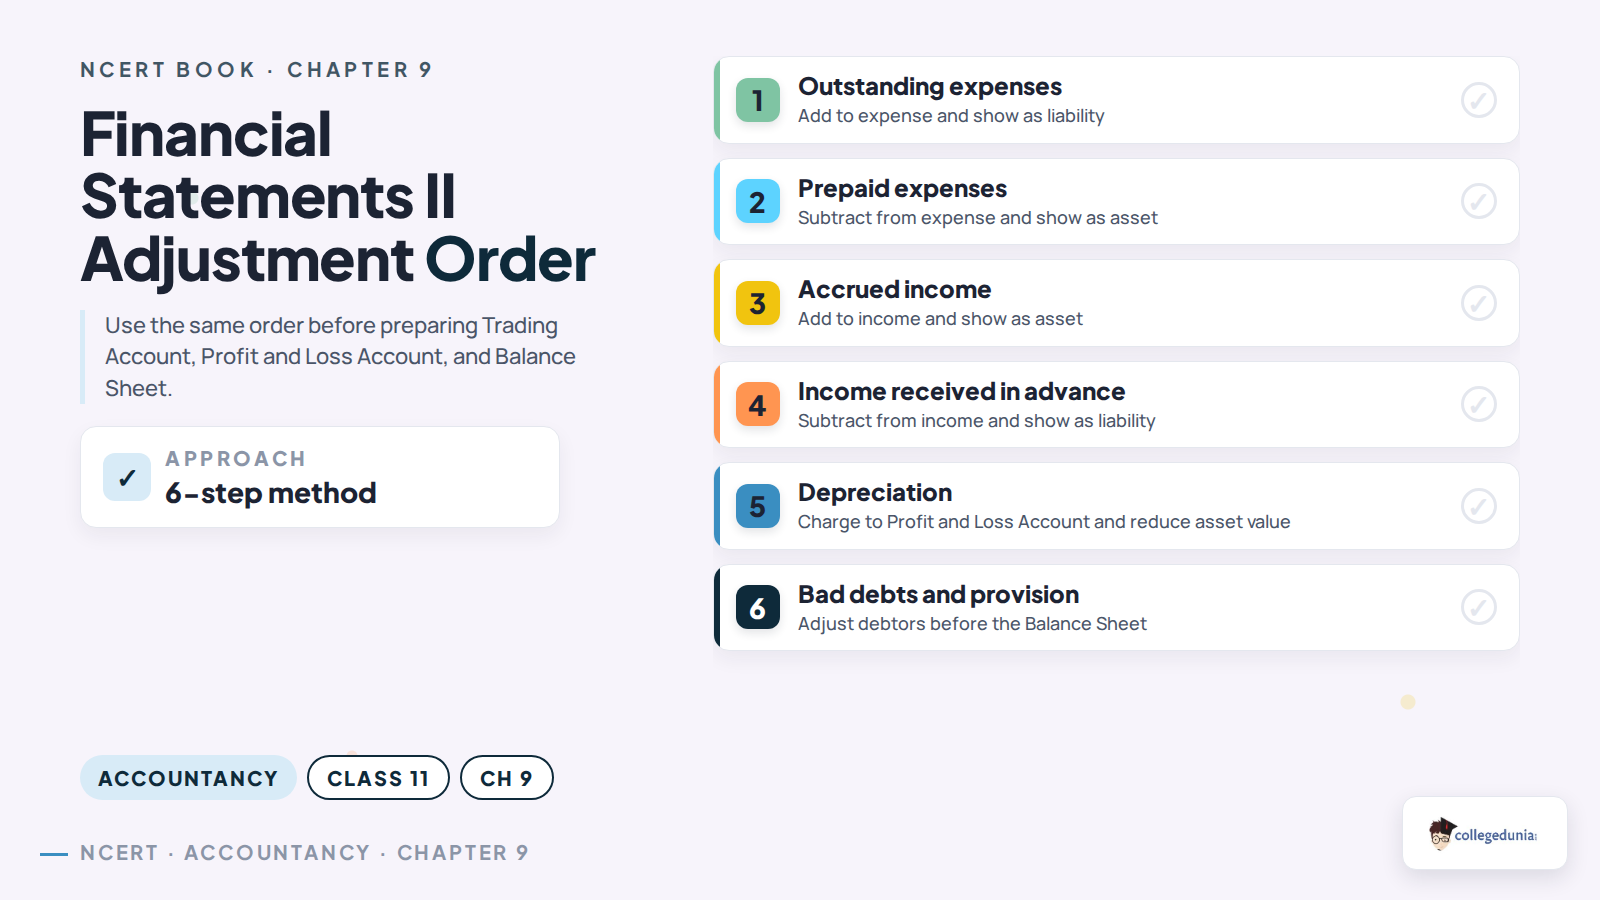
Students should not solve this chapter by guessing the place of each item. Work through the adjustment list in a fixed order. It keeps the Trading Account, Profit and Loss Account and Balance Sheet connected.
- Mark every adjustment given below the trial balance.
- Write the account affected in final accounts.
- Write the second effect as asset, liability or deduction.
- Prepare Trading Account before Profit and Loss Account.
- Transfer net profit or net loss to capital in the Balance Sheet.
Do not record only one side of an adjustment. That is the most common error in Financial Statements - II.
Financial Statements - II Adjustments Video for Class 11
Source: Magnet Brains on YouTube
Balance Sheet Links for Financial Statements - II Adjustments
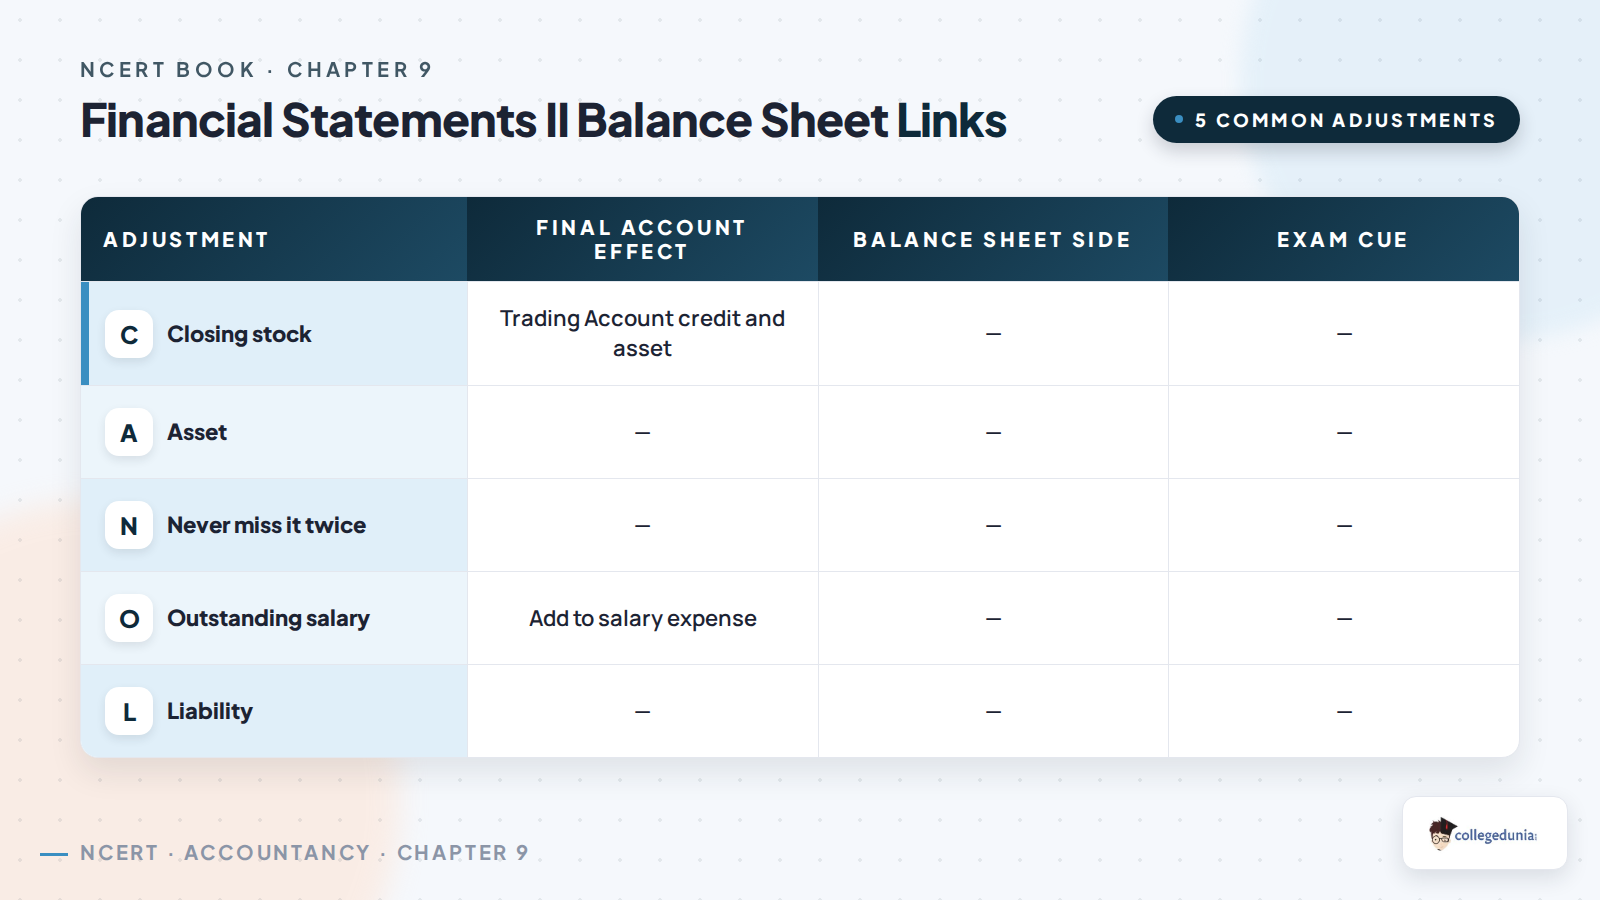
Balance Sheet errors usually happen when students finish the Profit and Loss Account but forget the matching asset or liability. Every adjustment must be traced to the Balance Sheet before the answer is complete.
- Asset side: prepaid expenses, accrued income and closing stock.
- Liability side: outstanding expenses and income received in advance.
- Deduction from asset: depreciation, bad debts and provision for doubtful debts.
- Capital adjustment: net profit, drawings and interest on capital.
How to Study the Financial Statements - II NCERT PDF
Read this NCERT chapter with a rough final-account format beside you. The chapter is practical, so formats matter as much as definitions.
- Revise Financial Statements - I before starting adjustments.
- Learn the double effect table for each adjustment.
- Solve one illustration slowly before timing yourself.
- Check whether the Balance Sheet totals match.
- Write short notes for commission and provision adjustments.
The best revision test is a balanced Balance Sheet. If it does not match, recheck the second effect of every adjustment.
Financial Statements - II Class 11 Related Resources
| Resource | Best use |
|---|---|
| Financial Statements - II Class 11 Notes | Revise every adjustment and final-account format |
| Financial Statements - II Class 11 Handwritten Notes | Use handwritten notes for quick adjustment revision |
| Financial Statements - I Class 11 NCERT Book PDF | Revise final accounts without adjustments first |
All Class 11 Accountancy NCERT Book Chapters
| Chapter | NCERT Book PDF |
|---|---|
| 1 | Introduction to Accounting |
| 2 | Theory Base of Accounting |
| 3 | Recording of Transactions - I |
| 4 | Recording of Transactions - II |
| 5 | Bank Reconciliation Statement |
| 6 | Trial Balance and Rectification of Errors |
| 7 | Depreciation, Provisions and Reserves |
| 8 | Financial Statements - I |
| 9 | Financial Statements - II |
Financial Statements - II Class 11 NCERT Book FAQs
Ques. What does Financial Statements - II cover in Class 11 Accountancy?
Ans. It covers adjustments for final accounts, including outstanding expenses, prepaid expenses, accrued income, depreciation, bad debts, provisions, manager's commission and interest on capital.
Ques. Why are adjustments needed while preparing financial statements?
Ans. Adjustments are needed because final accounts follow accrual accounting. Income and expenses must be recorded in the year to which they belong.
Ques. What is the double effect of an adjustment?
Ans. Double effect means one part changes profit and the other part changes the Balance Sheet. For example, outstanding salary increases salary expense and also appears as a liability.
Ques. Which accounts are prepared in Financial Statements - II?
Ans. Students prepare the Trading Account, Profit and Loss Account and Balance Sheet after considering all year-end adjustments.
Ques. Is this PDF based on the 2026-27 NCERT book?
Ans. Yes. The PDF is from the Class 11 Accountancy NCERT reprint for the 2026-27 academic session.


Comments